For Los Angeles buyers adding a Boca Raton residence, thoughtful ownership begins before closing. Coordinate the deed, trust, insurance review, and succession plan while keeping Florida homestead benefits distinct from second-home ownership.
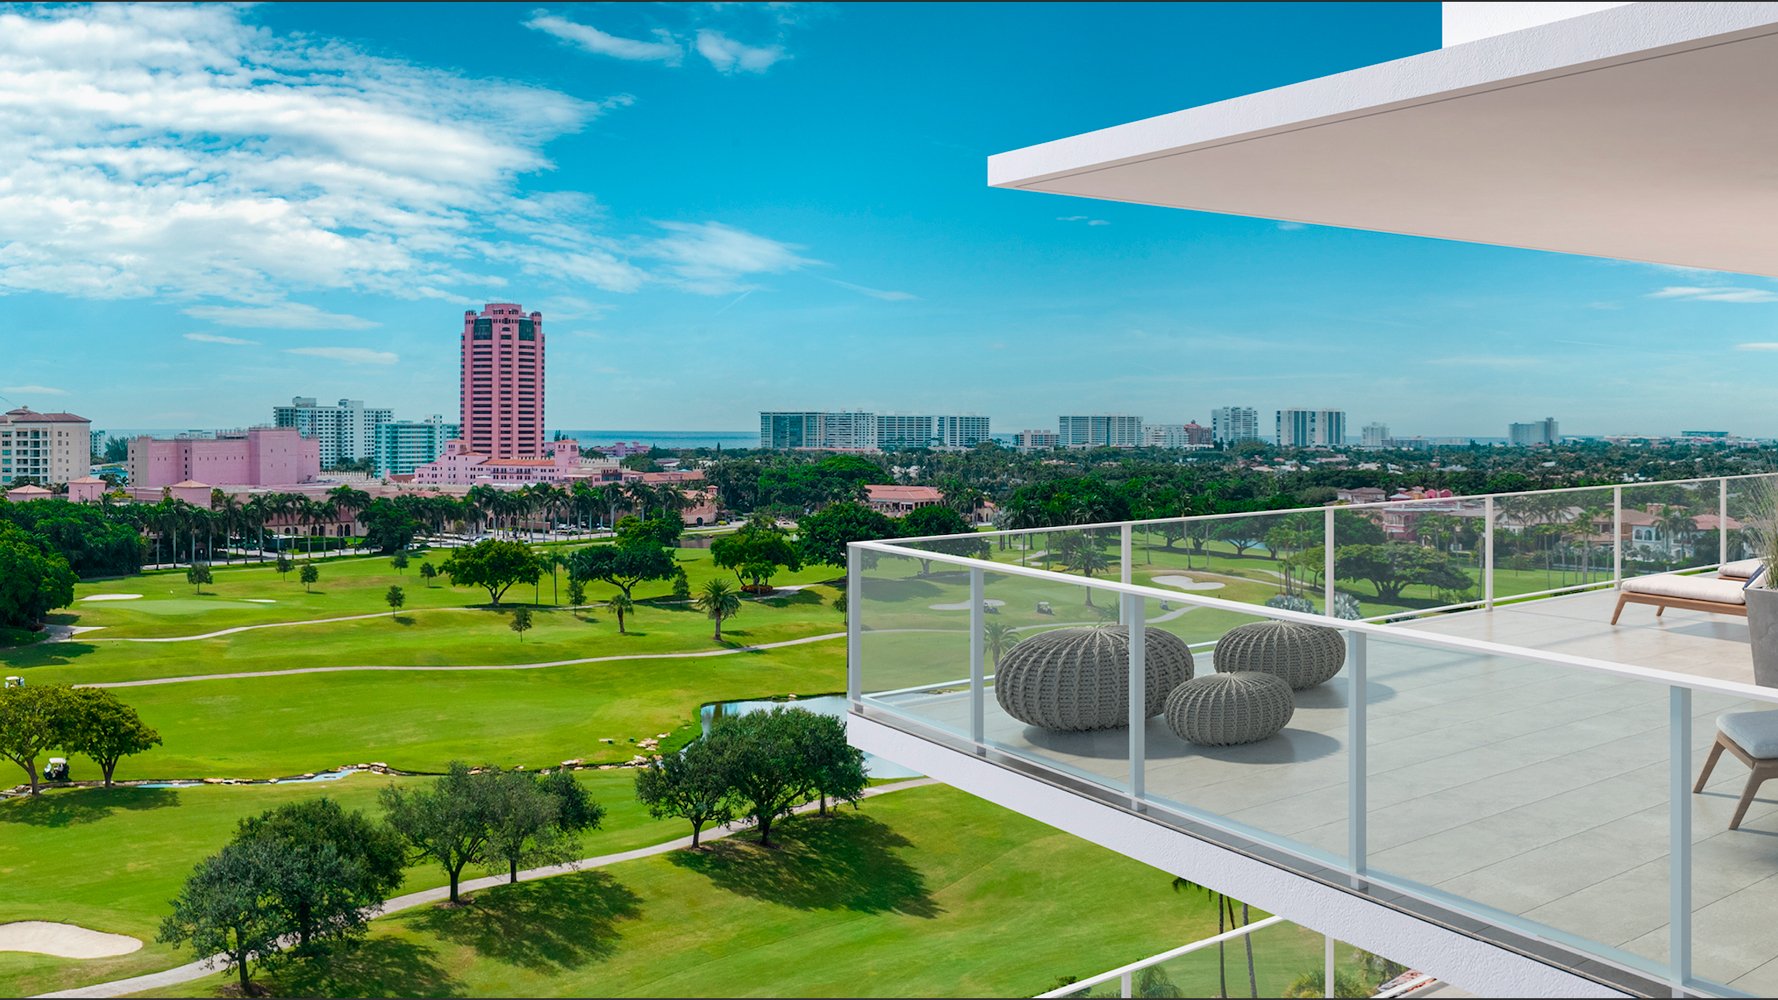
A Boca Raton residence can bring a different rhythm to a Los Angeles household: another place to gather, retreat, and spend extended time. Yet the most consequential decisions may concern neither the interiors nor the view. They concern who holds title, how the property fits into an existing estate plan, and what happens when its owner can no longer direct those arrangements.
For a buyer considering Alina Residences Boca Raton, a disciplined approach treats the acquisition as both a residential choice and an estate-coordination exercise. The purchase should serve the household's present needs without leaving future ownership unresolved.
The central distinction is simple: purchasing a Florida home is not the same as establishing a qualifying Florida permanent residence. That distinction should shape the tax assumptions before it shapes the paperwork.
Florida's property-tax homestead exemption generally requires permanent residence. A Boca Raton property used seasonally or solely as a second home ordinarily does not qualify. Budget without assuming either the exemption or the Save Our Homes assessment-growth benefit, which ordinarily does not apply to a vacation-only home.
If the property later becomes a qualifying permanent residence, timing matters. Homestead eligibility requires qualifying permanent residency as of January 1 of the tax year, and applications are generally due to the county property appraiser by March 1.
The first $25,000 of the exemption applies to all property taxes, including school district taxes. The additional exemption applies to non-school property taxes. Do not treat a familiar headline exemption amount as a fixed ceiling; the additional amount is subject to tax-year adjustments.
The practical lesson is to distinguish today's intended use from a possible future relocation. Second-home planning should not borrow assumptions from a permanent-residence scenario simply because both involve the same address.
An existing California estate plan deserves review before the Florida acquisition is incorporated into it. Ask counsel to identify the intended owner, the intended beneficiaries, and the documents needed to connect those decisions. The objective is consistency between the estate plan and the actual ownership instrument.
Florida real estate does not, by itself, eliminate California trust-tax considerations. California-resident trustees and noncontingent beneficiaries can be relevant to estate-and-trust filing obligations. Moving an asset to another state does not fully resolve the tax treatment of the trust holding it.
For buyers evaluating Glass House Boca Raton, this conversation belongs alongside the acquisition review, not after it. Ask the California tax adviser and Florida estate counsel to reconcile their recommendations before final vesting instructions are approved. Neither the property's appeal nor its Florida location determines the appropriate ownership structure.
Deed vesting should reflect the ownership arrangement the household has chosen. Rather than defaulting to whichever name appears on an early purchase document, ask counsel to explain how the proposed title supports the intended succession outcome.
A revocable living trust can allow Florida real estate to pass outside probate when the property is properly transferred into the trust. The essential step is the transfer: a trust document alone is not proof that this particular property is held within it.
Request a clear closing review that compares the proposed deed with the trust plan. After closing, retain the recorded ownership instrument with the relevant estate documents. If homestead eligibility later becomes relevant, Florida law requires the deed or qualifying ownership instrument to be recorded in the county's official records before the exemption may be granted.
Recording does not substitute for meeting permanent-residence requirements. It is one requirement, not a promise of eligibility.
Florida does not recognize a general transfer-on-death deed for real estate. Buyers should not assume that a succession mechanism familiar from another jurisdiction can simply be replicated for the Boca Raton property.
Commonly used probate-avoidance alternatives include a properly funded revocable trust and an enhanced life estate deed, often called a Lady Bird deed. The latter can preserve broad lifetime ownership powers while naming beneficiaries to receive the property at death.
These are options to evaluate with counsel, not interchangeable labels. Ask which instrument best reflects the household's intended control during life and transfer at death, and how it fits the existing estate documents. For a residence being considered at The Residences at Mandarin Oriental Boca Raton, the same principle applies: select the succession arrangement for the family, not for the residential branding.
Property-tax homestead eligibility, homestead succession, and creditor-protection rules are not interchangeable. An answer about one does not settle the others.
When Florida homestead is not validly devised and the decedent leaves a spouse and descendants, the succession rules generally give the spouse a life estate and the descendants the remainder. In those circumstances, the surviving spouse may elect an undivided one-half tenancy-in-common interest instead, with the remaining half passing to descendants.
These rules warrant specific legal review if the home becomes a Florida homestead. Ask counsel to test the intended inheritance against the applicable family circumstances rather than assuming a general beneficiary instruction resolves every issue.
Insurance deserves a parallel review, but it is not an estate-planning instrument. Ask the insurance adviser to review the proposed ownership arrangement and intended seasonal use, and to explain how the proposed policy would address them.
Keep the discussion property-specific. Request written explanations of coverage, exclusions, and unresolved questions before relying on a proposal. This is a review agenda, not an assurance that any particular coverage, premium, or eligibility outcome is available.
Likewise, ask estate counsel to review the documents intended to support decision-making if the owner cannot act. Keep that review connected to the deed and trust discussion, without assuming that insurance resolves questions of authority or inheritance.
Before closing, bring the proposed deed, relevant trust provisions, succession instructions, and insurance questions into one coordinated review. Preserve the final documents together and revisit the plan if the home's use or the household's intentions change.
A Los Angeles residence cannot generate Florida portability benefits. Portability concerns eligible transfers between qualifying Florida homesteads, allowing up to $500,000 of the Save Our Homes assessment difference to move. It transfers that difference, not the exemption itself; a new homestead application is required, generally with Form DR-501T and a March 1 deadline.
The enduring objective is coherence: a home selected for enjoyment, owned as intended, and integrated into the family's longer-term plans.
Explore Boca Raton residences with MILLION as you align your next home with your ownership and succession priorities.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationA home used only seasonally or as a second home ordinarily does not qualify. Florida's property-tax homestead exemption generally requires permanent residence.
Qualifying permanent residency must exist as of January 1 of the tax year. Homestead applications are generally due by March 1.
No. Save Our Homes limits assessment growth on qualifying homesteads and ordinarily does not apply to a vacation-only second home.
No. Florida portability concerns the assessment difference transferred between a previous qualifying Florida homestead and a new qualifying Florida homestead.
Eligible owners may transfer up to $500,000 of their Save Our Homes assessment difference. They must apply for a new homestead exemption, generally submitting Form DR-501T alongside it.
Yes, a revocable living trust can provide that route when the property is properly transferred into the trust. Having a trust document alone does not establish that the property has been transferred.
No. Commonly used probate-avoidance alternatives include revocable trusts and enhanced life estate deeds, which should be evaluated with counsel.
An enhanced life estate deed, commonly called a Lady Bird deed, can preserve broad lifetime ownership powers while naming beneficiaries to receive the property at death.
Yes. California-resident trustees and noncontingent beneficiaries can remain relevant to estate-and-trust filing obligations.
If the decedent leaves a spouse and descendants, the spouse generally receives a life estate and the descendants the remainder. The spouse may instead elect an undivided one-half tenancy-in-common interest, with the remaining half passing to descendants.