A discreet operating plan for a Houston household establishing a South Beach second home, from staff continuity and 2026 payroll obligations to building access, utilities, and vendor approvals.
For a Houston household establishing a second home in South Beach, the most consequential move may be the operating routine, not the furniture. Familiar service depends on clear responsibilities: who travels with the family, who maintains Houston, and who prepares the Florida residence between visits.
Treat the transition as three connected assignments: staffing, payroll, and residence-vendor onboarding. Appoint one coordinator-the household manager or the owner-to maintain the calendar and resolve questions before they become arrival-day interruptions. The objective is not to reproduce every Houston arrangement, but to preserve the standards that matter.
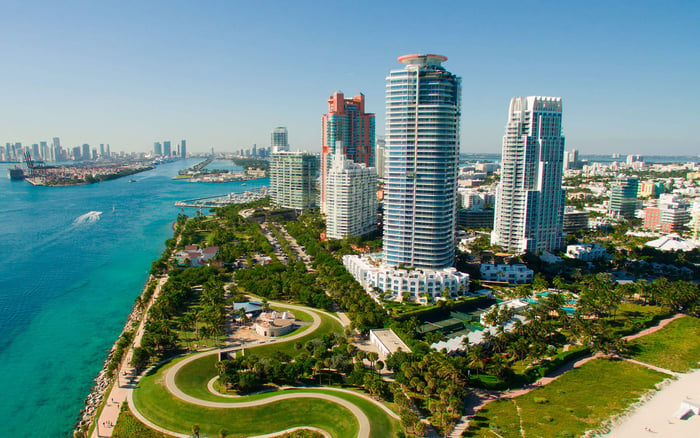
When considering Apogee South Beach, make operational due diligence part of the purchase conversation. Request the residence’s current access and service procedures rather than assuming an established household routine will transfer unchanged.
Begin with a role-by-role plan. Identify employees who will remain in Houston, those who may accompany the family, and duties better assigned locally. Separate occupied-home service from unoccupied-home oversight, with a designated person responsible for housekeeping, maintenance coordination, and pre-arrival preparation.
A written assignment summary provides operational clarity. Record duties, anticipated schedules, reporting lines, travel expectations, compensation, expense arrangements, and the process for requesting changes. This is a practical recommendation, not a statement that every Florida household must use a particular employment agreement.
For anyone dividing time between Houston and Florida, keep a clear record of work locations and hours. Have a qualified adviser review live-in arrangements, overtime, benefits, and state unemployment obligations before the schedule begins. Federal household-payroll thresholds alone do not resolve those questions.
Plan a handoff rather than relying on memory. A concise residence manual can document care preferences, approved purchasing authority, emergency contacts, and the distinction between routine tasks and work requiring owner approval. Keep sensitive employee information separate from the vendor-facing version.
The distinction between a household employee and an independent provider turns on the working relationship. A worker is generally an employee when the household controls both what work is performed and how it is performed. Someone who controls how services are delivered may be self-employed.
An invoice or business label does not settle the distinction. Review each arrangement on its own terms, particularly when a recurring provider begins taking detailed daily direction from the household.
Next, establish the employing party’s identity with the payroll adviser. Household employers subject to employment-tax reporting need an employer identification number. For an existing Houston employer, ask how the Florida work should be reflected in the current setup. Do not assume a second residence automatically requires a separate payroll structure.
Decide who approves hours, authorizes payments, and communicates changes. The household manager and payroll administrator should use the same approved compensation record.
In 2026, paying one household employee $3,000 or more in cash wages generally triggers Social Security and Medicare taxes on that employee’s applicable wages-not merely the amount above the threshold. Even a brief seasonal assignment can therefore require attention when the residence is used intermittently.
The employer generally contributes 7.65% of applicable wages: 6.2% for Social Security and 1.45% for Medicare. Employers ordinarily withhold the employee’s contributions, although they may elect to pay those contributions themselves. Clarify that choice before discussing take-home compensation.
Federal income-tax withholding is generally not required unless the employee requests it and the employer agrees, using Form W-4. Florida has no state personal income tax, but that does not remove federal household-employment obligations.
Federal unemployment tax has a different trigger. Combined household cash wages of $1,000 or more in any calendar quarter of the current or preceding year generally trigger FUTA obligations on each employee’s first $7,000 of applicable annual wages. Household employment taxes are generally reported on Schedule H with the employer’s federal income-tax return.
Florida’s 2026 minimum wage is $14 an hour through September 29, rising to $15 on September 30. Confirm coverage and exceptions before setting compensation. These figures are planning checkpoints, not a complete payroll checklist; state unemployment, overtime, and other individualized questions still require review.
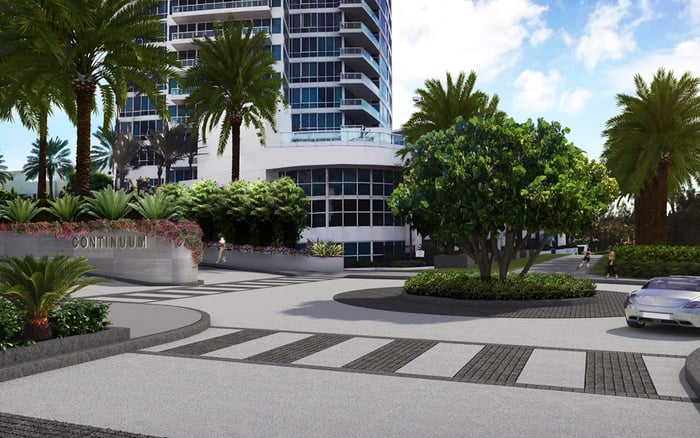
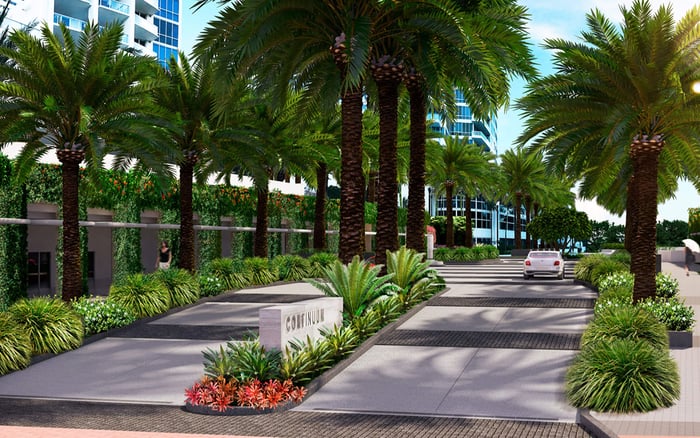
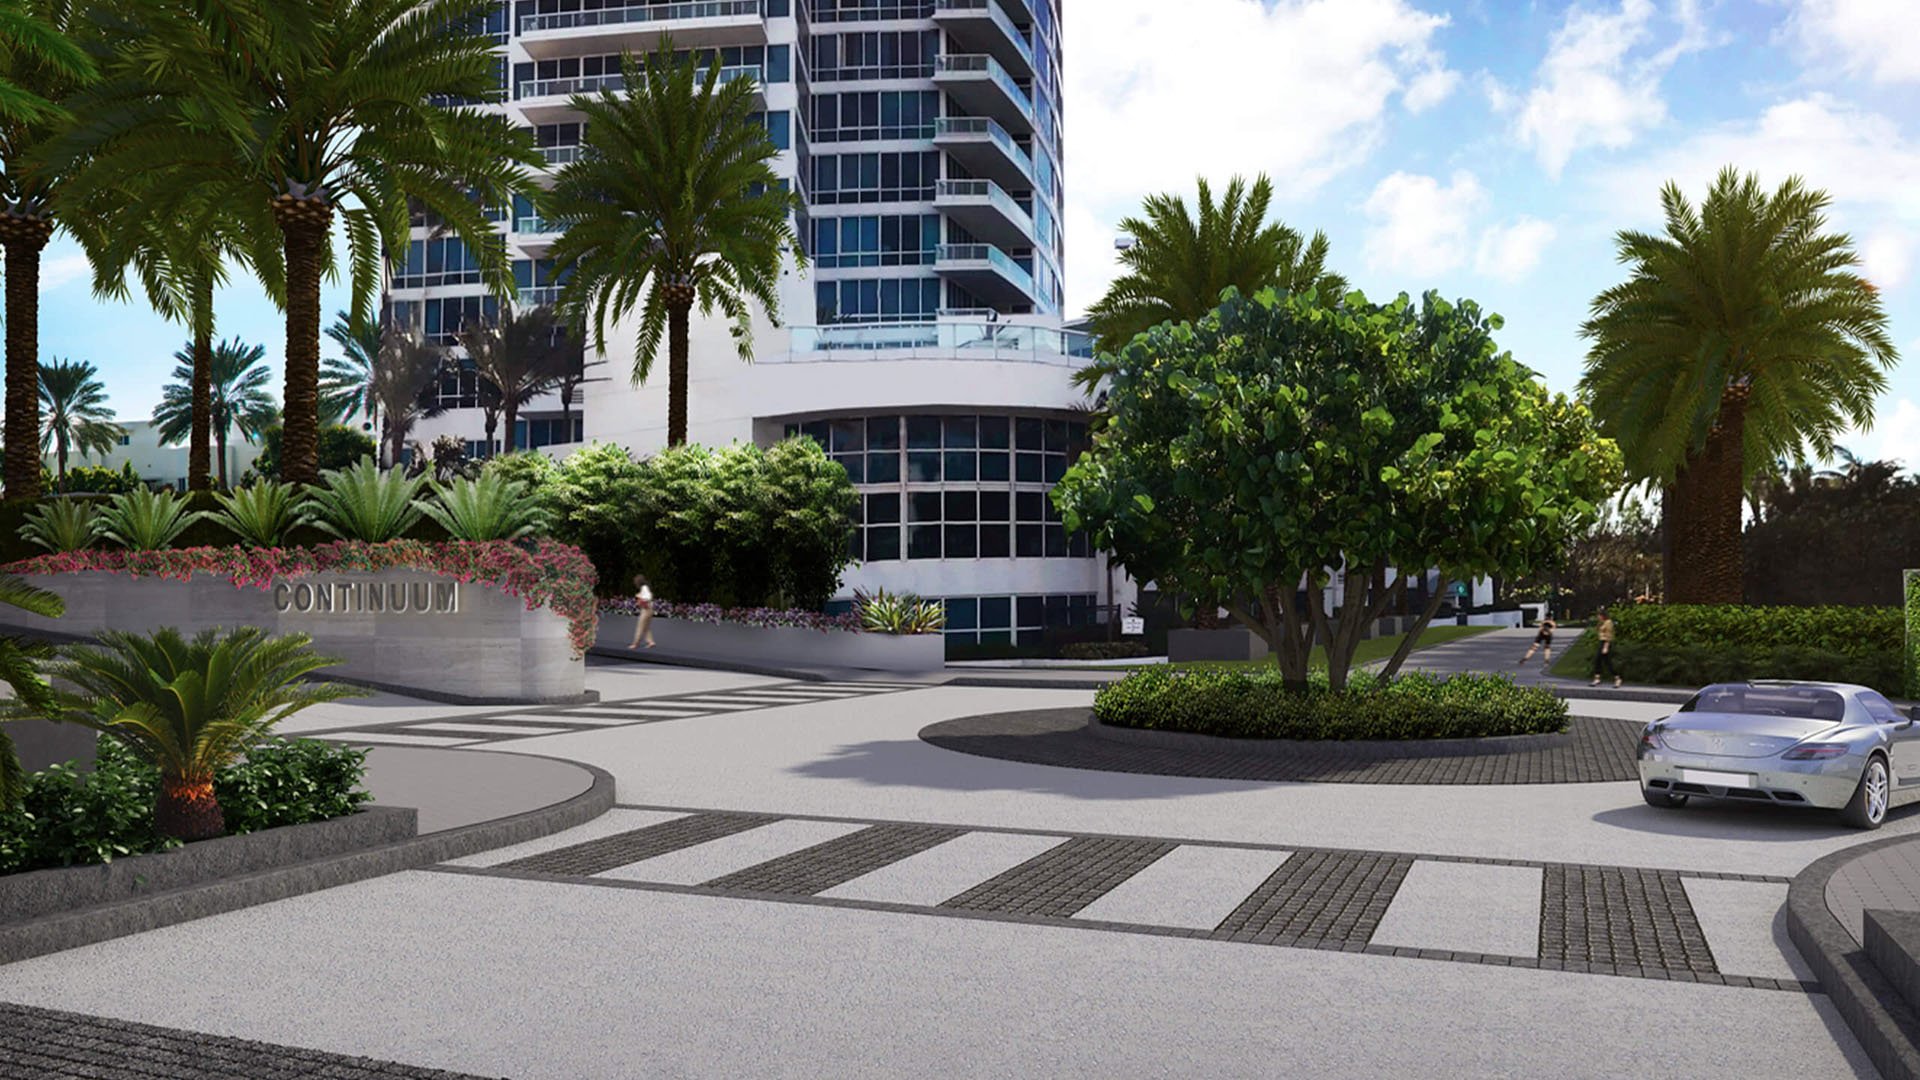
For a buyer evaluating Continuum on South Beach, the practical question is how a private household team would coordinate with building management. Obtain the current procedures directly rather than presuming any particular move-in, contractor, or staff-access policy.
Ask about service-elevator reservations, delivery windows, worker registration, contractor access, insurance documentation, and permitted work hours. Confirm which requirements apply to recurring household staff and which apply to outside contractors. These are due-diligence questions, not universal South Beach rules.
Create a vendor file documenting each provider’s scope, principal contact, agreed pricing, access arrangements, and approval status. Request insurance documentation where applicable and confirm the building’s requirements before committing to a start date.
Keep access authority narrower than spending authority. A provider admitted for an inspection should not automatically have permission to order replacements or expand the work. Record who can approve additional charges and how completion will be documented while the owner is in Houston.
First, determine which services the household must establish directly and which the building handles. Miami Beach’s Customer Service Center is a contact point for relevant municipal utility service; direct general questions to 305-673-7000 or [email protected].
For proposed residence work, consult the city’s project-specific permitting guidance before scheduling installation. Do not assume a checklist for single-family homes, duplexes, or qualifying townhouses applies unchanged to a condominium unit. Air-conditioning and generator projects have dedicated planning resources, but those resources do not establish approval for a particular residence.
Direct building-permit questions to 305-673-7610. The city also supports electronic permitting submissions. Keep municipal requirements and building permissions as separate checkpoints.
Apply the same discipline to a purchase review at Five Park Miami Beach: establish the proposed work scope first, then confirm the applicable approvals. A vendor’s availability is not permission to proceed.
Before the first owner stay, conduct a readiness review with the household coordinator. Confirm the staffing calendar, payroll arrangements, active services, vendor contacts, access permissions, and outstanding work. Ask the local team to rehearse the arrival sequence and identify unresolved handoffs.
The standard is simple: everyone should know their responsibilities, what they may authorize, and whom to call when circumstances change. That clarity allows the residence to feel effortless without leaving its operation to chance.
Explore your South Beach second-home options with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationDecide role by role, distinguishing traveling staff, Houston coverage, and locally assigned duties. Document responsibilities and obtain individualized review for split-location schedules.
A worker is generally an employee when the household controls both what work is performed and how it is performed. An invoice or business label does not determine classification.
Paying one household employee $3,000 or more in cash wages during 2026 generally triggers these taxes on applicable wages, not just the amount above the threshold.
The employer generally contributes 7.65% of applicable wages, comprising 6.2% for Social Security and 1.45% for Medicare. Employers ordinarily withhold the employee’s contributions but may elect to pay them instead.
Generally not, unless the employee requests withholding and the employer agrees, using Form W-4. This is separate from Social Security and Medicare obligations.
Combined household cash wages of $1,000 or more in any calendar quarter of the current or preceding year generally trigger FUTA obligations. These apply to each employee’s first $7,000 of applicable annual wages.
They are generally reported on Schedule H with the employer’s federal income-tax return. Household employers subject to employment-tax reporting also need an employer identification number.
The schedule lists $14 an hour through September 29, 2026, increasing to $15 on September 30. Confirm coverage and exceptions before setting staff compensation.
Ask management about access, worker registration, service-elevator reservations, delivery windows, insurance documentation, and work hours. Requirements must be confirmed for the particular building.
Do not assume it applies unchanged to a condominium unit. Confirm project-specific municipal requirements and building permissions before scheduling work.