A second-home buyer’s framework for reviewing Oceana Key Biscayne assessment exposure, reconciling payment schedules, and negotiating seller payoffs, credits, or escrow holdbacks before closing.
For a second-home buyer, the most valuable luxury is predictability: knowing what ownership requires whether the residence is occupied or not. At Oceana Key Biscayne, assessment review deserves the same attention as the residence itself. The question is not simply whether an assessment exists, but which costs attach to the unit, when they become payable, and how the purchase agreement allocates them.
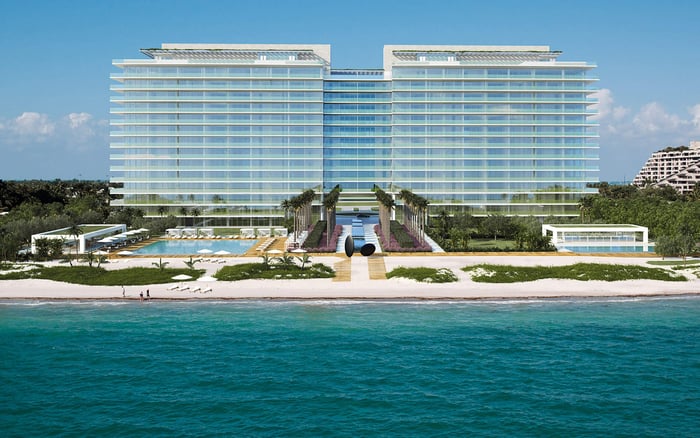
The property at 360 Ocean Drive, Key Biscayne, includes tower and villa residences. That distinction raises a practical question: do those components participate in every project cost on the same basis? The answer lies in the governing documents and assessment terms, not in assumptions about the development as a whole.
Historical language stating “no special assessments through 2025” does not confirm current 2026 status. Before committing, obtain current association documentation that distinguishes approved charges from work still under discussion.
Request the current budget, reserve information, special-assessment notices, and available inspection and structural-integrity reserve-study materials. Florida milestone-inspection and structural-integrity reserve-study requirements concern qualifying condominium buildings of three or more stories. Verify which requirements apply and review the relevant records without assuming a particular compliance outcome.
For any existing assessment, request a written schedule showing the original amount, installments already paid, remaining balance, and each payment date. Match that schedule to the target residence. A building-wide project budget is not, by itself, a unit payoff figure.
The association estoppel certificate should identify the date through which regular dues are paid, the amount and due date of the next installment, and assessments, fees, or other charges levied against the unit. Reconcile it with the seller’s disclosures and payment schedule. A verbal assurance that everything is paid does not resolve a documentary discrepancy.
Keep three categories separate: approved assessments, unpaid installments of those assessments, and disclosed work that might generate a future assessment. Each presents a different negotiation problem. An estoppel is an important closing safeguard, but it should not replace contractual treatment of work that has not yet become a charge.
Assessment exposure is tied to each unit’s share of the common elements, rather than interior square footage alone. Two-bedroom Unit 205N has a 0.403000% share; four-bedroom Unit 301N has a 0.836500% share. These are unit-specific reference points, not interchangeable estimates.
The preliminary calculation is straightforward: multiply the total assessment by the ownership percentage expressed as a decimal. Those percentages convert to 0.00403000 and 0.00836500, respectively. The declaration’s allocation rules and the particular assessment’s terms, however, govern whether that calculation applies to the cost under review.
Before using a figure in negotiations, confirm the target unit’s recorded allocation and whether the assessed work is shared across the relevant components. Then distinguish total allocated exposure from the unpaid balance. A seller credit should neither reimburse installments already paid nor overlook installments that remain due after closing.
Seller payment in full at or before closing is one structure for an unpaid assessment. Support it with association payoff information or written confirmation, and specify the obligation in the contract. Do not treat payoff as an automatic Oceana policy or assume the seller’s intention is sufficient.
A negotiated seller credit is an alternative when the buyer accepts responsibility for the remaining payments. The agreement should identify the assessment, credit amount, payment schedule, and how the credit will be applied at closing. Tie the amount to documented figures or an agreed allocation formula, not a rounded estimate.
A credit and a payoff may appear economically similar, but they operate differently. With a credit, the buyer must still track installments and fund payments when due. Review the proposed structure with the lender and closing agent, because financing restrictions may affect which credits or arrangements are acceptable.
Neither structure should leave responsibility for post-closing installments implicit. Florida buyers can face liability for unpaid condominium assessments associated with the unit, making clear allocation language and current estoppel information particularly important.
An escrow holdback can be negotiated when a pending assessment or disclosed project does not yet have an established final cost. Rather than treating an estimate as settled, the parties can reserve funds under agreed release conditions. This is a contractual solution, not an automatic entitlement.
The agreement should identify the holdback amount, covered project, release deadline, evidence required for disbursement, recipient of unused funds, and responsibility for any shortfall. Counsel should also address what happens if the deadline arrives before the project cost is established. A date alone does not resolve the underlying uncertainty.
The agreement should expressly cover disclosed work that results in an assessment only after closing. Otherwise, a buyer may negotiate protection against existing charges while leaving the most consequential future obligation unallocated. Clear language matters more than a broad promise that the seller will “take care of it.”
A buyer also considering Oceana Bal Harbour should apply the same document-first discipline without carrying over assumptions about assessment status, ownership percentages, or payment responsibility. Similar branding does not establish identical financial obligations.
For a broader search that includes Park Grove Coconut Grove, keep a separate assessment worksheet for each candidate residence. Compare documented unit exposure, payment timing, and negotiated protections-not merely the headline purchase price. These are diligence comparisons, not conclusions about either alternative’s current finances.
Before closing, designate who will receive association notices, monitor relevant board decisions, and track installment and escrow-release deadlines while the buyer is away. An adviser can help organize that calendar, but the arrangement should assign responsibility explicitly rather than assume someone else is watching.
The final review should connect four things: the association’s current records, the residence’s allocation, the seller’s contractual obligations, and the closing statement. Resolve inconsistencies before funds move. The objective is not to eliminate every future building expense, but to understand known exposure and allocate uncertainty deliberately.
For a discreet perspective on your next South Florida residence, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationOceana Key Biscayne is at 360 Ocean Drive, Key Biscayne, and includes tower and villa residences. Buyers should verify how costs are allocated across those components.
No. Language stating no special assessments through 2025 does not establish current 2026 status; obtain current association documentation.
Multiply the total assessment by the unit’s recorded ownership percentage expressed as a decimal, subject to the declaration’s allocation rules and the assessment terms.
No. The 0.403000% share identified for Unit 205N and 0.836500% share identified for Unit 301N are unit-specific and should not replace verification of the target residence’s recorded allocation.
Request the original amount, installments already paid, remaining balance, and payment due dates. Reconcile those figures with the seller’s disclosures and association estoppel.
It should identify the date through which regular dues are paid, the next installment’s amount and due date, and assessments, fees, or other charges levied against the unit.
Seller payment in full at or before closing is a negotiable structure supported by association payoff information or written confirmation. It is not an automatic Oceana-specific requirement.
It should identify the assessment, credit amount, installment schedule, and application of the credit. Clear the arrangement with the lender and closing agent before relying on it.
A negotiated holdback can address a pending assessment or project whose final cost is not established. Its terms should define the covered work, release conditions, deadline, unused funds, and shortfall responsibility.
The purchase agreement should expressly allocate that responsibility rather than assume the seller remains liable. Buyers should have transaction counsel review the language and coordinate monitoring of future notices.