For yacht owners planning a South Florida residence, ownership structure deserves the same attention as the address. A discreet briefing on homestead-tax eligibility, public records, and coordinating residence, marina, insurance, and financing decisions.
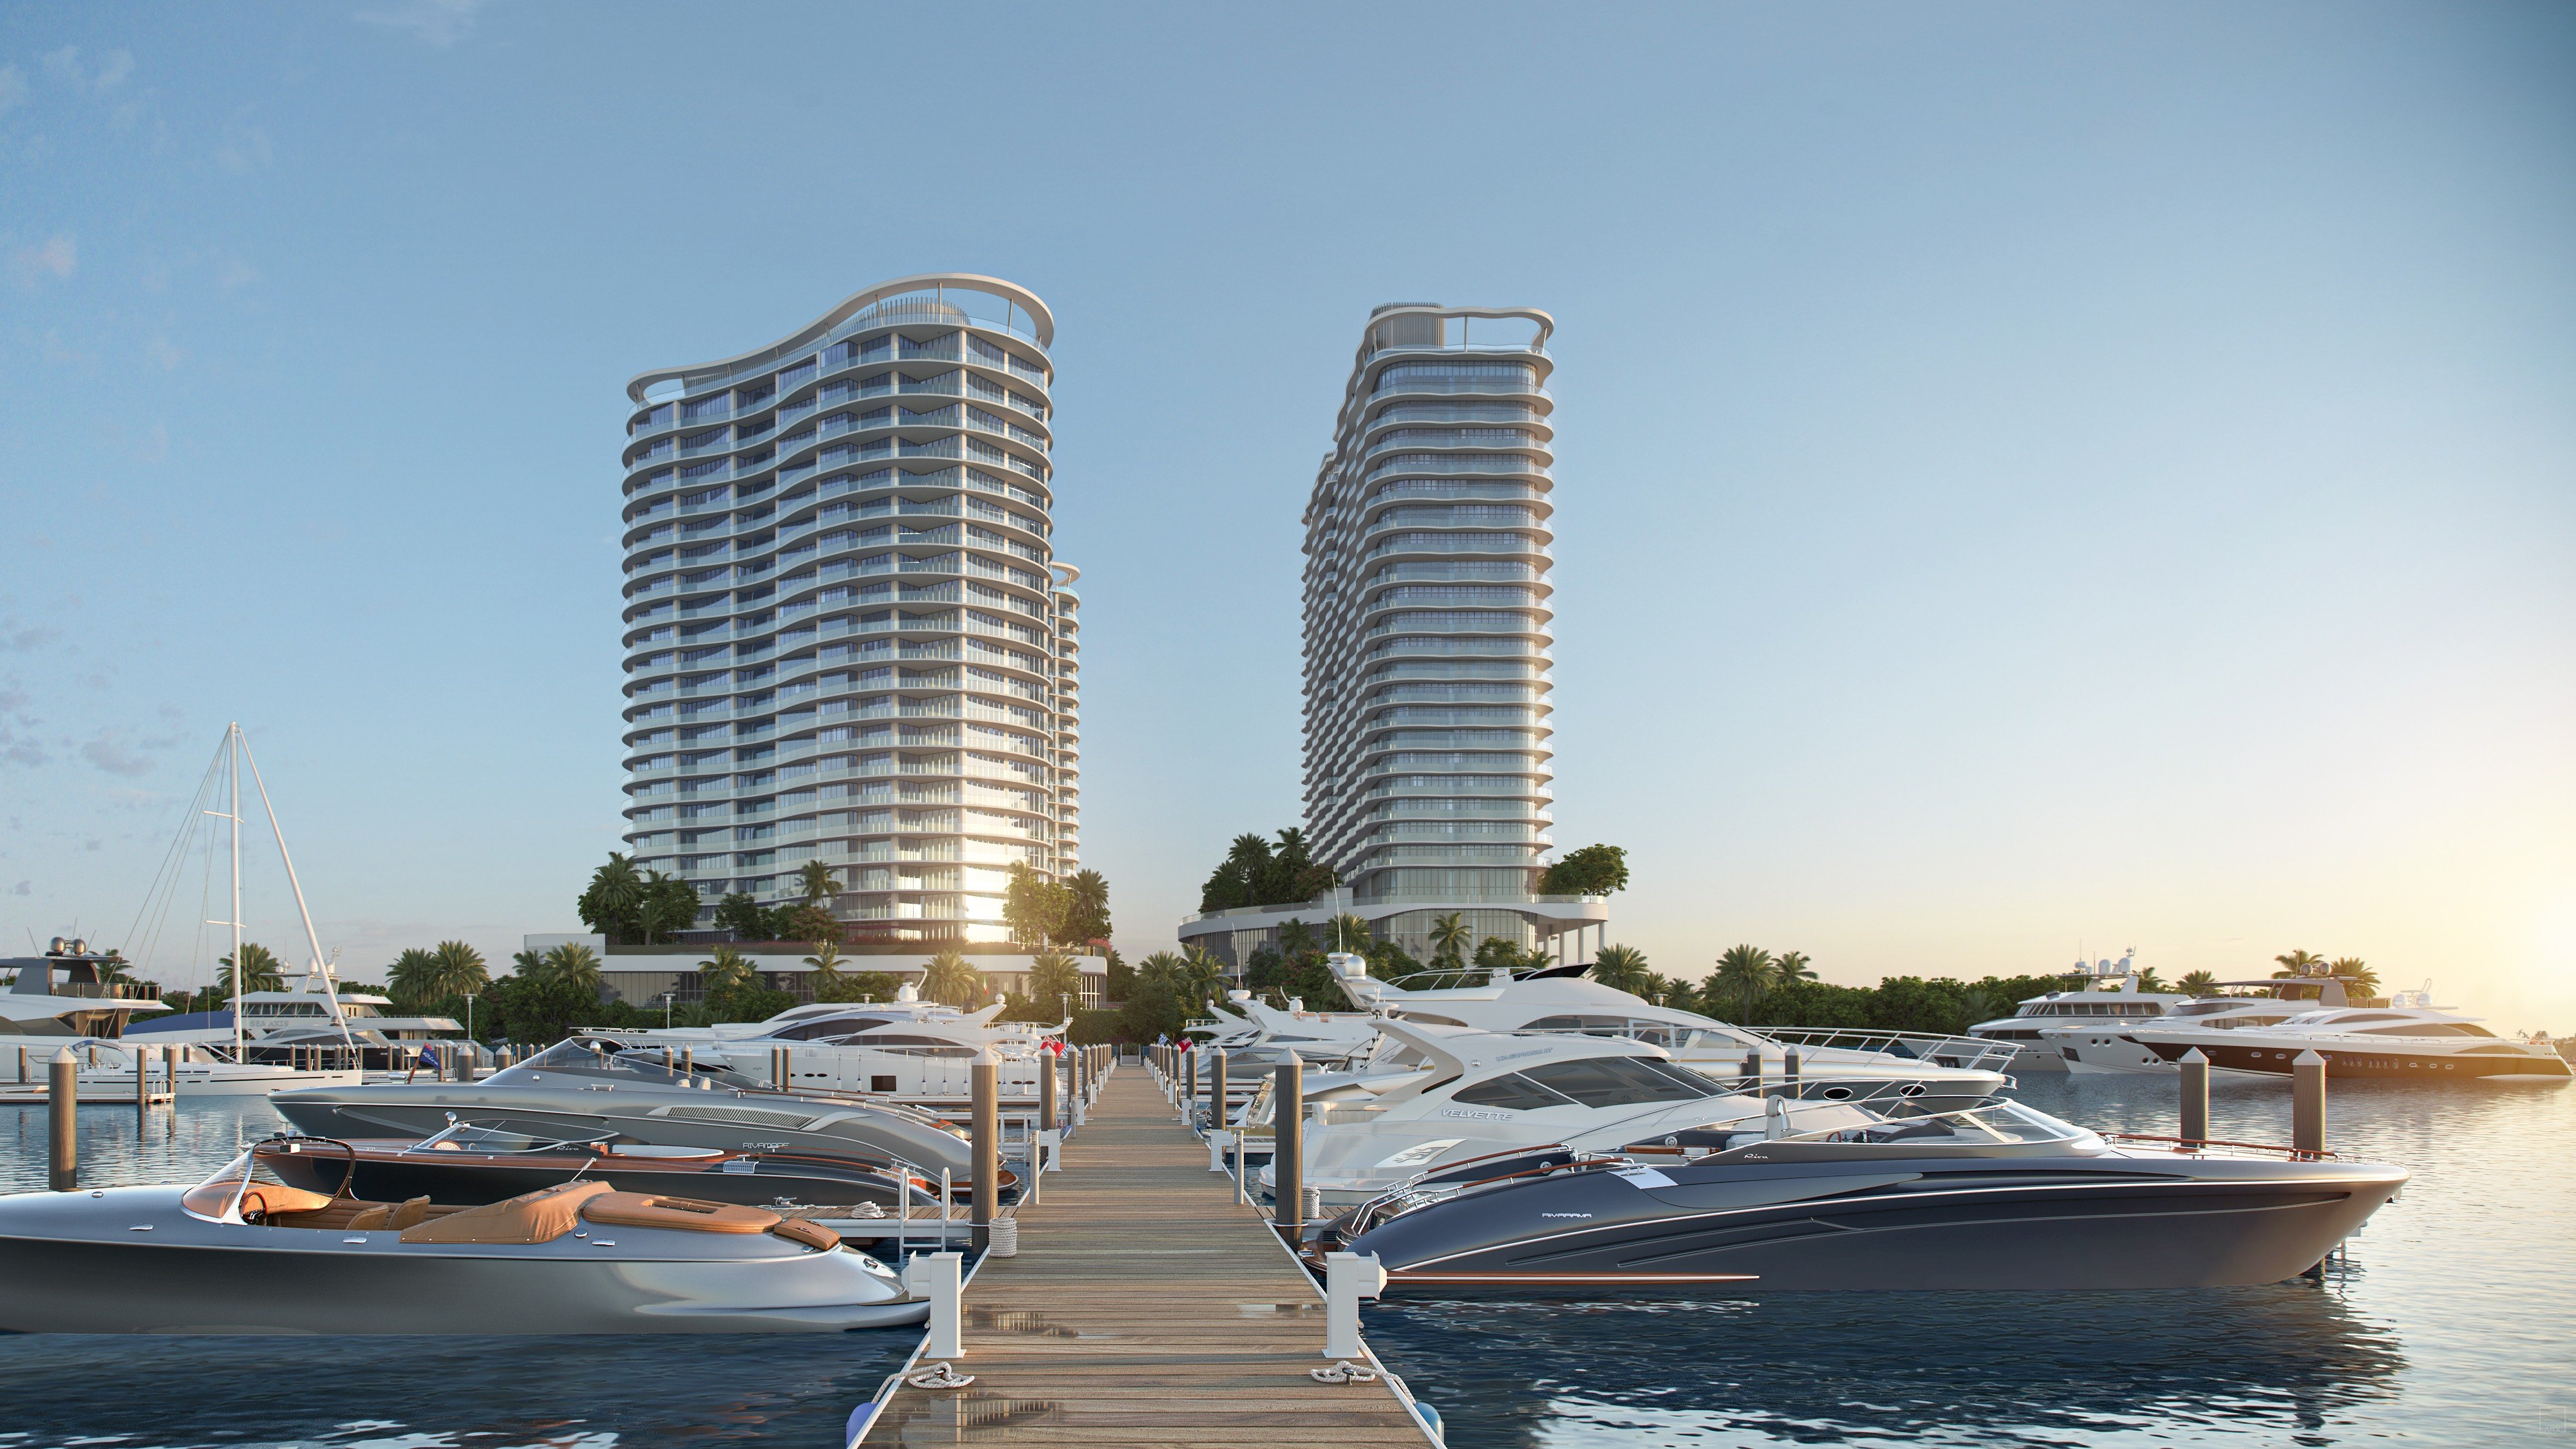
For a yacht owner assembling a South Florida home base, the residence and berth may feel like a single lifestyle decision. Ownership and contracts deserve separate attention. A permanent home, a vessel, and a marina relationship should not share one structure simply because a single entity appears administratively elegant.
Start with a clear instruction to the advisory team: identify which property will serve as the permanent residence, whether homestead-tax benefits are a priority, and what privacy means in practical terms. Then test the proposed ownership arrangement against the actual residence, marina, insurance, and financing documents. Coordination means making the choices compatible-not assuming every document should carry the same name.
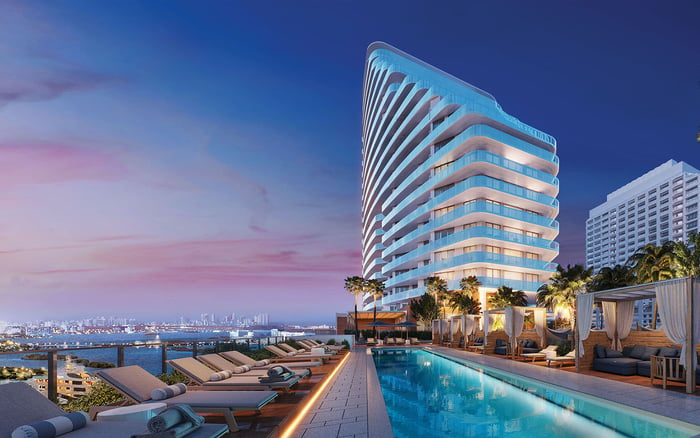
For a buyer considering Una Residences Brickell, this review belongs alongside the residential comparison, before the ownership vehicle is settled. The address is a lifestyle choice; the title decision requires its own analysis.
Florida homestead-tax eligibility generally requires legal or beneficial title and use of the property as a permanent residence as of January 1. A property may also qualify when it is the permanent residence of someone legally or naturally dependent on the owner. Address these conditions before finalizing the closing calendar and ownership documents.
Occupancy alone does not establish the exemption. Owners must apply through the county property appraiser’s office, and the deed or other ownership instrument must be recorded in county official records before the exemption is granted. Ask counsel to map the intended ownership, residential use, recording, and application steps together.
Beneficial-title eligibility is not blanket approval for every trust arrangement. If a trust is contemplated, review the relevant documents and eligibility rather than drawing conclusions from the word “trust.” Throughout this briefing, homestead refers to property-tax treatment, not constitutional creditor protection, inheritance restrictions, or spousal rights. Those questions require separate advice.
An LLC should not be treated as a way to hold a permanent residence while automatically retaining homestead-tax benefits. Florida’s homestead-exemption framework does not include LLCs among eligible ownership entities. Personal use of an LLC-owned home does not resolve that ownership issue.
The distinction also matters after acquisition. Transferring a homesteaded property into an LLC can remove existing exemptions and assessment caps. Before executing a new deed, request a review of the potential property-tax consequences rather than treating the transfer as a housekeeping exercise. Ownership and property-use changes also belong on the ongoing compliance agenda.
A purchaser weighing Onda Bay Harbor can separate two questions: whether the residence suits the household, and whether the proposed title structure suits its tax objectives. Neither answer establishes the other. If entity ownership remains a priority, the decision should reflect the homestead trade-off rather than a presumed exception.
Review the proposed marina arrangement separately. Ask who would sign, what access or use the agreement actually grants, and whether its duration fits the residential plan. Have counsel identify any language addressing assignment, termination, ownership changes, or the relationship between the residence and berth. These are review questions, not presumed contract provisions.
For someone evaluating St. Regis® Residences Bahia Mar Fort Lauderdale, assess the residential purchase and any contemplated marina arrangement on their own written terms. Do not infer berth rights, vessel suitability, or a particular contracting structure from a project’s name or presentation.
Request a short comparison of proposed signatories, relevant dates, and unresolved permissions. If different people or entities are involved, have the team explain how the arrangements would work together. Resolve that question before relying on the berth as part of the household’s relocation plan.
Review insurance and financing against the proposed ownership structure rather than leaving assumptions to revisit after signing. Request a side-by-side review of the residence documents, any marina agreement, proposed policies, and financing papers. The purpose is to identify questions that require written answers from the relevant counterparties.
For insurance, ask whether the proposed owner, intended use, and marina arrangement have been accurately presented, and how the policy wording addresses them. For financing, ask whether the contemplated borrower and title holder are acceptable and whether any later ownership change would require further review. Do not assume a policy or lender will accommodate a structure merely because it is convenient for the buyer.
The goal is not uniform names at any cost. It is a documented understanding of each party’s role and each agreement’s scope. Neither coverage nor financing availability should be an unstated premise of a tax or privacy decision.
Entity ownership is not anonymity. Miami-Dade provides online property searching, and its official-record search accepts a person’s or company’s name. Holding title through an entity therefore does not make recorded property documents unsearchable. A privacy review should consider both property records and entity filings.
Florida LLC articles of organization must identify the principal office, mailing address, registered agent, and registered office. Annual reports must identify at least one person authorized to manage the company, including that person’s name, capacity, and address. These disclosure requirements are part of the ownership decision-not details to discover afterward.
Ask counsel to review the anticipated public-record footprint before filing. Distinguish a preference for less immediately recognizable ownership from a promise of secrecy. The requirement to record the ownership instrument before homestead exemption is granted also belongs in this discussion. A privacy strategy should accommodate applicable disclosure obligations, not presume they disappear behind an entity name.
For a household considering Alba West Palm Beach, the final briefing should extend beyond acquisition. Ownership or property-use changes should be reported to the local property appraiser, including relevant changes associated with sale, marriage, divorce, or death. A later restructuring warrants fresh review rather than automatic reuse of the original analysis.
Before signing, request a concise decision record: the chosen title arrangement, the homestead-tax objective, the expected public disclosures, and the insurance, financing, and marina questions still requiring resolution. Assign responsibility for each follow-up. A considered ownership plan is one the household can administer as circumstances change.
For a considered approach to your South Florida residential search, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationEligibility generally requires legal or beneficial title and use of the property as a permanent residence as of January 1. Owners must also apply through the county property appraiser’s office.
A property may qualify when it is the permanent residence of someone legally or naturally dependent on the owner, subject to the applicable eligibility conditions.
Yes. The deed or other ownership instrument must be recorded in county official records before homestead exemption is granted.
Florida’s homestead-exemption framework does not include LLCs among eligible ownership entities. Personal occupancy should not be treated as a solution to that ownership issue.
Yes. Such a transfer can remove existing exemptions and assessment caps, so the property-tax consequences deserve review before a new deed is executed.
No. Beneficial-title eligibility does not automatically establish eligibility for every trust arrangement; the documents and circumstances require review.
No. Miami-Dade property and official-record searches provide public research channels, and recorded documents can be searched using a company’s name.
Articles identify the principal office, mailing address, registered agent, and registered office. Annual reports identify at least one person authorized to manage the company, including name, capacity, and address.
Review the actual documents against the proposed ownership arrangement and obtain answers to unresolved questions. Do not assume shared signatories, coverage, berth rights, or lender acceptance.
No. This briefing concerns homestead property-tax treatment, not constitutional creditor protection, inheritance restrictions, or spousal rights.