A seasonal home deserves a closing strategy that coordinates ownership, insurance, succession intentions, and signing authority without confusing their distinct legal roles.
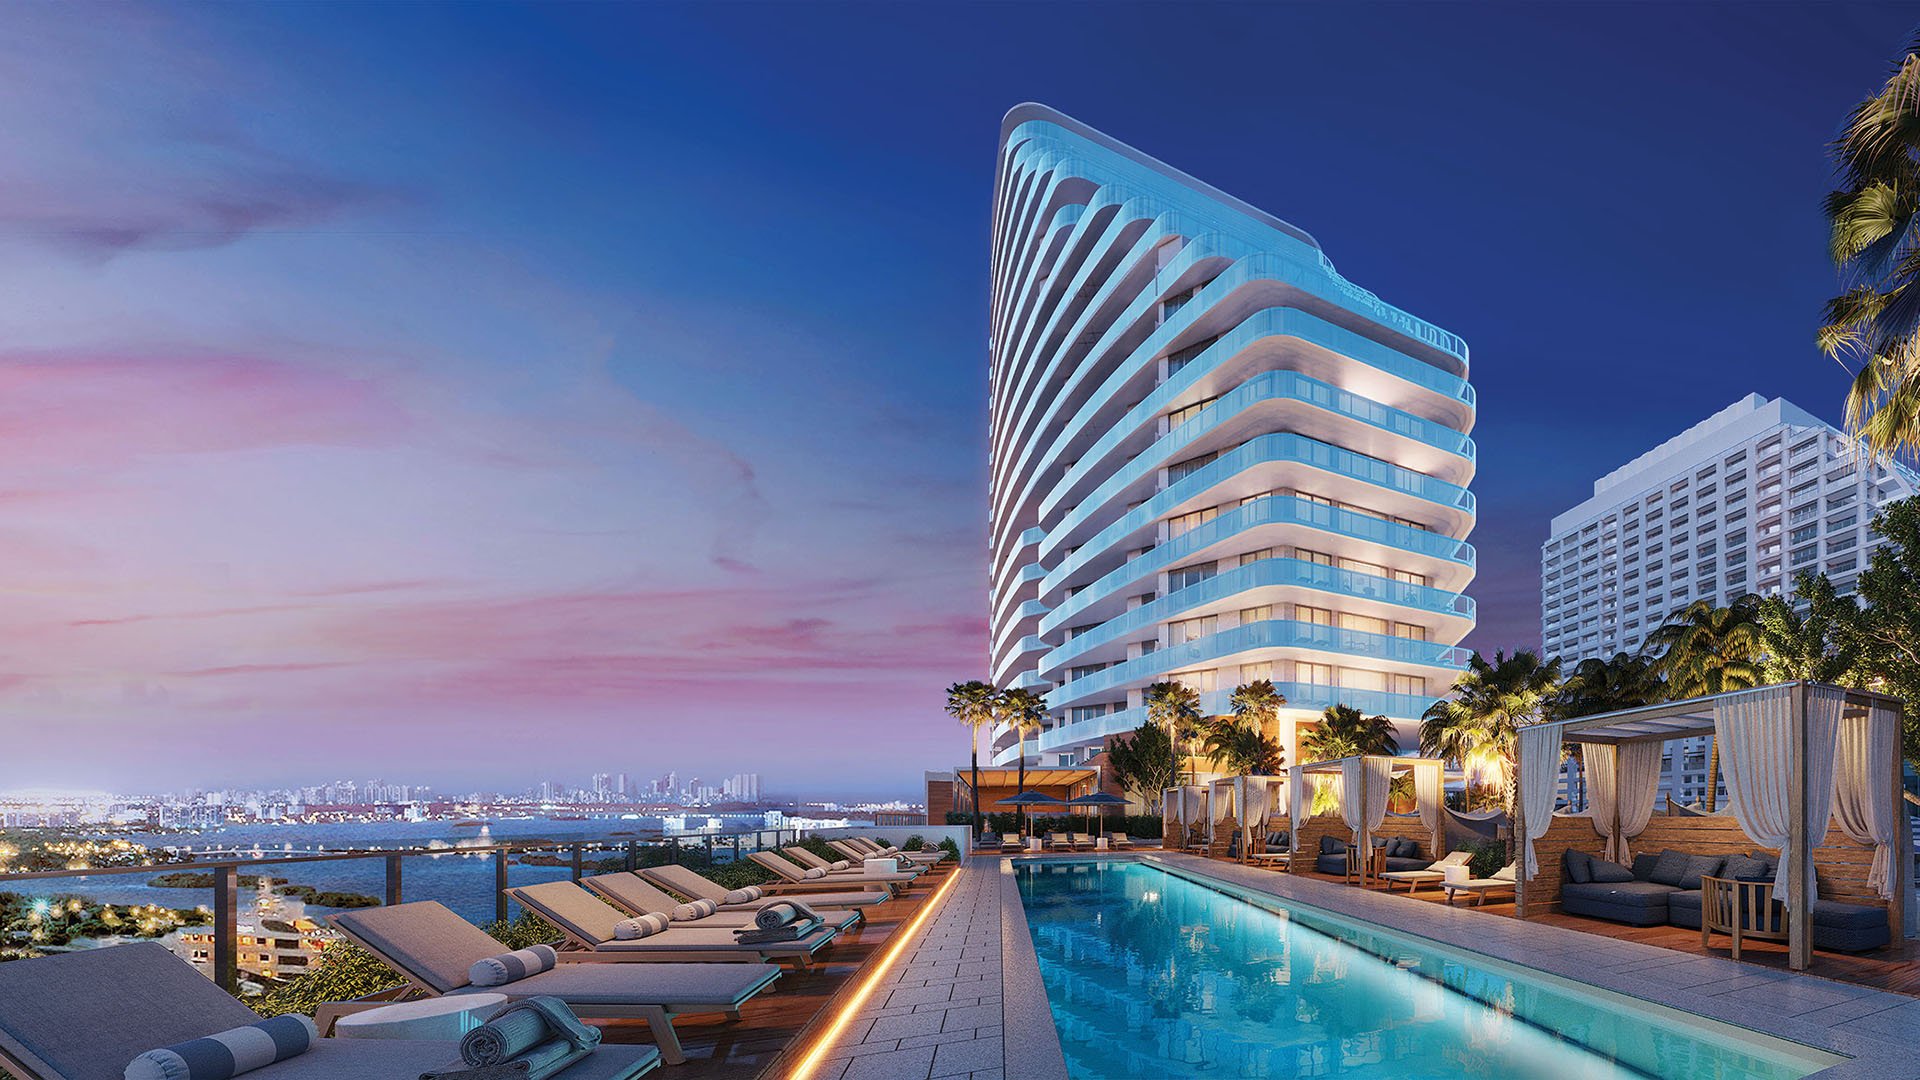
A South Florida residence may be chosen for its outlook, privacy, or place in a family's seasonal rhythm. Its closing deserves equally deliberate attention. Waterfront appeal is one decision; the legal relationship among owner, insured, beneficiary, and authorized signer is another. Those roles should work together, but they are not interchangeable.
For a seasonal purchaser considering The Residences at 1428 Brickell, the starting point is not simply who will attend closing. It is who should own the property, what should happen to that interest later, which interests the insurance policy covers, and who may execute the necessary documents.
Resolve those questions with Florida counsel, the closing team, and the insurance adviser before travel plans dictate the timetable. The objective is a coordinated file, not a last-minute collection of signatures.
Deed vesting establishes how ownership is held. Choosing it early matters because the ownership structure affects survivorship, future transfers, and whose signatures the closing team must obtain. Treating vesting as a clerical detail can leave important decisions unresolved while documents are being prepared.
Start with a written statement of intentions: who should hold the ownership interest now, whether survivorship is intended, and what future transfers the family anticipates. Counsel can then assess the appropriate structure. No single choice among individual, joint, or trust ownership is preferable for every seasonal household.
A Miami Beach buyer evaluating The Perigon Miami Beach should bring those intentions into the closing discussion before relying on a preferred signing arrangement. An agent's availability does not determine how title should be held.
Ask the closing team to review the proposed vesting and signature requirements together. If ownership instructions change, request a fresh review of the related documents rather than assuming the earlier signing plan still fits.
The insurance conversation should proceed alongside the ownership conversation. Property-insurance recovery depends on an insurable interest at the time of loss, so the relationship between actual ownership and the policy's insured interests matters.
That does not mean every policy must reproduce the deed's vesting language word for word. Instead, ask the insurance adviser to review the proposed ownership structure, identify the named insureds, and explain how the policy addresses the relevant interests. A familiar family name on a declaration page is not, by itself, a complete analysis.
For a seasonal acquisition at Four Seasons Hotel & Private Residences Fort Lauderdale, this means reviewing ownership and policy terms-not making assumptions about that property's insurance arrangements.
Keep the distinction clear: deed ownership identifies the property interest, while policy terms address insured interests and coverage. Neither beneficiary status nor signing authority substitutes for that review. Revisit the alignment when ownership circumstances change, rather than treating closing as the final checkpoint.
Florida permits a power of attorney, or POA, for real estate transactions, allowing an authorized agent to sign closing documents for an absent principal. For seasonal owners, this can be a practical way to separate the closing schedule from personal travel.
The document should expressly identify the relevant real estate powers rather than rely on broad, general authorization. Florida's general execution requirements include the principal's signature, two subscribing witnesses, and acknowledgment before a notary. Authority and execution formalities require separate checks: satisfying one does not satisfy the other.
Before relying on an existing POA, have counsel and the closing team review it against the contemplated documents and actions. Do not assume that a broadly worded family document resolves every closing issue.
Arrange the recording plan in advance as well. Recording a real-estate POA in the county's official records, often before or alongside the deed it supports, is a recommended closing practice. Confirm how the closing team intends to handle that step rather than assuming it happens automatically.
Permission to sign real estate documents is not permission to redesign succession outcomes. Under Florida's POA rules, creating or changing survivorship rights or beneficiary designations requires specifically enumerated authority separately signed or initialed by the principal.
This distinction matters when a proposed deed does more than carry out an ordinary transaction. General real estate authority alone may not authorize an agent to execute a lady bird deed that changes beneficiary or survivorship outcomes. Have counsel examine the instrument's effect, not merely its label.
Certain self-benefiting actions are also limited. Unless the POA otherwise provides, an agent who is not the principal's ancestor, spouse, or descendant cannot use the specified powers to create an interest for themselves or someone they owe a duty to support.
For a West Palm Beach purchaser considering Alba West Palm Beach, the practical lesson is to settle succession intentions before asking an agent to implement them. Signing convenience should follow those decisions, not determine them.
The phrase second home describes an owner's plans, but it is not a conclusive legal classification. Confirm actual homestead status with counsel before deciding which spousal-signature rules apply.
An agent conveying or mortgaging a married principal's homestead must obtain joinder by the principal's spouse or the spouse's guardian. A spouse who is not on title may nevertheless need to join a homestead deed, including when the titled spouse acquired the property before marriage.
These rules concern conveyances and mortgages. They do not impose a blanket requirement that every married buyer's spouse sign every purchase document.
Florida also permits qualifying deeds or mortgages involving married-person homestead or property held as an estate by the entirety to be executed through a POA executed with deed formalities. Qualifying authority may run from one spouse to the other, or from one or both spouses to a third party. The specific arrangement still warrants document-level review.
Before signing, request a final reconciliation of four items: deed vesting, insured interests, intended beneficiary or survivorship outcomes, and each signer's authority. Each answers a different question. Reviewing them together helps reveal inconsistencies without treating any one document as a substitute for the others.
Maintain that discipline after closing. An owner's death does not automatically terminate insurance coverage, but it can leave current ownership and the named insured misaligned, requiring policy review. Keep the ownership and insurance advisers connected when circumstances change.
These statewide principles provide a planning framework, not transaction-specific legal or coverage advice. The best closing strategy is one your advisers have checked against your actual ownership intentions and documents.
Explore South Florida residences with MILLION as you shape a considered second-home plan.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationOwnership structure affects survivorship, future transfers, and whose signatures the closing team must obtain. Early decisions allow the related documents to be reviewed together.
Florida permits an authorized agent to sign real estate closing documents through a power of attorney. The authority should expressly cover the relevant real estate actions.
They include the principal's signature, two subscribing witnesses, and acknowledgment before a notary. Counsel should review the document's authority as well as its execution.
Recording it in the county's official records, often before or alongside the deed it supports, is a recommended closing practice. Confirm the recording plan with the closing team.
The review should focus on ownership, named insureds, and the interests addressed under the policy rather than word-for-word matching. Ask the insurance adviser how the policy covers the proposed ownership structure.
Property-insurance recovery depends on an insurable interest at the time of loss. Coordinating ownership and insured interests therefore deserves attention before and after closing.
Creating or changing beneficiary designations or survivorship rights through a POA requires specifically enumerated authority separately signed or initialed by the principal. General real estate language alone may not suffice.
No blanket requirement follows from the homestead-joinder rules discussed here. Those rules concern conveyances and mortgages, and actual homestead status must be assessed.
No. Counsel should confirm actual homestead status rather than relying on the seasonal-use description.
An owner's death does not automatically terminate coverage. It can leave current ownership and the named insured misaligned, so the policy should be reviewed.