A discreet ownership checklist for The Surf Club, separating advertised residential services from emergency arrangements and addressing pets, household staff, valuable contents, and post-storm access.
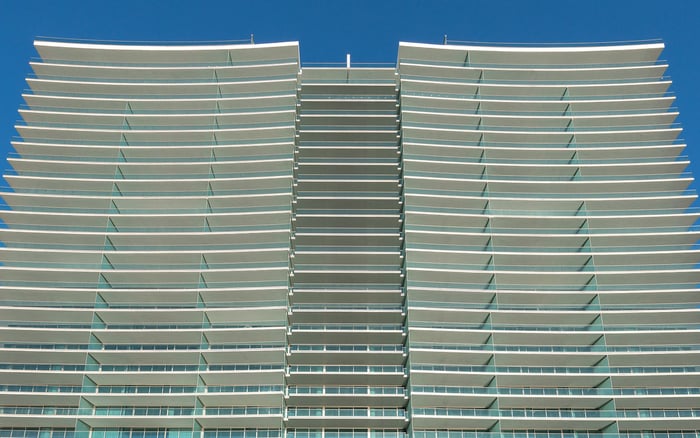
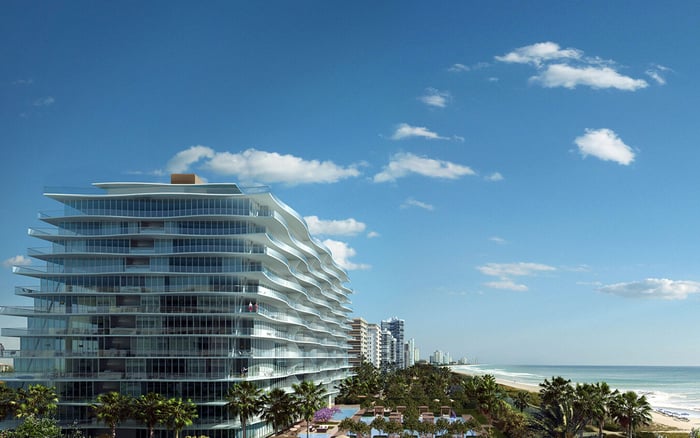
At The Surf Club Four Seasons Surfside, ownership includes expansive private terraces, floor-to-ceiling glass, and residences with Atlantic Ocean or Biscayne Bay views. At 9011 Collins Avenue, those pleasures warrant an equally considered emergency plan, particularly for households coordinating pets, employees, and valuable collections.
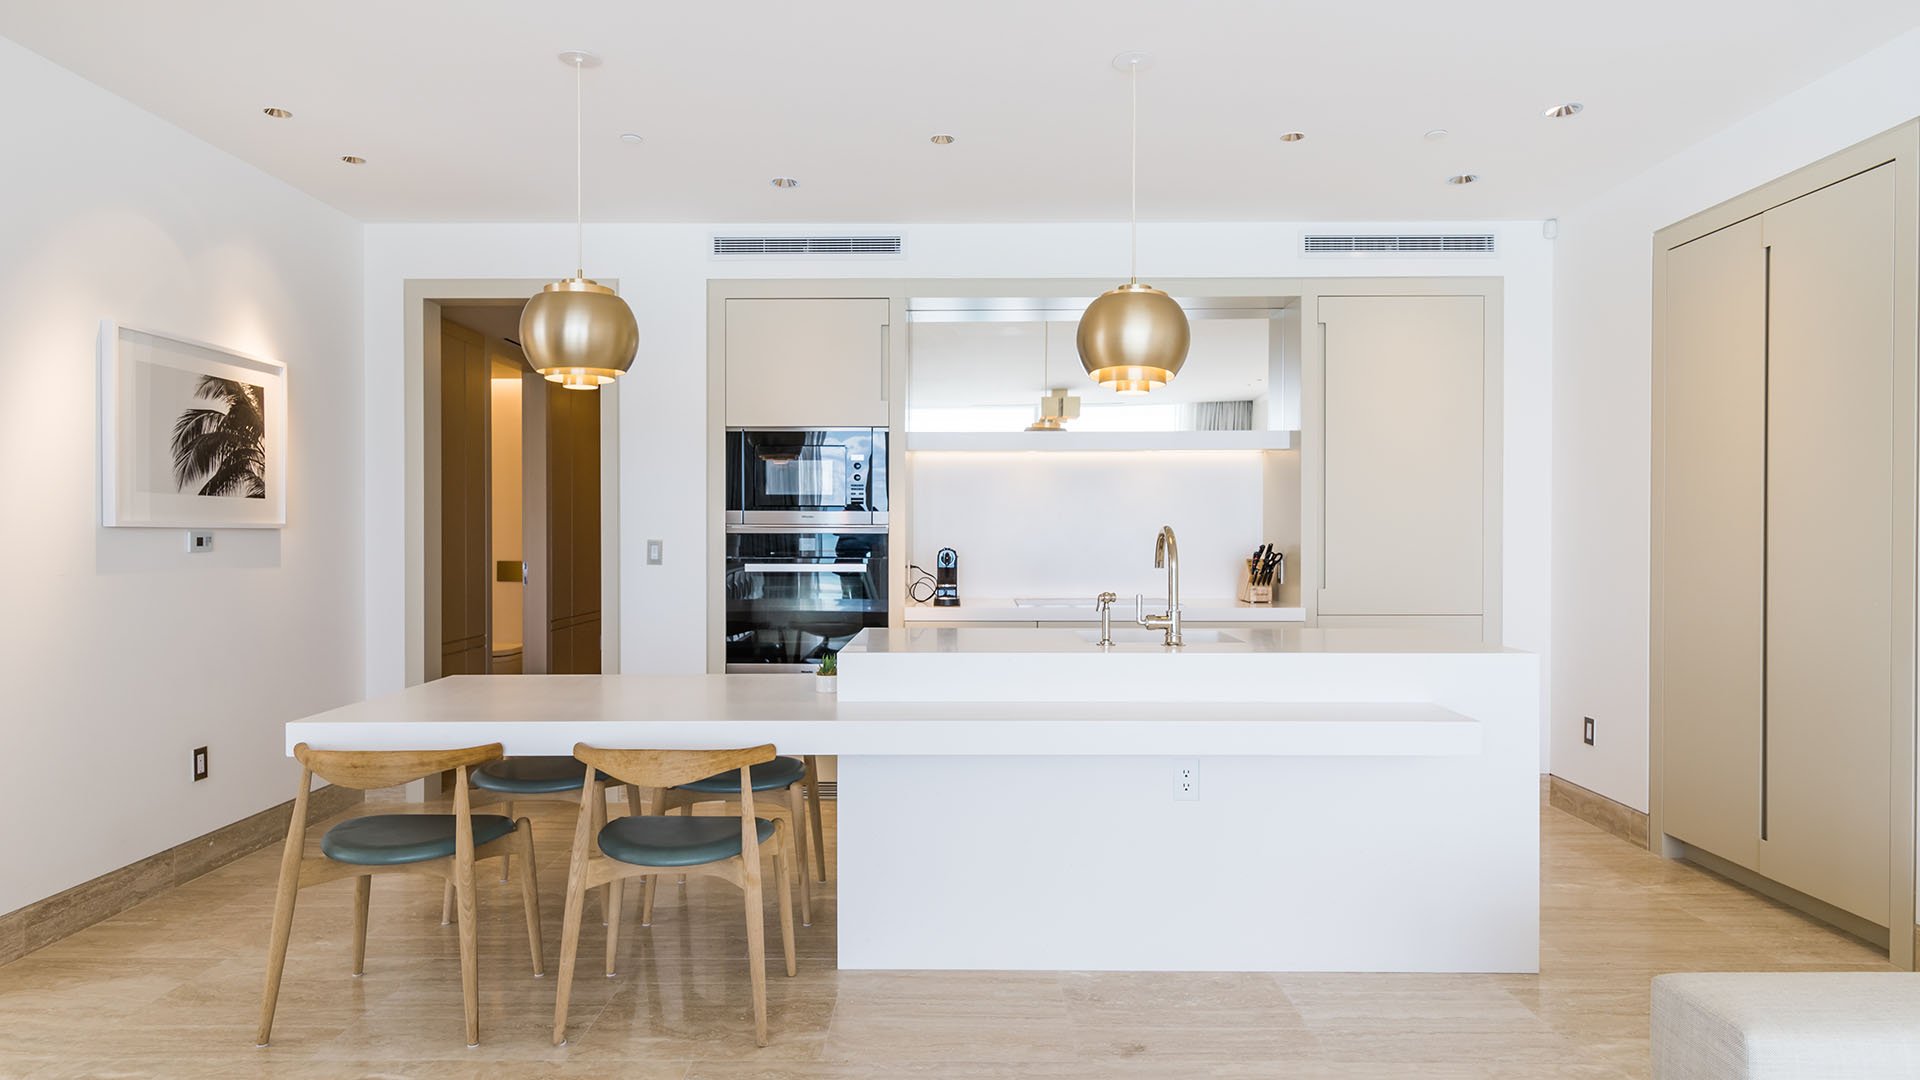
Advertised private-residence sizes range from approximately 1,800 to 7,800 square feet, with ceilings reaching up to 20 feet. For an owner, the question is not simply when to leave. It is who prepares each room, who accompanies each animal, and which possessions require advance decisions rather than last-minute handling.
An evacuation plan should make departure possible without relying on unconfirmed assistance. At a highly serviced address, everyday convenience and emergency obligations are not interchangeable. A buyer should resolve that distinction before closing; an existing owner should revisit it before each hurricane season.
Advertised services include doorman and bellman assistance, 24-hour on-call emergency repair, housekeeping, grocery provisioning, valet, and concierge support. Advertised security features include 24-hour security, patrols, and closed-circuit cameras. None of these, on its own, establishes a commitment to hurricane staffing, transportation, pet evacuation, or contents removal.
Request a written emergency brief from management. Ask when ordinary services may change, how residents receive instructions, and which tasks remain the owner's responsibility. Clarify whether assistance must be reserved, whether outside vendors require advance approval, and what happens when an owner is overseas.
Buyers also considering Fendi Château Residences Surfside should ask the same questions rather than infer emergency arrangements from an amenity package. This is a due-diligence comparison, not a claim that the properties share procedures.
The practical result should be a short responsibility schedule: each task, the person accepting it, a backup contact, and the point beyond which the task will no longer be attempted.
Build the household plan around current official evacuation instructions, not a preferred forecast threshold. Do not assume a lower-category storm rules out an evacuation order. Confirm the applicable instructions when a storm threatens and, where practical, set an earlier departure point for the household.
Work backward from a confirmed destination. Identify who travels together, which vehicle carries the animals, and how everyone communicates if separated. Discuss escape routes, utility loss, and animal safety before departure, not during it.
Ask management about departure access, vehicle retrieval, elevator procedures, and the deadline for any permitted preparation work. Treat each as a building-specific question, not an assumed service.
Keep essential documents, medications, contact details, and departure instructions accessible to those who need them. The plan should remain usable if the principal owner cannot answer a call. No art collection or apartment-preparation checklist should delay compliance with evacuation instructions.
Account for pets in both the evacuation plan and the household emergency kit. Designate a primary handler and a backup for every animal, including instructions for when the owner is away. Confirm that the destination accepts the animals before making it the primary option.
Plan to travel with crates or carriers, keep collars and identification tags on, and select a safe destination where owners and animals can remain together. Include one week of pet food and water, plus medications, as a preparedness provision rather than a building requirement.
A pet-friendly evacuation center is an option to investigate for households in an evacuation zone or unsafe structure. Check current operating and admission arrangements rather than assuming a particular center will be available.
For a household using a driver or pet-care professional, confirm availability, responsibility, and a backup arrangement in advance. Do not treat a concierge relationship as confirmation of pet transport. The written plan should specify who collects each carrier, who carries supplies, and who confirms that every animal has departed.
A house manager, caregiver, housekeeper, or driver needs a clear departure plan, not an open-ended instruction to protect the residence. Discuss transportation, communications, personal evacuation needs, and whether anyone will accompany the household. Agree on arrangements before the storm becomes an immediate concern.
For building personnel, ask management which roles, if any, continue during an emergency and when services may stop. Clarify authorized unit entry, any utility-shutoff procedures, and how urgent conditions inside an unoccupied residence would be communicated. These are questions to resolve, not verified commitments.
Document who may authorize entry, who holds the relevant contact information, and who can approve an expense if the owner is unreachable. Keep private household instructions separate from building procedures, then check that they do not conflict.
Finally, establish how employees and residents will confirm their departure. Nobody should be expected to remain behind solely to supervise possessions once evacuation is required.
Begin with an inventory and an insurance review. For artwork, jewelry, collectible furniture, and other valuable possessions, consider photographs, identifying details, purchase records, and current appraisals where appropriate. Retain an accessible copy away from the residence.
Divide contents into practical groups: essentials that travel with the household, objects that may require specialist relocation, and items intended to remain. This is an owner's planning exercise, not a description of the building's removal procedures.
If considering specialist handling, discuss timing, packing, transport, storage, access approval, and cancellation conditions in advance. Ask insurance advisers how the actual policy treats items at home, in transit, and in temporary storage, including relevant limits, exclusions, deductibles, and documentation requirements. Do not assume coverage follows an object unchanged.
An owner comparing Arte Surfside can apply the same contents review without assuming either property's staff will move or safeguard a collection. Obtain written confirmation of any agreed assistance.
Terraces warrant a separate conversation with management. Ask what preparation is required, who may perform it, and when access or work must stop. Avoid improvising handling methods for large furnishings or delicate objects as departure approaches.
For an intermittently occupied residence, name a local representative and a backup, subject to management's authorization requirements. Ask how damage notifications, inspections, vendor entry, and post-storm access would be handled. Do not assume departure authorization also permits immediate re-entry.
Before returning, confirm official access instructions and the building's readiness to receive residents. Establish who will document conditions and contact the insurer if necessary, without making unconfirmed promises about repair availability.
The ownership standard is straightforward: protect people and animals first, assign preparation tasks explicitly, and treat every unconfirmed service as a question to settle rather than a promise.
For a considered perspective on South Florida residential ownership, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationThe Surf Club is at 9011 Collins Avenue, Surfside, Florida 33154.
Published private-residence sizes range from approximately 1,800 to 7,800 square feet. Features include floor-to-ceiling glass and ceilings up to 20 feet high.
No. Listings for concierge support, valet, security, and on-call emergency repair do not by themselves establish hurricane-specific obligations.
Owners should follow current official evacuation instructions and consider an earlier household departure. A lower-category storm should not be treated as assurance that no evacuation order will apply.
Assign a handler and backup, arrange transport with crates or carriers, and confirm a destination that accepts the animals. Keep collars and identification tags on and prepare food, water, and medications.
One week of pet food and water, plus medications, is a useful preparedness provision. It is not presented as a Surf Club requirement.
Pet transportation should not be assumed from advertised concierge services. Confirm any assistance directly and maintain a household backup arrangement.
Household employees need agreed departure, transportation, and communication arrangements. Ask management separately about building staffing, authorized entry, utility procedures, and damage notifications.
Create an inventory, review appraisals where appropriate, and discuss any relocation with qualified handlers in advance. Ask insurance advisers about coverage at home, in transit, and in temporary storage.
Designate a local representative and backup under management's authorization requirements. Confirm official access instructions and building readiness before arranging a return or inspection.