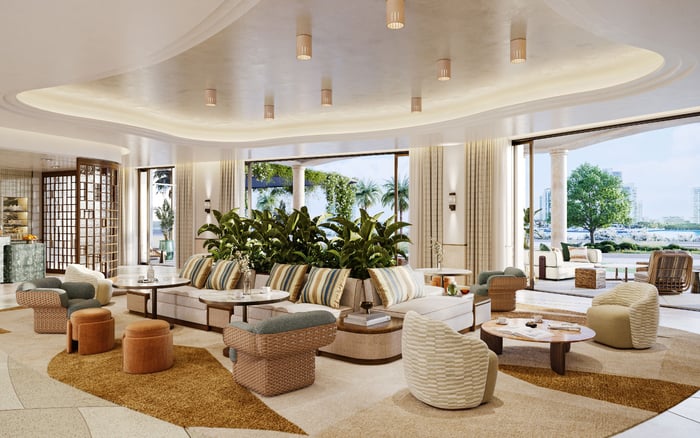
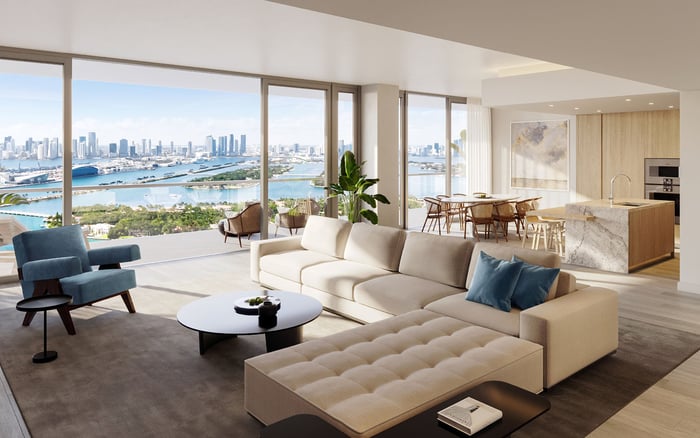
A collector’s Miami residence should accommodate not only the presence of important art, but its departure and return. Thoughtful planning connects display, handling, building access, insurance, and loan permissions without assuming every home can meet every artwork’s needs.
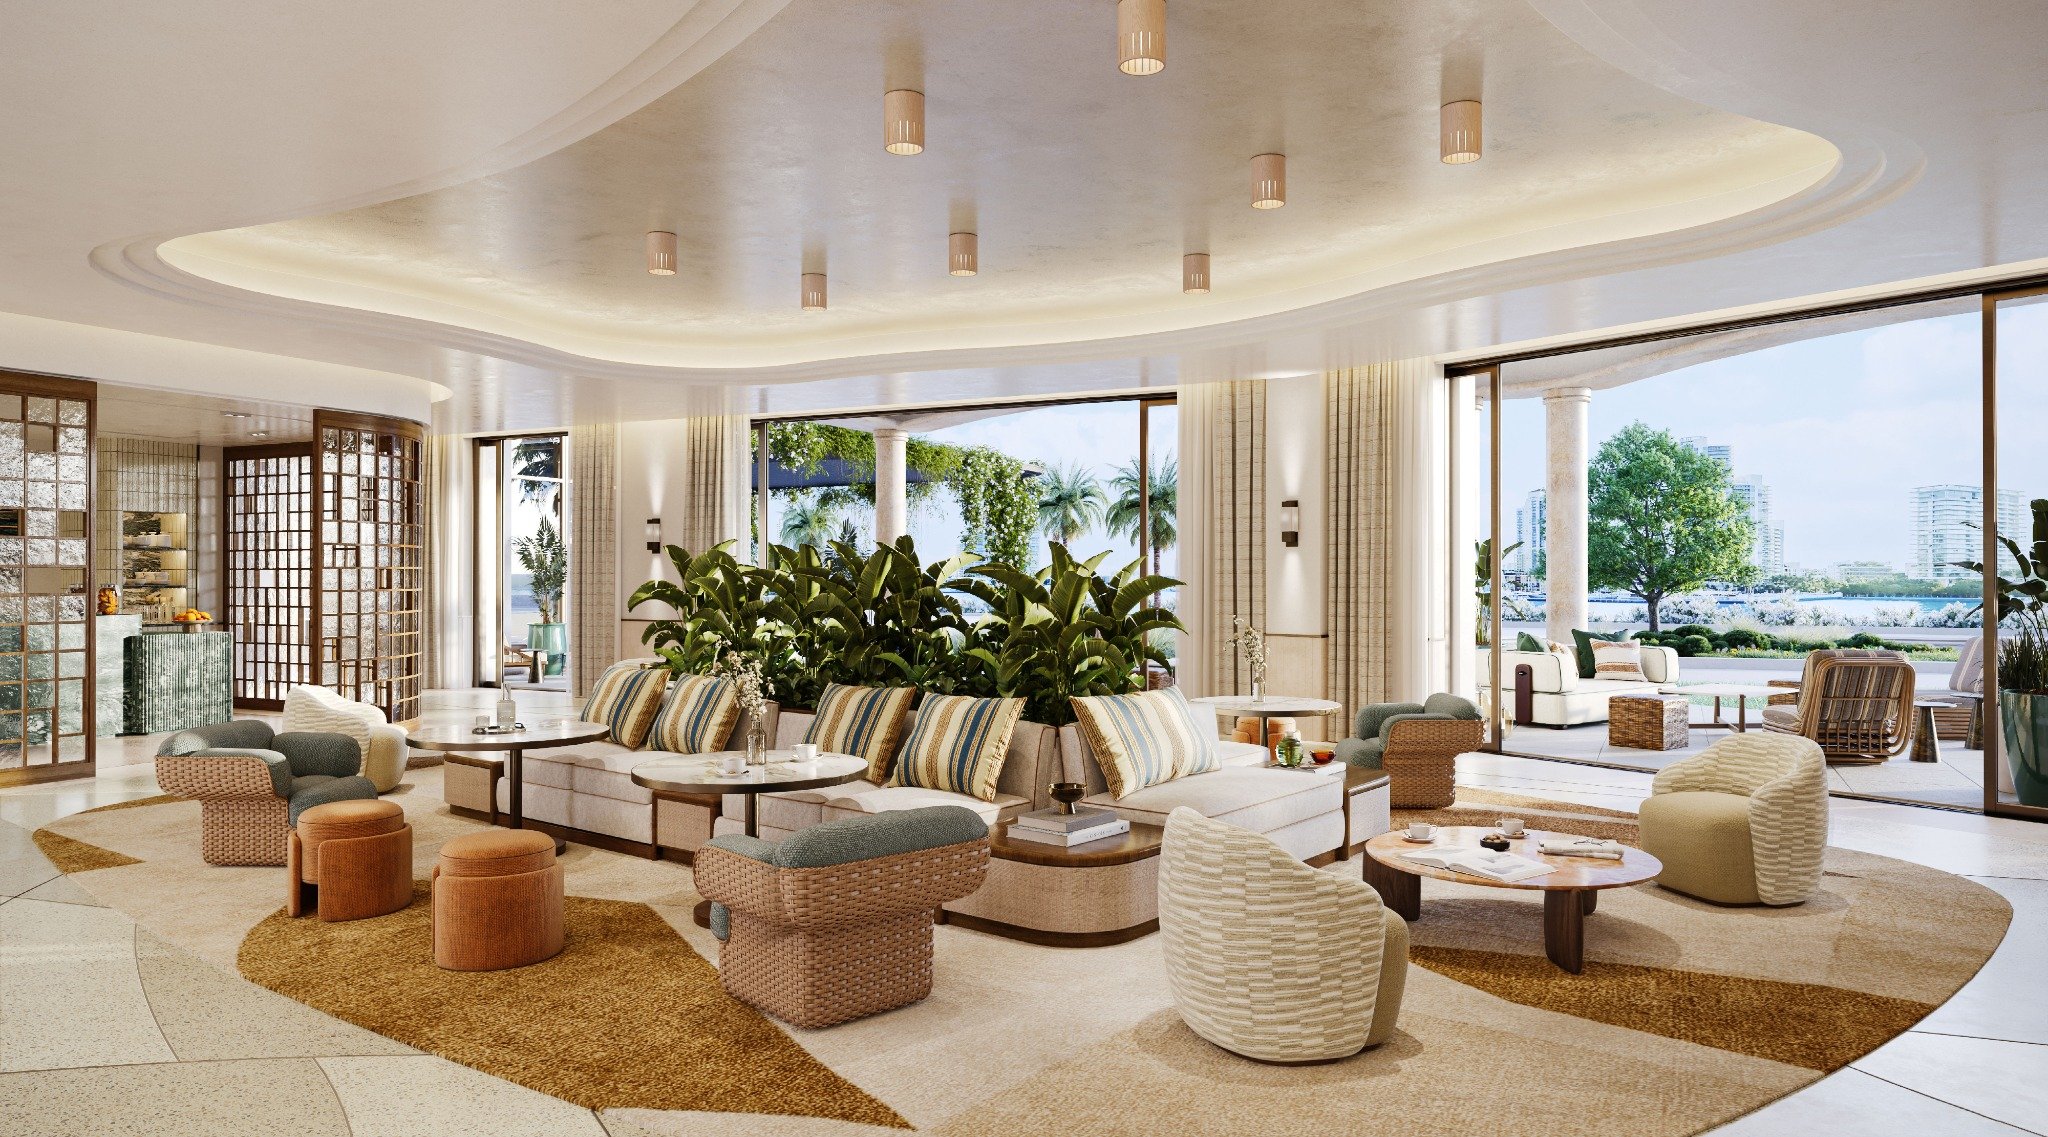
A Miami home built around a collection should be considered in two states: with its defining works installed and with those works away. When a painting leaves for a museum exhibition, the residence must remain composed. When it returns, the route from delivery vehicle to display wall deserves as much attention as the room itself.
The first distinction is contractual, not architectural. A private owner lending to a museum is different from a museum lending to a private residence. Miami’s exhibition culture includes extensive lending by private collections and presentations assembled from borrowed works. Neither establishes a general entitlement to borrow museum art for domestic display.
For a buyer, the useful question is not whether a residence looks like a gallery. It is whether the property can support the particular collection, its lending commitments, and the professionals responsible for its care.
Start with an object schedule rather than a decorative concept. Ask the collection adviser or conservator to identify each proposed work’s dimensions, weight, materials, installation needs, and relevant restrictions. Treat wall reinforcement, adjustable lighting, and environmental monitoring as planning questions, not presumed requirements for every collection.
A beautiful wall may still be unsuitable for a particular object. Ask specialists to review daylight exposure, mounting options, nearby activity, and proposed environmental conditions. Do not substitute a universal temperature, humidity, or light target for object-specific guidance from the lender, conservator, and insurer.
For a buyer considering The Perigon Miami Beach, the review should test the intended installation rather than assume architectural distinction establishes suitability. In Miami Beach or elsewhere, evaluate the art plan against the actual residence and applicable building permissions.
A collection that travels needs a receiving strategy. Before committing to a property, ask the art handler to review the proposed route: vehicle access, delivery scheduling, elevators, doorways, turns, and space for unpacking. The protective crate’s dimensions matter alongside those of the artwork.
In Brickell, a residence under consideration at The Residences at 1428 Brickell should prompt the same practical questions: who approves deliveries, where can handlers work, and what restrictions govern installation? These are due-diligence questions, not statements about the project’s facilities or policies.
Discuss whether temporary receiving space or off-site storage would be appropriate. A delivery should not depend on improvising a safe working area after the crate arrives. Nor should a museum return be scheduled without confirming that the home is ready to receive it.
Loan arrangements can allocate borrowing-related expenses to the borrowing party. Potential costs extend beyond transport to framing, mounting, packing, installation, preservation, and conservation. Establish responsibility for each category before the work leaves its current location.
Ensure the agreement addresses dates, approved destinations, authorized handlers, condition documentation, and procedures for requesting changes. Some institutional loan procedures expressly prohibit relocation without prior authorization. Do not assume a borrowed work can simply move from one room or property to another.
For an owner lending a privately held work, negotiate these points with the borrowing institution. For someone seeking to borrow, establish eligibility and permitted use first. Access to institutional loans can be restricted because of an object’s fragility, age, value, importance, or donor and lender conditions.
Fine-art insurance can accommodate agreed-value arrangements and works that travel, enter exhibitions, or go on international loan. Coverage nevertheless depends on the actual policy. Neither the loan agreement nor the existence of homeowners insurance confirms that every stage is protected.
Ask the broker to reconcile the proposed itinerary with the policy wording. Discuss packing, transit, temporary storage, installation, exhibition, and return, along with valuation and responsibility for arranging coverage. Identify any gap between the lender’s requirements and the protection offered before movement begins.
Standalone private-collection insurance is another option to evaluate, including its potential to separate collection-related claims from homeowners coverage. The appropriate structure is a matter for the owner and insurance adviser, not a universal rule based on the prestige of the address.
A loan can leave a major room without its visual anchor. Rather than treat that absence as a problem to conceal, design a secondary composition: an alternate work, a different furniture arrangement, or a deliberately quieter wall. Any substitute should receive its own installation review.
In Coconut Grove, a buyer considering Park Grove Coconut Grove can use the floor-plan review to test both versions of the interior. Can the room feel complete without its principal painting? Can an alternative piece be installed without unnecessary alterations? These questions concern the buyer’s proposed design, not a promised project feature.
Build flexibility into the return schedule as well. Discuss what happens if an exhibition timetable changes or the residence is undergoing work. An agreed contingency is preferable to choosing a temporary destination under pressure.
A residence remains a home. Consider entertaining, household staff, maintenance, and seasonal absences alongside conservation advice. Ask who may authorize handling, who receives monitoring alerts if monitoring is specified, and who contacts the collection team when circumstances change.
For a Surfside buyer evaluating The Surf Club Four Seasons Surfside, distinguish desired services from responsibilities that require separate arrangements. Confirm the building’s actual scope rather than assuming residential service includes specialist art care, storage, or emergency handling.
Hurricane planning warrants written discussion with the conservator, handler, building management, and insurer. Consider decision-making authority, access, any approved storage alternative, and the permissions needed before moving a loaned work. These are planning topics; the appropriate response depends on the object and the agreement.
The strongest purchase brief brings the collection adviser, designer, art handler, insurance broker, and relevant building representatives into the conversation early. Ask for a practical review of display locations, access routes, permissions, costs, and contingencies before assumptions become part of the interior design.
The objective is not to turn domestic life into a museum operation. It is to let important works move between private enjoyment and public exhibition without making the residence dependent on their permanent presence. That balance gives both the collection and the home room to evolve.
Explore residences with your collection’s next chapter in mind at MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationDo not assume museum works are available for residential display. Eligibility, permitted use, and access depend on the institution’s loan policy and the individual work.
When you lend, your privately held work goes to a borrowing institution under an agreed arrangement. Borrowing museum art requires separate institutional approval and may not be available for private display.
Review display locations, installation needs, receiving routes, building permissions, and possible storage arrangements with the relevant specialists. Evaluate the actual works rather than relying on the residence’s appearance.
No universal settings are established here. Obtain object-specific guidance from the lender, conservator, and insurer before specifying environmental conditions.
Potential expenses include framing, mounting, packing, transit, installation, preservation, and conservation. The agreement should identify who pays for each applicable category.
Check the agreement and obtain any required authorization first. Some institutional loan procedures prohibit relocating works without prior approval.
Do not assume that it does. Ask an insurance adviser to confirm protection for the proposed movement, exhibition, storage, and return under the actual policy terms.
Fine-art policies can use agreed-value structures and accommodate traveling or loaned works. Availability and protection depend on the specific policy.
Plan an alternative composition, such as another suitable work or a quieter wall. Have any replacement installation reviewed for its own requirements.
Discuss decision-making authority, access, approved storage alternatives, and any permissions needed to move the work. Coordinate the plan with the conservator, handler, building management, and insurer.