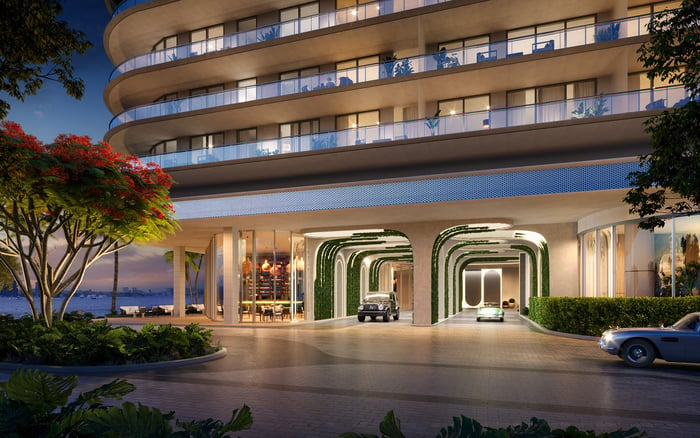
A North Bay Village second home deserves an insurance review as considered as its interiors. This buyer’s audit separates replacement-cost valuations from claim appraisal, identifies who can act for the association, and examines how deductibles could reach an owner’s balance sheet.
The appeal of a North Bay Village residence is the freedom to arrive, settle in, and leave without carrying every operational detail home. That freedom deserves a precise insurance audit. For a buyer considering Continuum Club & Residences North Bay Village, the essential questions extend beyond finishes and services: what property is insured, who can act after a loss, and how would the association fund its deductible?
These are distinct questions-not variations on whether a building has insurance. Florida’s condominium framework establishes obligations and allocation rules, but it does not establish any particular North Bay Village property’s coverage, claims history, or owner exposure. The audit should connect governing documents, insurance contracts, and funding decisions rather than rest on a general assurance that the association is covered.
Florida condominium associations must maintain adequate property insurance for the property they are required to insure. Coverage amounts for full insurable value, replacement cost, or similar coverage may be based on an independent insurance appraisal or an update of an earlier appraisal. The replacement cost of the property to be insured must be determined at least once every three years.
That valuation addresses insurance limits. It is distinct from a contractual appraisal provision that might apply when a claim is disputed. A replacement-cost appraisal does not, by itself, guarantee access to a claim-appraisal procedure.
Request the latest replacement-cost determination and ask the insurance professional to compare it with current policy limits. Separately, have counsel and the insurance professional examine any claim-appraisal clause: when can it be invoked, what conditions apply, which issues can it address, and what steps does the contract require? Do not assume its scope-including how causation questions might be treated-without reviewing the actual wording and applicable law.
The distinction is straightforward: one review concerns the value used to arrange coverage; the other concerns a possible mechanism for resolving a claim disagreement.
Lifestyle convenience should include a clear route for communicating about a loss. A buyer evaluating Shoma Bay North Bay Village should request the named-insured information, bylaws, relevant board resolutions, and management agreement. Review these documents together to identify who may report, negotiate, and settle a master-policy claim.
Those powers are not interchangeable. Ask the association to identify the contact for reporting a loss, the person responsible for insurer communications, and the authority required to accept a settlement. Where a role is delegated, ask advisers to confirm that delegation rather than infer it from a job title.
For an owner who travels frequently, request a written communication plan: whom should the owner contact, who follows up, and how will material claim decisions reach the owner? This is a practical due-diligence recommendation, not a statement that every association must follow an identical procedure. The aim is to replace informal promises with defined responsibilities.
Florida law permits association insurance policies to contain deductibles established by the board. Those deductibles must be consistent with industry standards and prevailing practices for communities of similar size, age, construction, and facilities in the relevant location. The board must establish deductible amounts at a meeting conducted in accordance with statutory requirements.
In setting deductibles, the board may consider available funds, including reserves, or predetermined assessment authority available when insurance is obtained. For the buyer, the funding question is therefore as important as the deductible amount.
Request complete policies and endorsements, separate deductible schedules, and relevant board records. Then ask how the association expects to meet each applicable deductible: through available funds, an assessment, or a combination? Have advisers distinguish the board’s stated plan from the funds and authority actually available.
A reference to reserves does not prove that a particular reserve balance can or will pay a loss. Ask counsel and the insurance professional to evaluate the proposed funding approach against the governing documents and applicable rules. A deductible becomes meaningful to the buyer only when its financing is understood.
A loss affecting or originating in one unit does not, by itself, establish that its owner must personally pay the association’s deductible. Statutory allocation rules and applicable exceptions matter. Nor should a buyer presume that every deductible will be divided equally among all owners.
Common expenses include the operation, maintenance, repair, replacement, and protection of common elements and association property. The declaration’s insurance, maintenance, and common-expense provisions belong in the same review. Read alongside applicable law, they help advisers assess the relevant allocation rather than rely on a convenient rule of thumb.
For a purchase at Tula Residences North Bay Village, request the same document-based analysis rather than infer the answer from the project’s identity. Ask counsel to explain how a loss confined to one residence and a loss affecting shared property would be analyzed, without presuming either result. These are review scenarios, not claims about that project’s insurance or loss history.
Florida’s insurance code separately addresses residential condominium unit-owner insurance and required loss-assessment coverage. That does not mean every association assessment is insured under an owner’s HO-6 policy.
Have the buyer’s insurance professional confirm loss-assessment limits, covered perils, and the treatment of association deductibles. The question is not simply whether loss-assessment coverage appears on a declarations page, but how the actual policy would respond to the exposure under review.
The same discipline applies when comparing North Bay Village with a Miami Beach option such as Five Park Miami Beach. Compare the insurance documents separately for each property. A shared second-home purpose is not evidence of equivalent coverage or deductible allocation.
Complete the review with open-claim information and any pending renewal or nonrenewal notices. Ask advisers to distinguish conclusions about current coverage from questions requiring follow-up before closing. A review of today’s documents is not a promise about future renewals.
A useful closing deliverable is a short insurance-and-deductible memorandum reviewed by a Florida condominium attorney and insurance professional. It should summarize insured property and limits, the replacement-cost determination, any claim-appraisal provision, claim authority, deductible funding, allocation considerations, and HO-6 questions. This memorandum is a due-diligence recommendation, not a statutory requirement.
The objective is not to eliminate uncertainty. It is to understand who acts, which documents govern, and where an owner may need liquidity before leaving the residence unattended.
Explore South Florida residences with a more considered ownership perspective at MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationReview insured property, policy limits, appraisal provisions, claim authority, deductible funding and allocation, and the owner’s HO-6 coverage.
Florida’s condominium framework requires the replacement cost of the property to be insured to be determined at least once every three years.
No. The replacement-cost provision concerns insurance limits; access to a disputed-claim appraisal process requires separate review of the policy and applicable law.
The answer requires reviewing named-insured information, bylaws, board resolutions, and the management agreement. Do not assume that the person reporting a claim also has settlement authority.
Yes. The board must establish deductible amounts at a compliant meeting, and deductibles must be consistent with industry standards and prevailing practices for comparable communities in the relevant location.
Not by itself. Statutory allocation rules, applicable exceptions, and the relevant governing documents require review before assigning responsibility.
No. Have counsel review the declaration’s insurance, maintenance, and common-expense provisions alongside applicable law before assuming an allocation.
Yes, the board may consider available funds, including reserves, or predetermined assessment authority. Buyers should still verify the proposed funding plan rather than assume reserves will pay a particular loss.
Do not assume it does. Ask the insurance professional to confirm limits, covered perils, and the policy’s treatment of association deductibles.
The memorandum described here is a due-diligence recommendation, not a statutory requirement. Review by a Florida condominium attorney and insurance professional can help clarify the buyer’s exposure.