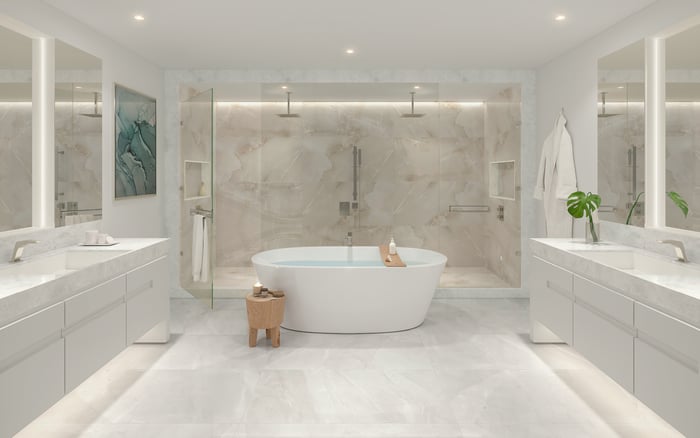
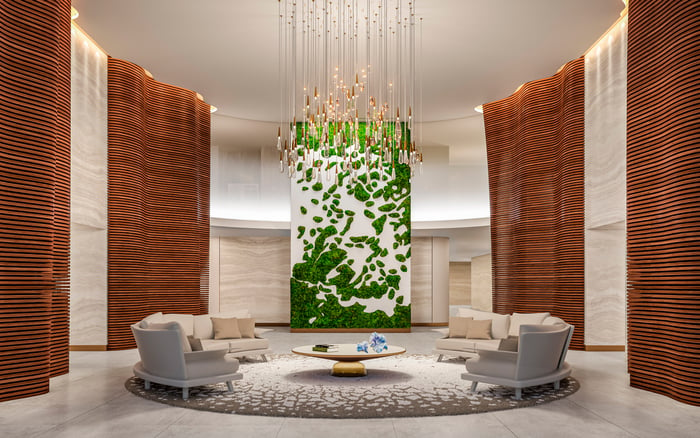
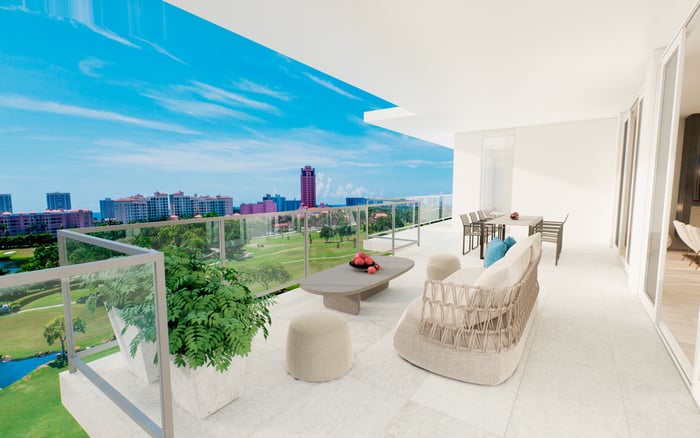
A disciplined acquisition framework for Mr. C Residences Boca Raton, separating projected ownership costs from negotiated protections and organizing assessment disclosures, seller credits, and escrow holdbacks into a closing-ready file.
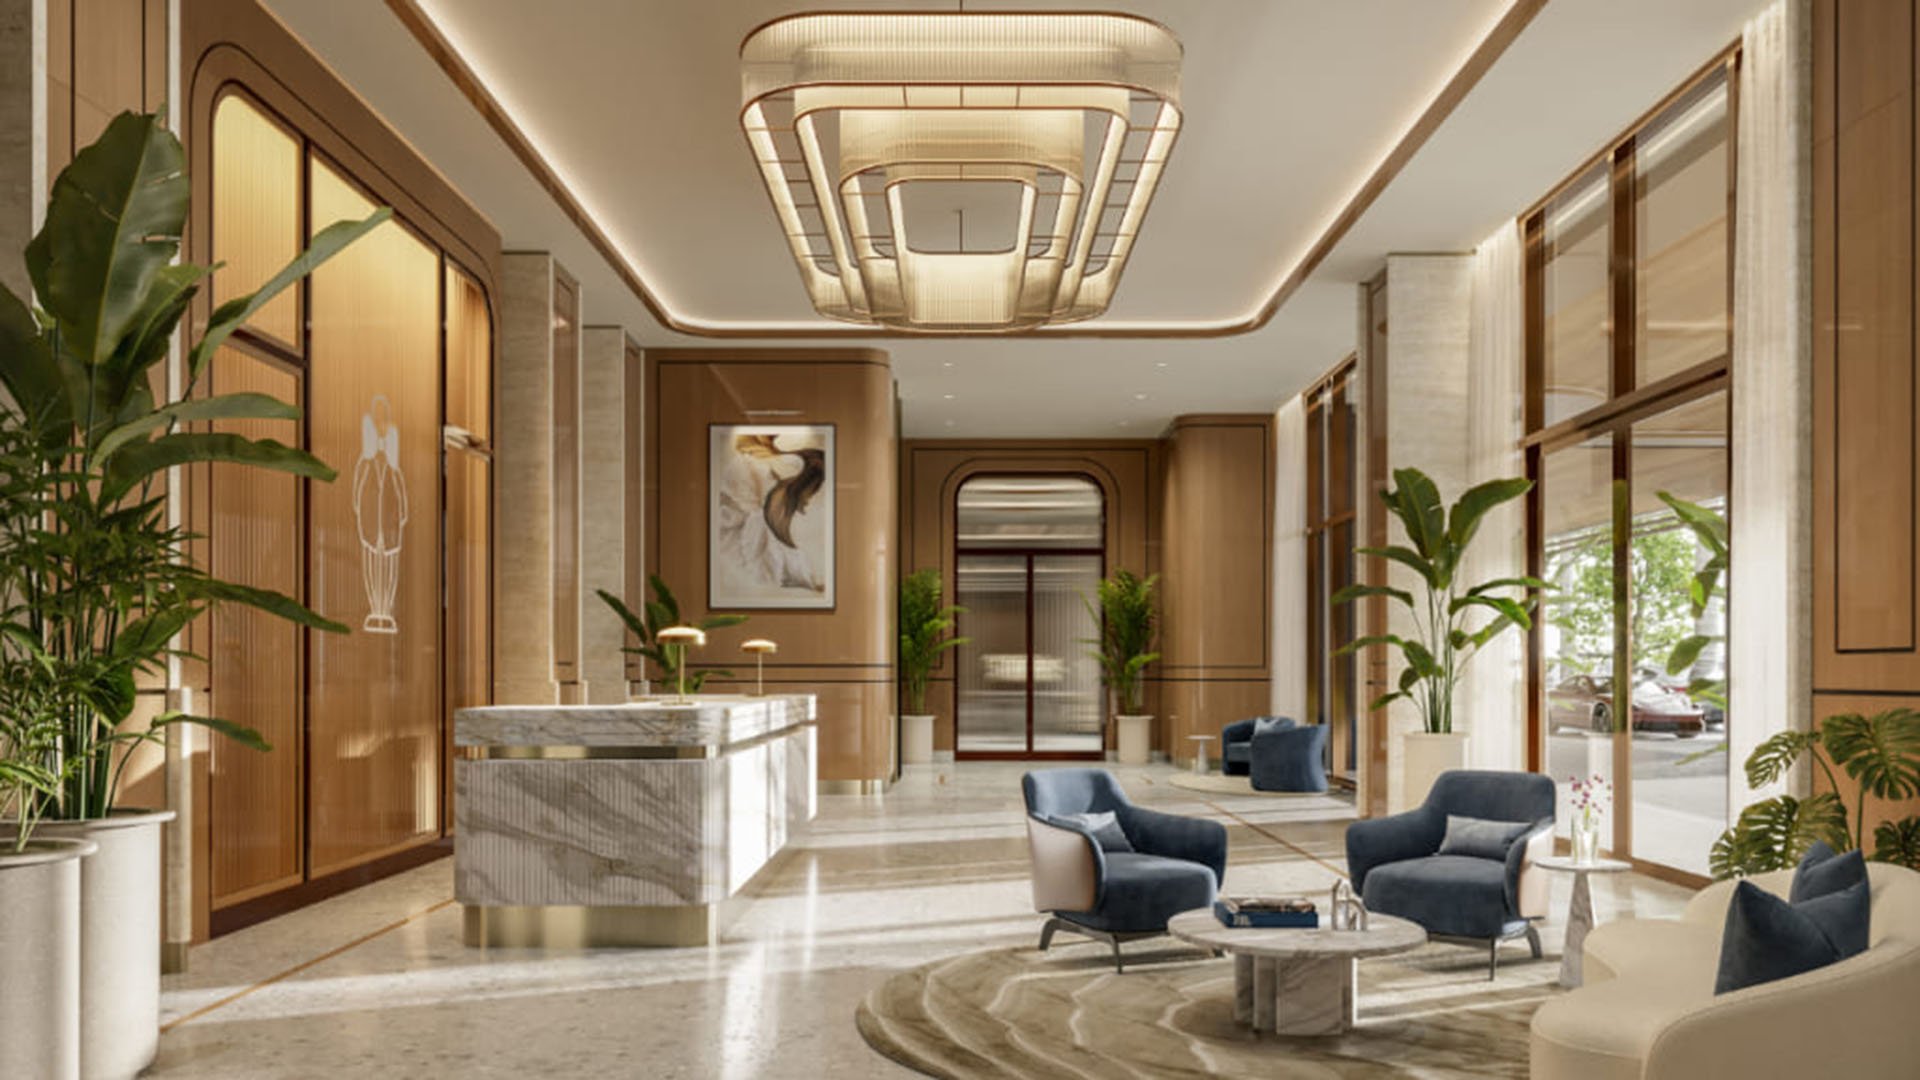
For a family office considering Mr. C Residences Boca Raton, the acquisition decision extends beyond layout and service. The more consequential question is how the contract allocates costs and unresolved obligations between signing, closing, and completion. A beautifully appointed residence deserves an equally precise diligence file.
The project is marketed as 133 private residences with two- and three-bedroom layouts at 41 SE 4th Street, Boca Raton. The sales gallery occupies a separate address: 36 SE 3rd Street. Planned offerings include Bellini Restaurant, rooftop amenities, wellness and fitness facilities, racquet amenities, concierge, and valet services.
These features establish the lifestyle proposition, not the final ownership economics. A public unit-by-unit special-assessment schedule, project-wide seller-credit program, and standard escrow-holdback policy are not established here. Treat each as a matter for written inquiry or negotiation-not an included benefit or an existing liability.
A transaction file should distinguish three categories: marketed specifications, executed contractual obligations, and open diligence requests. Conflating them can turn an attractive projection into an assumed promise.
Request the declaration, bylaws, purchase agreement and addenda, proposed budget, reserve schedule, insurance summary, management and amenity agreements, warranties, and amendments. Have counsel identify the documents governing each material obligation and track subsequent revisions against the original underwriting.
For each unresolved item, record the requested document, responsible party, response date, and required follow-up. An unanswered assessment question should remain open; it should not become a zero in the acquisition model.
The same discipline applies when evaluating Alina Residences Boca Raton alongside the subject property. Compare the documents supporting each opportunity without assuming that one project's contractual protections or expense allocations apply to another.
Request written disclosure of approved, proposed, or noticed special assessments before signing, then refresh the request before closing. The objective is to distinguish a presently payable obligation from a possible future cost-and establish who bears each exposure.
Organize the response into a schedule that identifies:
The assessment's purpose and status, including whether it is approved or merely proposed.
The amount allocated to the residence and the basis for that allocation.
Each installment amount, due date, and outstanding balance.
The proposed buyer-seller allocation and the document recording that agreement.
Any unresolved increase, reallocation, or payment condition requiring further review.
Do not assume that an assessment approved before closing is necessarily paid entirely by the seller, or that installments due afterward automatically fall to the buyer. Ask Florida condominium counsel to reconcile the governing documents, applicable requirements, and negotiated allocation.
If no assessment is disclosed, obtain a written response addressing the requested categories. That response is useful diligence evidence, not a guarantee against future assessments.
Projected common charges circulated in March 2026 were approximately $1.67 per square foot per month, inclusive of reserves. This is a dated projection, not a confirmed final charge. Including reserves does not establish an assessment ceiling or eliminate future funding needs.
Request the current proposed budget and confirm the area measurement used to calculate the residence's charges. Then stress-test insurance, payroll, utilities, repairs, reserve contributions, and hospitality operations. The investment committee should see both the stated projection and the effect of higher recurring costs.
For amenities and services, ask which expenses fall within common charges, which may be charged separately, and which agreements govern the allocation. Do not infer the restaurant's financial relationship with the association from its inclusion in the amenity offering.
A comparison with Glass House Boca Raton should likewise begin with each property's own budget and agreements. A headline monthly figure is no substitute for understanding the costs it covers.
Model a seller credit only after its terms are documented in a signed agreement. No verified project-wide credit program is established for this acquisition framework; a proposed concession should not be presented as an available developer offer.
Any negotiated credit should specify its amount, permitted use, conditions, and timing. Counsel should address what happens if the intended expense is lower than the credit or if closing circumstances change. Relevant advisers should review lender acceptance and tax treatment before the concession enters the final acquisition economics.
A promise to cover assessments requires particular care. Define whether it covers a fixed dollar amount, a stated period, or specifically identified assessments. Address subsequent increases and reallocations rather than relying on a broad phrase such as prepaid assessments.
Keep the credit distinct from the underlying liability allocation. The closing statement should make both clear, leaving no ambiguity about what is paid, credited, or outstanding.
A holdback is a proposed contractual mechanism, not an established entitlement at this project. Potential subjects for negotiation include unfinished punch-list work, undelivered finishes or amenities, and unresolved permit, title, or lien issues. Availability and enforceability require transaction-specific review.
Start with the covered obligation, then define the amount and administration. A proposed holdback agreement should identify:
The escrow agent, funding amount, and specific covered claims.
Objective completion standards and evidence required for a draw or release.
Notice procedures, cure periods, and a dispute-resolution process.
The release deadline, treatment of unresolved claims, and allocation of interest.
Do not rely solely on a general promise of satisfactory completion. Specify the documents, inspections, or other evidence counsel considers appropriate to establish performance. Address partial completion expressly, so releasing funds for one resolved item does not inadvertently extinguish protection for another.
The amount should reflect the identified exposure, not merely appear substantial relative to the purchase price.
The marketed 2029 completion projection is not a verified contractual delivery deadline. Confirm delivery provisions in the purchase agreement and refresh construction diligence independently. Pursue unavailable municipal permit and inspection documents through a public-records request or Development Services.
Before closing, have Florida condominium counsel confirm disclosure and cancellation rights and reconcile assessment allocations, credits, and any negotiated holdback with the closing documents. Refresh insurance, title, permit, and construction reviews rather than carrying early assumptions forward unchanged.
Final approval should identify what remains uncertain, who bears that exposure, and which signed provision addresses it. For a family office, that clarity is part of the residence's value: the lifestyle can remain effortless because the acquisition was not.
For a discreet perspective on South Florida residential acquisitions, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationThe project address is 41 SE 4th Street, Boca Raton. The separate sales gallery is at 36 SE 3rd Street.
The offering markets 133 private residences with two- and three-bedroom layouts.
A public unit-by-unit special-assessment schedule is not established here. Request written disclosure of approved, proposed, or noticed assessments before signing and again before closing.
It should identify the assessment's purpose, status, unit allocation, installment amounts, due dates, and outstanding balance. The buyer–seller allocation should be documented separately and reconciled at closing.
The March 2026 projection of approximately $1.67 per square foot per month included reserves. That projection is not a confirmed final charge or a guarantee against future assessments.
No verified project-wide seller-credit program is established here. Any proposed credit should specify its amount, permitted use, conditions, and timing in a signed agreement.
Specify whether the concession covers a fixed amount, a stated period, or particular assessments. Address later increases and reallocations explicitly.
No standard holdback policy or automatic entitlement is established here. A proposed holdback requires negotiation and transaction-specific legal review.
Identify the agent, amount, covered claims, objective completion standards, draw evidence, cure periods, dispute process, release deadline, and interest treatment.
No. It is a marketing projection, not a verified contractual deadline; review the purchase agreement and independently refresh construction and permit diligence.