For a family office choosing between Downtown Miami and Edgewater, the decisive differences sit inside the building documents: rental permissions, buyer approvals, reserve funding and the cost of waiting for an orderly exit.
For a family office, choosing between Downtown Miami and Edgewater is less a contest between skylines than a decision about control. A residence must serve the family today without unnecessarily narrowing its options tomorrow. The central questions are resale depth, acquisition approvals, permissible leasing and the financial capacity to wait for an acceptable exit.
Neither higher neighborhood prices nor broader rental permissions establish superior liquidity. The more defensible acquisition is the one whose governing documents, carrying costs and comparable sales support the intended ownership plan. Architectural distinction can shape the shortlist; documented flexibility should determine the commitment.
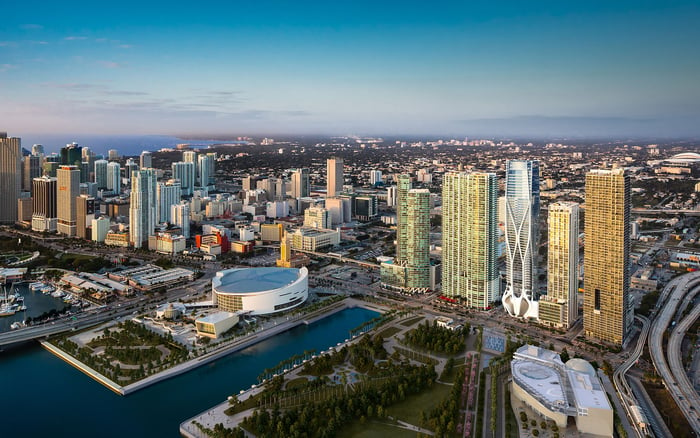
A Downtown Miami search that includes Aston Martin Residences Downtown Miami should begin with the same investment questions as an Edgewater search. The project name is a starting point, not evidence of its approval process, rental permissions or future resale speed.
A neighborhood price range is not a valuation for a particular residence. Nor does it establish which neighborhood offers a faster or more certain exit. Scarcity and liquidity are not interchangeable.
For a candidate at Aria Reserve Miami, the next step is a residence-specific comparison. Examine closed sales of residences with comparable size, condition, outlook and ownership costs. Distinguish asking prices from achieved prices.
The family office should request building-level evidence of marketing periods, competing inventory and concessions. Until that comparison is assembled, neither Downtown nor Edgewater warrants a blanket liquidity premium. An exceptional residence can still require a patient seller.
Buyer approval and tenant approval answer different questions. The first concerns the acquisition process; the second concerns a future leasing strategy. A building’s willingness to approve a tenant does not establish how it handles a purchaser. Neither process should be inferred from neighborhood practice.
Before committing to a closing schedule, ask counsel and management to confirm any purchaser application requirements, submission deadlines, interviews, fees and approval steps in the applicable documents. Establish what constitutes a complete submission and who confirms its status. These are diligence questions, not assumed requirements at every condominium.
If ownership through an entity is contemplated, ask what documentation the proposed structure would require. The investment committee should distinguish a timetable supported by written requirements from an optimistic closing assumption. Apply that discipline equally when considering One Thousand Museum Downtown Miami or another residence on the shortlist.
Do not assign a rental strategy to a residence based on its neighborhood. Ask counsel and management to verify applicable zoning, condominium restrictions and any other requirements before treating a proposed lease as permissible.
For a residence under consideration at EDITION Edgewater, confirm the actual rules rather than relying on neighborhood assumptions. Review any minimum terms, annual rental limits, tenant approvals, waiting periods, owner-occupancy requirements and prohibitions against short stays.
For family use with occasional leasing, model only the rental windows the documents permit. For an income-led purchase, test whether those windows support the intended tenancy pattern. Broader permissions may preserve options, but they do not guarantee occupancy, net income or a quicker resale.
Structural condition and association finances belong in the exit analysis from the outset. Unresolved work, inadequate reserves and pending assessments can prompt buyer discounts or demands for concessions. A residence’s presentation cannot resolve an uncertain building obligation.
Ask counsel to confirm which milestone inspection, structural-integrity reserve study and Miami-Dade recertification requirements apply to the particular building, including any deadlines or outstanding steps. Do not treat one completed document as a substitute for reviewing the full set of applicable obligations.
Review inspection and engineering documents, reserve studies and funding schedules, budgets, financial statements, insurance declarations and open violations. Verify actual reserve funding rather than relying on the existence of a study. Distinguish identified work, its anticipated funding and unresolved exposure. That distinction matters both to the present owner’s capital planning and to a future buyer’s confidence.
Build a residence-specific ownership budget using verified association fees, property taxes and insurance costs. Separate recurring expenses from potential assessment exposure, and avoid substituting neighborhood estimates for the obligations attached to the actual residence.
Gross rent alone is an insufficient investment measure. Compare potential rental receipts with the expenses and permitted leasing schedule of the candidate residence rather than assuming a headline yield will translate into an achievable return.
Prepare separate ownership scenarios for family occupancy, permitted leasing and a delayed sale. Include applicable financing, vacancy, management, transaction expenses and assessment exposure rather than assuming a headline net yield captures every cost. The key question is how comfortably the family can retain the residence without accepting an unattractive offer.
A future sale date should be a planning assumption, not a forecast. Revisit the exit when comparable transactions support the desired pricing, building obligations are clear and any tenancy aligns with the intended sale strategy. None of these conditions guarantees execution, but each supports a more informed decision.
Base the choice between Downtown Miami and Edgewater on a building-specific investment memorandum: purchase basis, approval path, documented rental flexibility, funded obligations and carrying capacity. The stronger acquisition fits the family’s use while preserving a credible alternative if its plans change.
For a discreet conversation about aligning your residence search with long-term ownership priorities, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNeither neighborhood warrants an automatic liquidity advantage. Compare building-level closed sales, marketing periods, competing inventory and concessions rather than relying on neighborhood prices.
Examine closed sales of residences with comparable size, condition, outlook and ownership costs. Distinguish achieved prices from asking prices rather than treating a neighborhood range as a valuation.
No; buyer approval concerns the acquisition process, while tenant approval concerns leasing. Verify each separately in the applicable building documents.
Confirm any application requirements, deadlines, interviews, fees and approval steps before setting a closing schedule. If an entity will own the residence, ask what documentation that structure requires.
Do not assume daily rentals are permitted based on the neighborhood. Verify the proposed leasing strategy against the applicable condominium documents and regulatory requirements.
Check for minimum lease terms, annual rental limits, tenant approvals and prohibitions against short stays. Underwrite only the leasing schedule confirmed for the particular residence.
Ask counsel and management to confirm any new-owner waiting periods, occupancy requirements and tenant approval steps. Do not budget immediate rental income before those details are verified.
Do not rely on zoning alone. Have counsel review condominium restrictions and any other applicable requirements before treating a proposed rental as permissible.
Ask counsel to identify the inspection, reserve-study and recertification requirements applicable to the building. Review actual reserve funding, identified work and unresolved obligations alongside those documents.
Use a target date as a planning assumption rather than a guaranteed outcome. Reassess comparable sales, building obligations, tenancy and carrying capacity before deciding to exit.