A discreetly run home requires more than thoughtful design. This Coral Gables buyer’s guide connects umbrella liability, household-employment coverage, caregiver access and long-term living plans into a practical pre-closing review.
A Coral Gables residence should serve the life a buyer enjoys today and the household that may take shape over time. A nanny may become a regular driver. A visiting companion may eventually provide daily support. Retirement may bring more time at home, different staffing and a fresh look at ownership arrangements.
For a 2026 purchase, treat insurance, caregiver access and aging-in-place planning as one coordinated exercise. The objective is not simply a larger liability limit, but a clear understanding of which policy responds, who employs each worker and whether the residence can support the family’s intended routine.
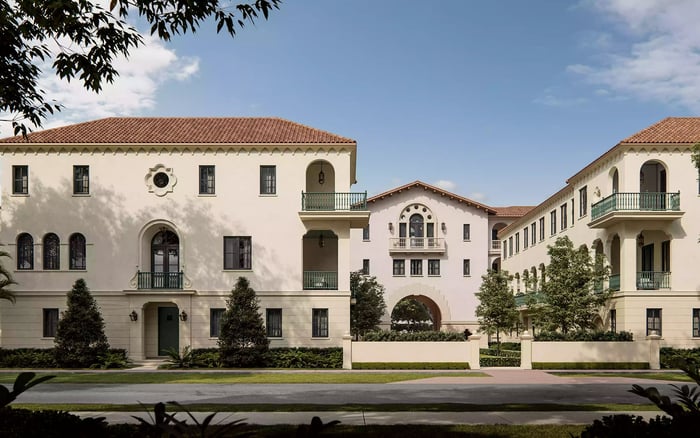
When considering Ponce Park Coral Gables, bring those household requirements to the purchase review alongside the floor plan. Ask about the arrangements your household would need rather than assuming residential services include caregiver coordination or particular access privileges.
Personal umbrella insurance adds liability protection above homeowners, auto and other eligible policies once their underlying limits are exhausted, subject to policy terms. This additional layer does not replace insurance for the home itself or address every risk associated with its staff.
Net worth is a useful starting point for selecting a limit, but not the only measure. Future income, existing liability limits and lifestyle exposures also belong in the discussion. Teen drivers, pools, boats and rental properties can materially change the assessment.
For high-net-worth households, $3-5 million can serve as a discussion range-not a legal minimum or an independently measured local norm. Households with more than $5 million in net worth and a high-profile profession may wish to discuss $5-10 million. Neither range replaces an individualized review.
Before changing homeowners or auto coverage, confirm the umbrella insurer’s minimum underlying limits. Ask the adviser to review how the policies work together and identify exclusions, eligible exposures and any conditions that could affect a claim. A generous headline limit is useful only when the underlying arrangements meet the policy’s requirements.
A household with employees needs more than a homeowners policy and an umbrella. Review homeowners liability, workers’ compensation for covered employee injuries, and umbrella protection for eligible excess liability claims as distinct forms of protection. Employee health and benefit coverage remains a separate matter.
For households with nannies, homeowners liability limits of $300,000-$500,000 are a starting range to review, not a guarantee of sufficient protection or umbrella eligibility. Confirm the actual underlying-limit requirement with the umbrella insurer.
Do not assume homeowners insurance will address a staff injury. Standard forms typically exclude domestic-employee coverage where workers’ compensation is legally required. Voluntary workers’ compensation can provide medical and disability benefits for covered work-related injuries, reducing reliance on homeowners liability protection.
Confirm whether Florida law requires coverage for the particular household with qualified counsel and an insurance adviser. Do not base the decision on a generalized employee-count rule or an assumed domestic-worker exemption. Describe each worker’s duties and employment arrangement before deciding whether coverage is required or advisable.
Employment Practices Liability Insurance, or EPLI, deserves a separate conversation. It addresses allegations such as harassment, discrimination and wrongful termination. Do not presume an umbrella covers those disputes, employee injuries or caregiver professional negligence.
For a family evaluating Cora Merrick Park, caregiver access belongs in pre-purchase diligence. Request the applicable written rules and discuss the schedule the family anticipates. Specific questions are more useful than assumptions about what a residence provides.
Ask how recurring caregivers would be authorized, how replacements would be admitted and what arrangements would apply to overnight support. Clarify arrival procedures, parking, keys or credentials, and how access would be withdrawn when an assignment ends. These are verification questions, not statements about a building’s policies.
Within the household, establish written instructions and training for vehicle use, pool use, guest access and emergencies. Designate a family contact for decisions and explain how a caregiver should escalate an urgent concern. Keep the instructions consistent with the worker’s agreed duties.
Directly employing a caregiver also calls for a review of payroll obligations and employee-injury insurance. When using an agency, request evidence of the relevant coverage and have the adviser review it alongside the service agreement. Licensing alone is not proof that workers’ compensation or professional-liability protection is in place.
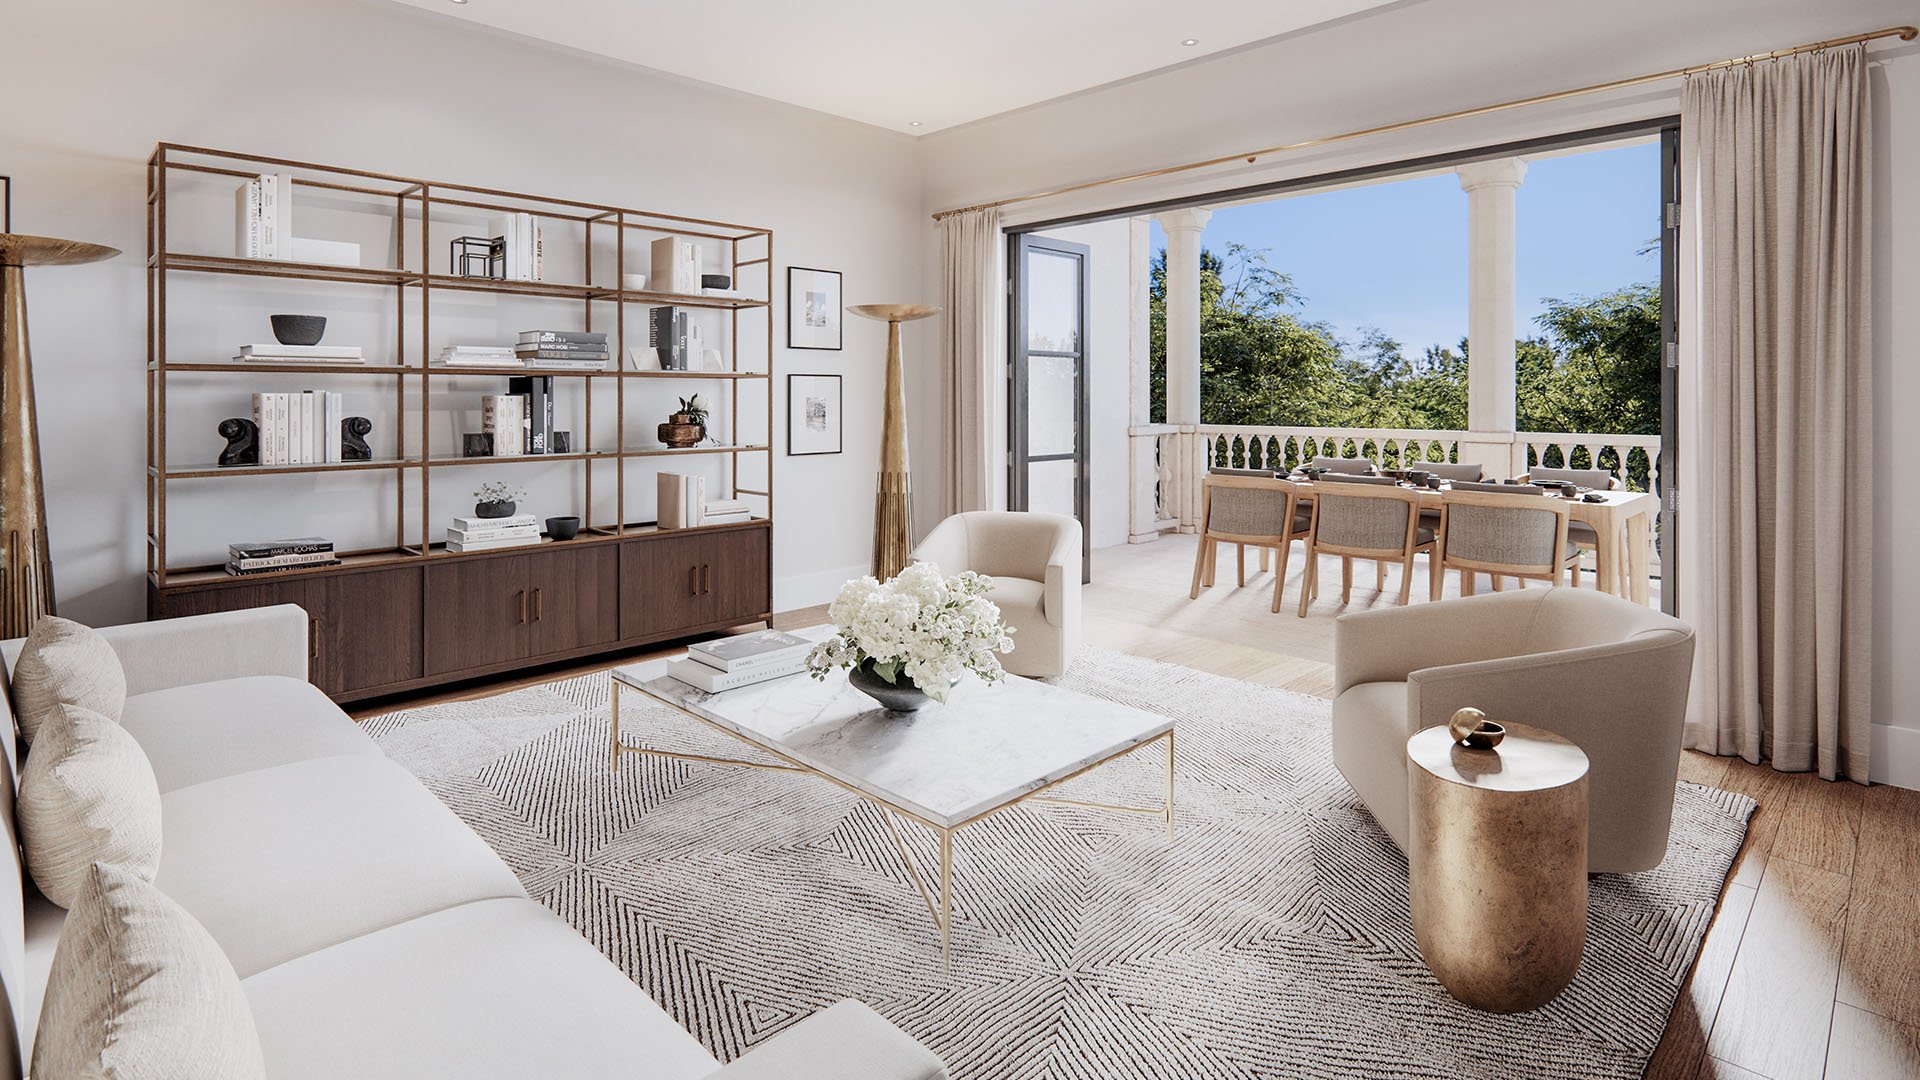
Aging in place begins with a practical question: would this residence still support daily life if assistance became routine? Before selecting The Village at Coral Gables, consider asking an appropriate design or care professional to assess the specific residence against anticipated needs.
Focus the assessment on everyday movement, privacy during care, room for assistance and how living spaces serve household routines. These are planning priorities, not assurances that a particular property is accessible or that a proposed alteration will be permitted. Obtain property-specific advice before relying on future changes.
Retirement and the introduction of in-home care are also occasions to reassess liability coverage. More time at home, new workers and changing responsibilities can alter the household’s exposure even when the address remains the same. Revisit the plan as care duties expand rather than treating the initial insurance purchase as permanent.
The insurance review should reflect how assets are actually held. Coordinate umbrella coverage with estate arrangements, including trusts and investment-property entities. Do not assume a policy written for an individual automatically addresses every ownership structure.
Ask the insurance adviser and estate counsel to compare ownership documents with the policy’s insured parties and eligible exposures. The aim is consistency between the family’s legal arrangements and its insurance protection. A change in title or household structure warrants another review of that alignment.
Before closing, assemble the proposed ownership structure, current liability policies, vehicle and property exposures, and a description of anticipated staff duties. Request written clarification of umbrella prerequisites, employee-injury coverage and any proposed EPLI protection.
Separately, confirm the residence’s caregiver-access arrangements and commission any needed review of its suitability for longer-term living. Keep unresolved questions in view until the relevant adviser or property representative has answered them. The most durable luxury is a home whose daily operation remains thoughtfully planned as circumstances change.
Explore your next Coral Gables residence with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationIt adds liability protection above homeowners, auto and other eligible policies when their underlying limits are exhausted. Coverage remains subject to the umbrella policy’s terms and exclusions.
A $3–5 million limit can be a discussion range, while households above $5 million in net worth with a high-profile profession may discuss $5–10 million. The appropriate limit depends on assets, future income and household exposures, not a legal minimum.
Umbrella insurers require minimum liability limits on underlying policies. Confirm those requirements before changing homeowners or auto coverage.
No. It does not replace workers’ compensation or employee health and benefit coverage, and employment disputes require a separate coverage review.
Do not assume a universal rule or rely on a generalized employee threshold. Have qualified counsel and an insurance adviser confirm the requirements under current law for the specific employment arrangement.
It can provide medical and disability benefits for covered work-related staff injuries. Coverage terms should be reviewed rather than assuming homeowners liability will respond.
Employment Practices Liability Insurance addresses employment-related allegations such as harassment, discrimination and wrongful termination. Evaluate it separately from umbrella coverage.
Request written rules and clarify recurring authorization, substitute caregivers, overnight support and access credentials. Confirm the arrangements for the specific residence rather than assuming particular privileges.
Licensing alone should not be treated as proof of workers’ compensation or professional-liability coverage. Request relevant coverage documentation and have an adviser review it with the service agreement.
Retirement, the introduction of in-home care and changes in staff duties are useful review points. Also revisit coverage when ownership or estate arrangements change.