A disciplined approach to Key Biscayne condominium carrying costs, separating service expenses, insurance renewals, reserve catch-up funding, and future replacement costs before purchase.
In Key Biscayne, the purchase price secures the residence. The association budget helps sustain the experience: maintained common spaces, staffed entrances, working amenities, and financial preparedness. For a 2026 buyer, the central question is not simply whether monthly charges appear competitive, but whether they rest on credible assumptions.
A lower fee does not automatically represent better value. It may reflect different service inclusions, fewer operating commitments, or insufficient provision for future work. A higher fee deserves equal scrutiny: what does it fund, and how much uncertainty remains outside it?
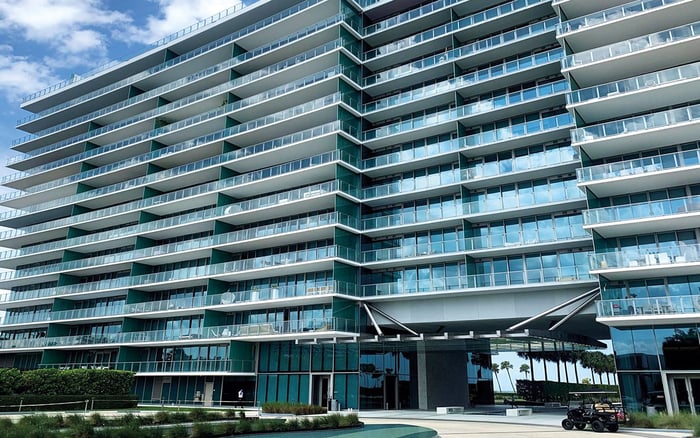
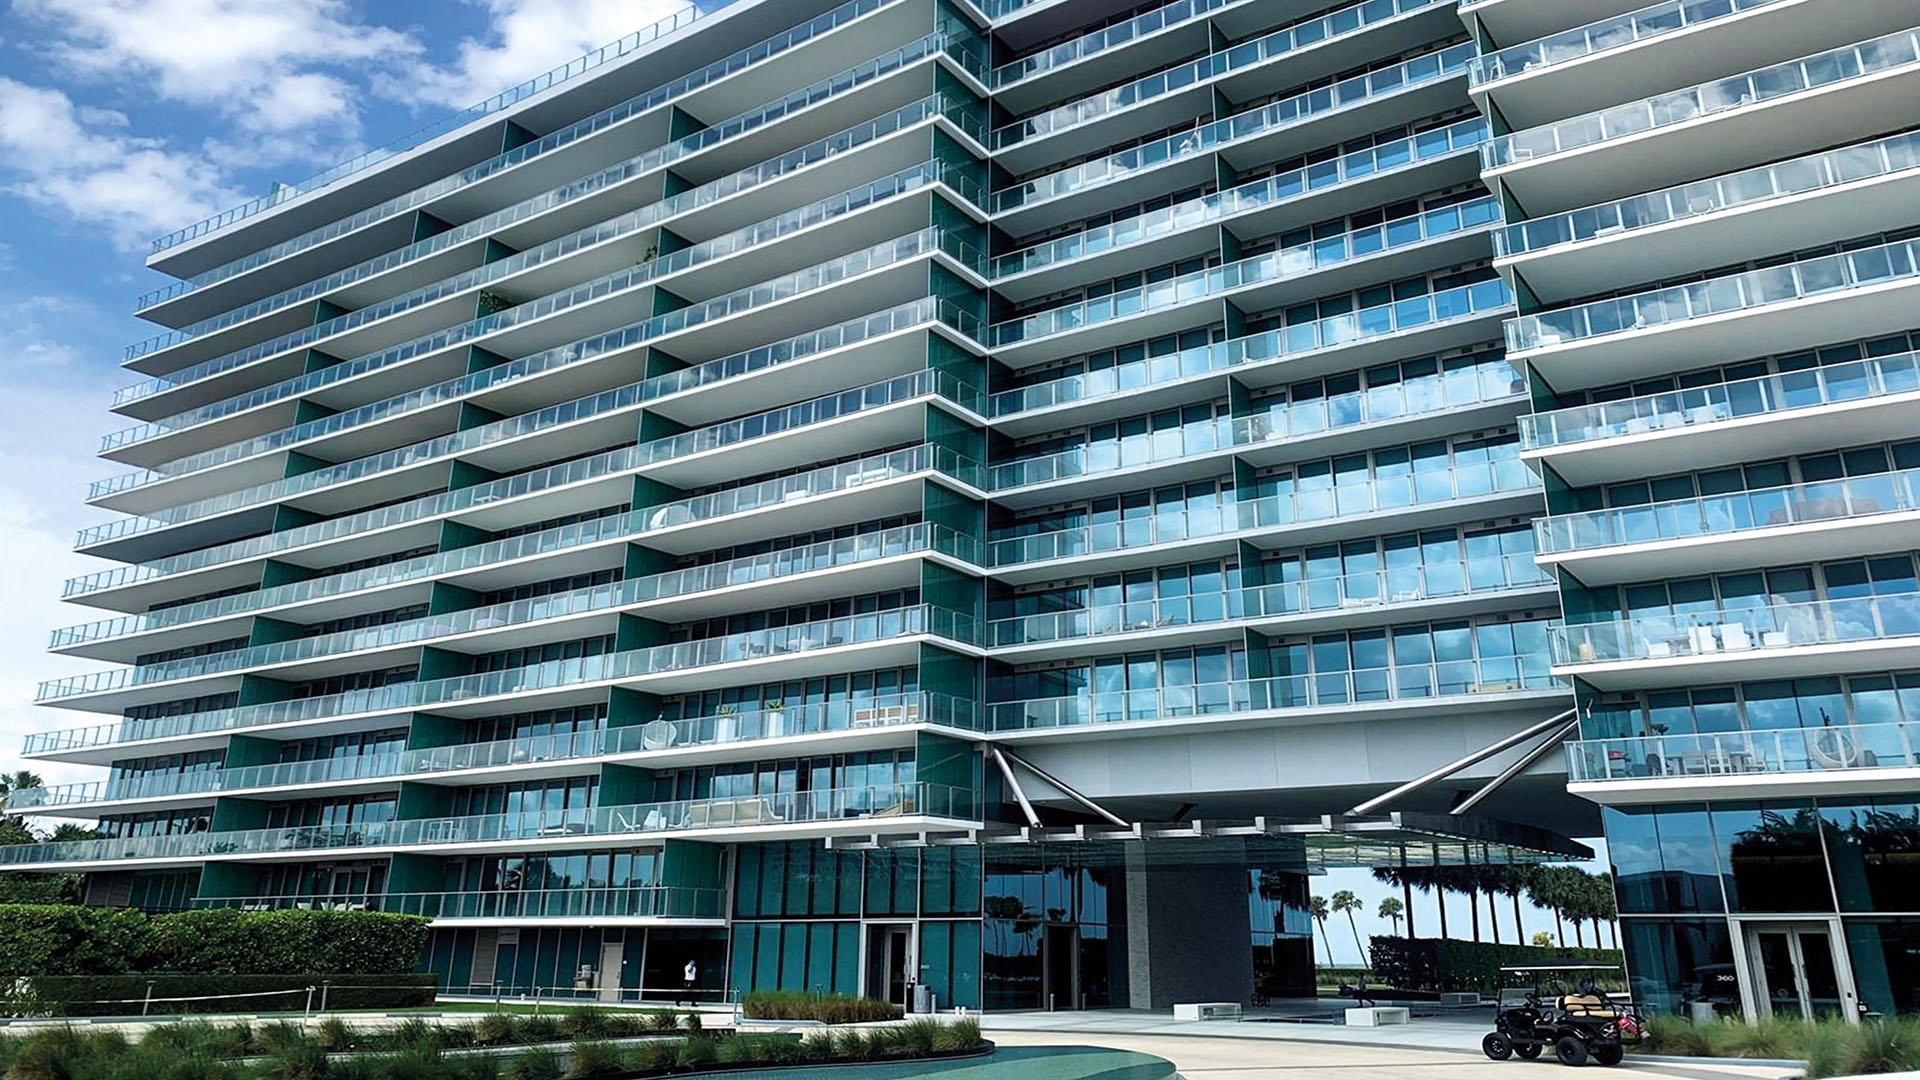
For buyers considering Oceana Key Biscayne, start with the residence’s actual assessment and the association’s current documents-not an assumed island-wide cost profile. Apply that discipline to every property on the shortlist.
Association budgets generally encompass building insurance, payroll, common-area utilities, amenity operations, management, maintenance, and reserve contributions. These categories serve different purposes and should remain distinct in a buyer’s model.
Build three separate layers:
Association charges: Identify the operating component and the reserve contribution within the regular assessment.
Direct owner expenses: Add property taxes, in-unit electricity, and personal insurance costs not included in association charges.
Additional capital exposure: Track disclosed special assessments and pending projects separately, including their payment timing.
Do not count reserve contributions twice if they are already included in the quoted monthly charge. Likewise, do not treat a special assessment as a permanent operating expense. Its cash requirement matters, but so does its duration.
The objective is a clear annual carrying-cost estimate, accompanied by a separate schedule of additional commitments.
Read payroll through the services the building promises to deliver. Security, concierge, valet, front-desk, pool, and beach services can make staffing costs sensitive to coverage and service intensity-not simply the number of residences.
Ask management to explain the staffing assumptions behind the budget. Which positions are included? What hours are covered? Are contracted services shown elsewhere? Seek clarification on wage changes, benefits, overtime, and contract renewals where applicable, rather than applying one inflation percentage to the entire staffing line.
Low density does not guarantee lower costs. Fixed staffing and amenity expenses can cost more per residence when fewer owners share them.
If the search extends to Coconut Grove and Park Grove Coconut Grove, compare documented service commitments before comparing monthly charges. The exercise should establish what each budget funds, without assuming identical staffing models or cost allocations.
Utility comparisons begin with scope. An association budget can include water, sewer, trash, bulk cable or internet, common-area air conditioning, lighting, and elevator power. In-unit electricity generally remains a separate owner expense. Confirm that boundary for the particular residence.
Then ask for the assumptions behind each material line. Distinguish consumption from pricing: an electricity budget should not be read in the same way as a contracted bulk-internet charge. Request recent actual expenses, the current budget, and explanations for material differences.
Do not assign a generic 2026 escalation rate to utilities or service contracts. Use the building’s available bills, renewal terms, and management explanations to establish a working assumption. Where future pricing remains unsettled, label the estimate as provisional and test a higher-cost scenario without presenting it as a market forecast.
Association master insurance, condominium-unit coverage-commonly called HO-6-and single-family homeowners insurance represent different exposures. Historical rate changes for one are not renewal guidance for another. Nor should a historical limit applying to certain policies be treated as a universal ceiling on association insurance increases.
For the association, request insurance summaries and renewal history. Ask the insurance professional to explain premiums, coverage, deductibles, and any material changes relevant to the buyer’s exposure. A premium comparison is incomplete without a comparison of terms.
Obtain a separate quotation for the residence’s personal coverage. Do not substitute a historical county average or a proposed rate increase for that quotation.
A buyer also considering Bal Harbour and Oceana Bal Harbour should maintain this distinction across the shortlist. Neither location nor project name provides a reliable insurance assumption without the relevant policy information.
Reserve contributions require their own analysis because several distinct forces can raise them. Florida’s post-Surfside legislation introduced Structural Integrity Reserve Studies, or SIRS, for many condominium buildings with three or more stories. Buyers should have qualified advisers confirm the rules and exceptions applicable to the particular association in 2026.
A reserve increase is not necessarily an inflation increase. Keep three questions separate:
Funding shortfall: Has the association historically waived or underfunded structural reserves?
Replacement costs: Have estimates for future projects changed?
Project timing: When is the work expected, and how does the funding schedule address it?
Catch-up contributions address money not accumulated previously. Replacement-cost inflation changes the estimated price of future work. Combining the two into a single escalation assumption obscures why contributions are rising.
The cost of commissioning a reserve study is also distinct from the capital funding it identifies. Neither the study’s existence nor a higher regular contribution, on its own, establishes that every anticipated project is fully funded.
Request the operating budget, financial statements, reserve study and funding schedules, insurance summaries and renewal history, meeting minutes, and disclosures of pending assessments or capital projects. Read them together: the budget identifies planned spending; the other documents help explain obligations and uncertainty.
Build a documented base case using the adopted charges and disclosed commitments. Then prepare a clearly labeled sensitivity case for unresolved renewals or project estimates. Adjust the relevant line rather than inflating every category equally.
For each assumption, record its basis, expected review date, and effect on the residence’s annual cash requirement. Ask management to clarify how association-level changes translate into that unit’s charges. Do not simply divide the total by the residence count without checking the allocation.
The strongest budget review does not seek a promise that costs will remain unchanged. It seeks a coherent explanation of what is funded, what may change, and what additional owner funding could be required. Inadequate existing reserves can still leave an association needing special assessments for major structural or capital projects.
For a luxury buyer, that clarity belongs beside the floor plan and the view. Favor a carrying-cost model that keeps daily operations, personal expenses, reserve funding, and separate capital commitments distinct. A transparent explanation of higher charges can be more useful than an attractive monthly figure with unresolved obligations.
For a considered approach to your South Florida residential search, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationIt generally includes building insurance, payroll, common-area utilities, amenities, management, maintenance, and reserve contributions. Confirm the exact inclusions for the building.
Property taxes, in-unit electricity, and personal insurance generally require separate allowances. Keep disclosed special assessments on a separate payment schedule.
No. Fixed staffing, amenity, maintenance, and insurance expenses can produce higher costs for each residence when shared among fewer owners.
Review staffing positions, coverage hours, service commitments, and applicable compensation or contract changes. Residence count alone does not explain staffing costs.
No. Associations may cover water, sewer, trash, bulk connectivity, and common-area energy, while in-unit electricity generally remains separate.
No. Single-family homeowners coverage, HO-6 unit coverage, and association master policies are different products and should be evaluated separately.
A SIRS addresses structural reserve needs within Florida’s post-Surfside framework for many condominium buildings with three or more stories. Confirm the applicable 2026 requirements and exceptions with qualified advisers.
Catch-up funding addresses a previous funding shortfall. Replacement-cost inflation changes the estimated future cost of the work itself.
Yes. Inadequate accumulated reserves can still leave an association needing additional owner funding for major structural or capital projects.
Request the operating budget, financial statements, reserve study and funding schedules, insurance summaries and renewal history, meeting minutes, and disclosures of pending assessments or capital projects.