For Zurich-based buyers considering Coconut Grove, the ownership decision extends beyond the deed. Personal title, trusts, LLCs, and foreign holding companies offer different balances of simplicity, liability protection, succession control, and cross-border tax complexity.
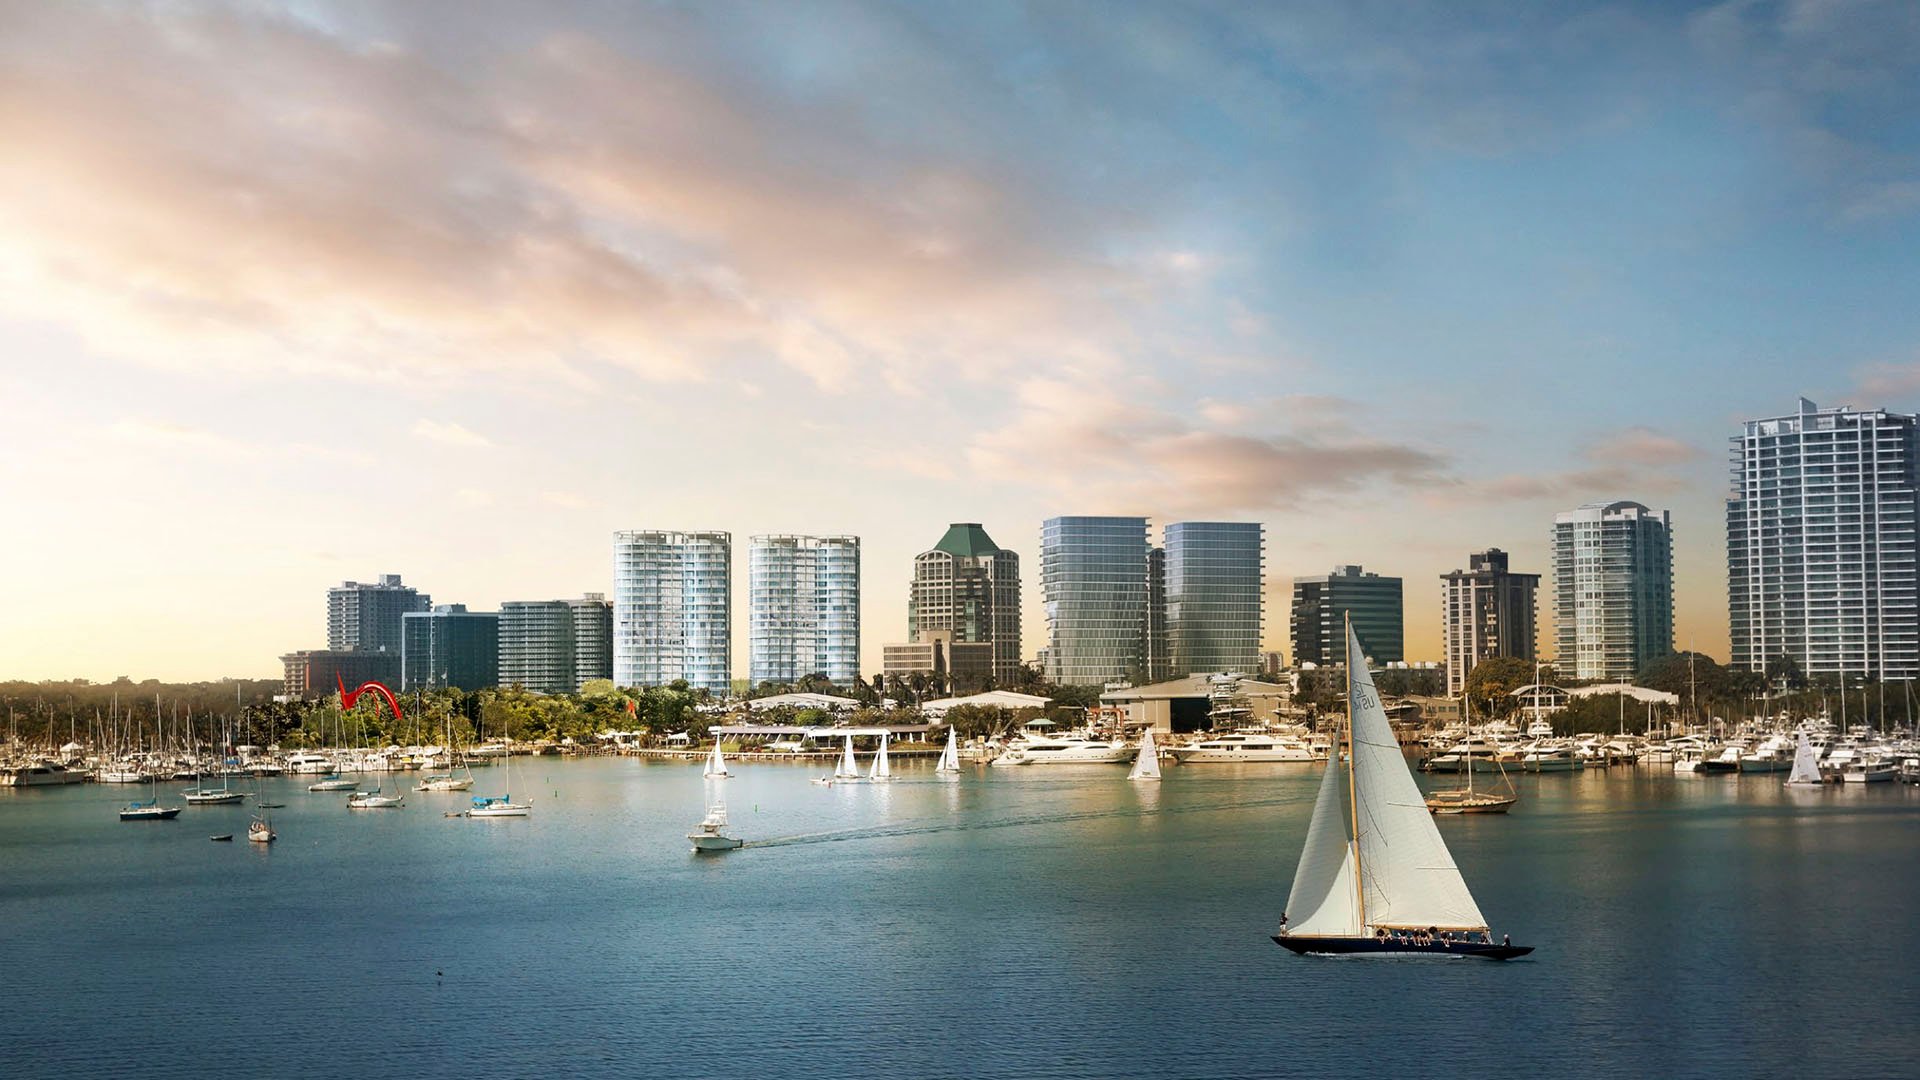
For a Zurich-based buyer considering Coconut Grove, choosing the residence and choosing its legal owner are distinct decisions. The first concerns how a home will serve the family. The second determines how simplicity, liability, succession, and tax obligations will be balanced over time. A well-planned purchase should address both.
Whether the search begins with Four Seasons Residences Coconut Grove or another residence, the ownership analysis starts with the buyer’s circumstances, not the project’s identity. A Zurich address does not establish a uniform U.S. tax status, particularly when the purchase accompanies relocation. Advisers should establish that status before comparing structures.
The relevant distinctions concern U.S. real estate and Florida ownership planning, not a separate Coconut Grove ownership regime. No single structure should be presumed preferable for Zurich buyers. The central question is which responsibilities the family wants to simplify and which complexities it is prepared to accept.
Buying in an individual’s name avoids entity-formation costs and ongoing entity administration. For a buyer who values straightforward ownership, that is a meaningful advantage: there is no company to maintain simply to hold the residence.
The tradeoff is equally direct. Personal title provides no entity-based liability shield. Direct ownership of U.S. real estate can also expose a foreign owner’s estate to U.S. estate tax. That calls for a buyer-specific review before purchase, not a blanket assumption that the entire property value will be taxed.
Consider a family evaluating Park Grove Coconut Grove for its own use. Even if ownership seems uncomplicated, inheritance may not be. Who should receive the interest, how succession should unfold, and what estate-tax exposure may arise deserve attention alongside the contract.
Personal ownership is a choice for simplicity, not an exemption from planning. It remains an option to assess, rather than one to dismiss automatically because the residence is expensive.
A U.S. limited liability company can help separate personal assets from claims associated with the property. It also holds title in its own name rather than the individual buyer’s name, reducing direct visibility in property records. These are separate benefits, and neither should be overstated.
An LLC does not guarantee anonymity. Buyers seeking discretion should distinguish the name appearing on the deed from any applicable disclosure obligations. Current requirements belong in the legal review; a company should not be assumed to make its owner invisible.
Tax treatment requires the same precision. Depending on ownership and tax classification, an LLC can preserve income-tax treatment broadly similar to direct ownership. That does not mean LLC status creates a tax saving. Nor should a single-member U.S. LLC owned directly by a foreign individual be treated as automatically eliminating U.S. estate-tax exposure.
For a purchaser considering Opus Coconut Grove, the useful question is not simply whether to buy through an LLC. It is which specific problem the LLC would solve and which issues would still require a separate solution.
Trust planning becomes especially relevant when a home is intended to remain within a family. A trust can support probate avoidance and provide control over succession. Its purpose may be less about the immediate purchase than about continuity for heirs.
That benefit should not be confused with automatic estate-tax protection. A trust may protect against U.S. estate-tax exposure only if the necessary conditions are met. Merely placing a residence in a trust does not establish that result, and the trust label alone says little about its suitability.
Trusts and LLCs need not be competing choices. Trust planning addresses succession and potentially privacy; an LLC addresses property-related liability. They can be combined where coordinated advice supports the arrangement. Each layer should serve a defined purpose, rather than add complexity for its own sake.
Florida land trusts are another possible structure, but they still require coordinated tax and estate planning. For a Zurich-based family, any proposed trust also requires home-country advice. No particular Swiss tax or inheritance outcome should be presumed from its U.S. treatment.
A foreign corporate holding arrangement offers a different planning possibility. One structure places a foreign holding company between the individual and a U.S. LLC that holds the residence. Properly structured, a foreign corporate arrangement may reduce U.S. estate-tax exposure.
That qualification matters. The arrangement does not promise estate-tax immunity, and it introduces legal, tax, and administrative complexity across jurisdictions. The evaluation should weigh the potential estate-planning benefit against the responsibilities of maintaining the structure and its consequences during ownership and at sale.
Entity terminology also matters. Nonresident-alien individuals cannot be S-corporation shareholders, making that option unsuitable for many foreign buyers. A recommendation to use a company should identify the actual ownership chain and tax treatment, rather than rely on a generic corporate label.
An ownership structure should be assessed across purchase, holding, succession, and exit. FIRPTA affects withholding when foreign owners sell U.S. real estate. Personal, corporate, LLC, and trust arrangements can change the seller’s U.S. tax treatment and how sale-related withholding and filings are handled.
A family considering Arbor Coconut Grove may initially focus on years of personal enjoyment. A future sale nevertheless deserves a place in the initial discussion. Ask advisers to explain how the proposed arrangement would operate at exit, not only what it accomplishes on the closing date.
A structure chosen solely for discretion or inheritance can leave other consequences insufficiently examined. A more useful comparison covers the entire ownership period, giving administrative obligations the same attention as potential protections.
Before selecting the purchaser named in the transaction, coordinate U.S. real-estate counsel, U.S. tax advisers, and Swiss advisers. Establish the buyer’s status, intended use, succession priorities, privacy expectations, and tolerance for administration. Then compare personal title, an LLC, a trust, and any proposed corporate arrangement against those priorities.
Resolve the decision early. Later restructuring can create complications involving financing, transfers, and tax treatment. The objective is not the greatest number of protective layers, but a coherent arrangement whose advantages and limitations the family understands. This is a planning framework, not individualized legal or tax advice.
For a discreet conversation about your Coconut Grove residential search, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationForeign buyers can hold Miami residential property in their own names. Personal title avoids entity-formation costs and administration but provides no entity-based liability shield.
No. Zurich-based buyers should have their individual U.S. tax status assessed, especially if the purchase accompanies relocation.
Direct ownership of U.S. real estate can expose a foreign owner’s estate to U.S. estate tax. The consequences require a buyer-specific assessment before purchase.
No. An LLC places its own name on title rather than the individual buyer’s name, reducing direct visibility in property records without guaranteeing anonymity.
A single-member U.S. LLC owned directly by a foreign individual should not be treated as automatically eliminating U.S. estate-tax exposure.
A trust can support probate avoidance and control over succession. Any estate-tax protection depends on meeting the necessary conditions, not merely using a trust.
Yes. Trust planning can address succession and potentially privacy, while an LLC can address property-related liability; coordinated planning may combine them.
A properly structured foreign corporate holding arrangement may reduce U.S. estate-tax exposure. It also adds cross-border legal, tax, and administrative complexity.
FIRPTA affects withholding when foreign owners sell U.S. real estate. The ownership arrangement can influence seller tax treatment and sale-related withholding and filings.
Resolve it before closing with coordinated U.S. legal, U.S. tax, and home-country advice. Early planning can help avoid later complications involving financing, transfers, and tax treatment.