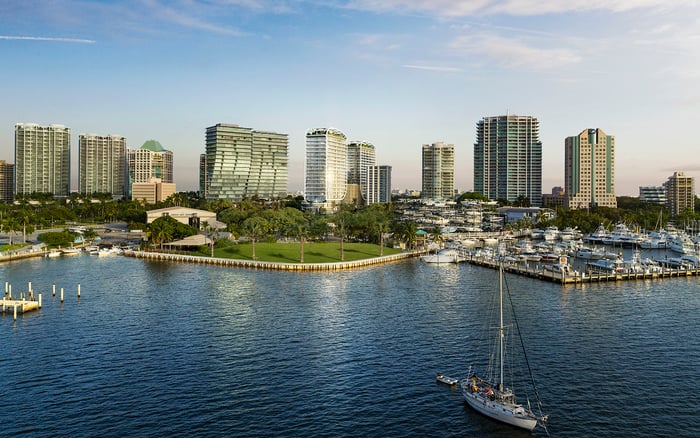
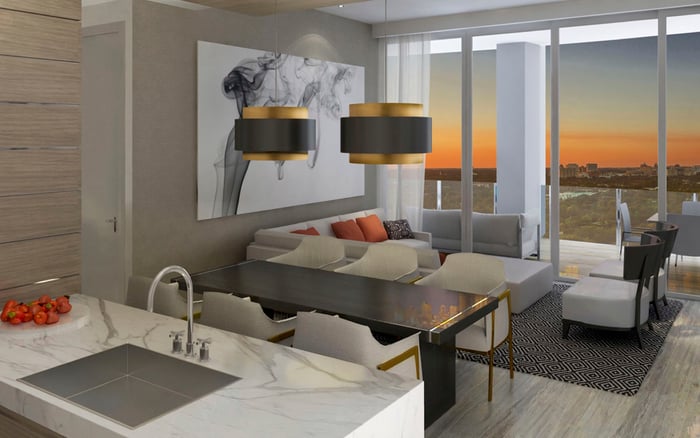
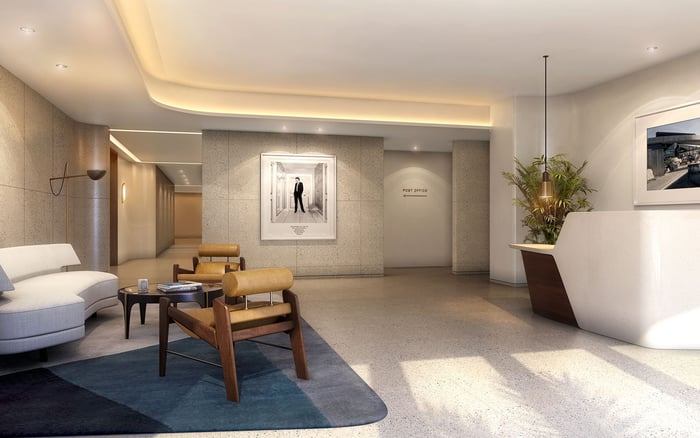
A Coconut Grove purchase should fit the household balance sheet as comfortably as the lifestyle. Separate closing funds, operating reserves and long-term investments to preserve flexibility before and after the keys change hands.
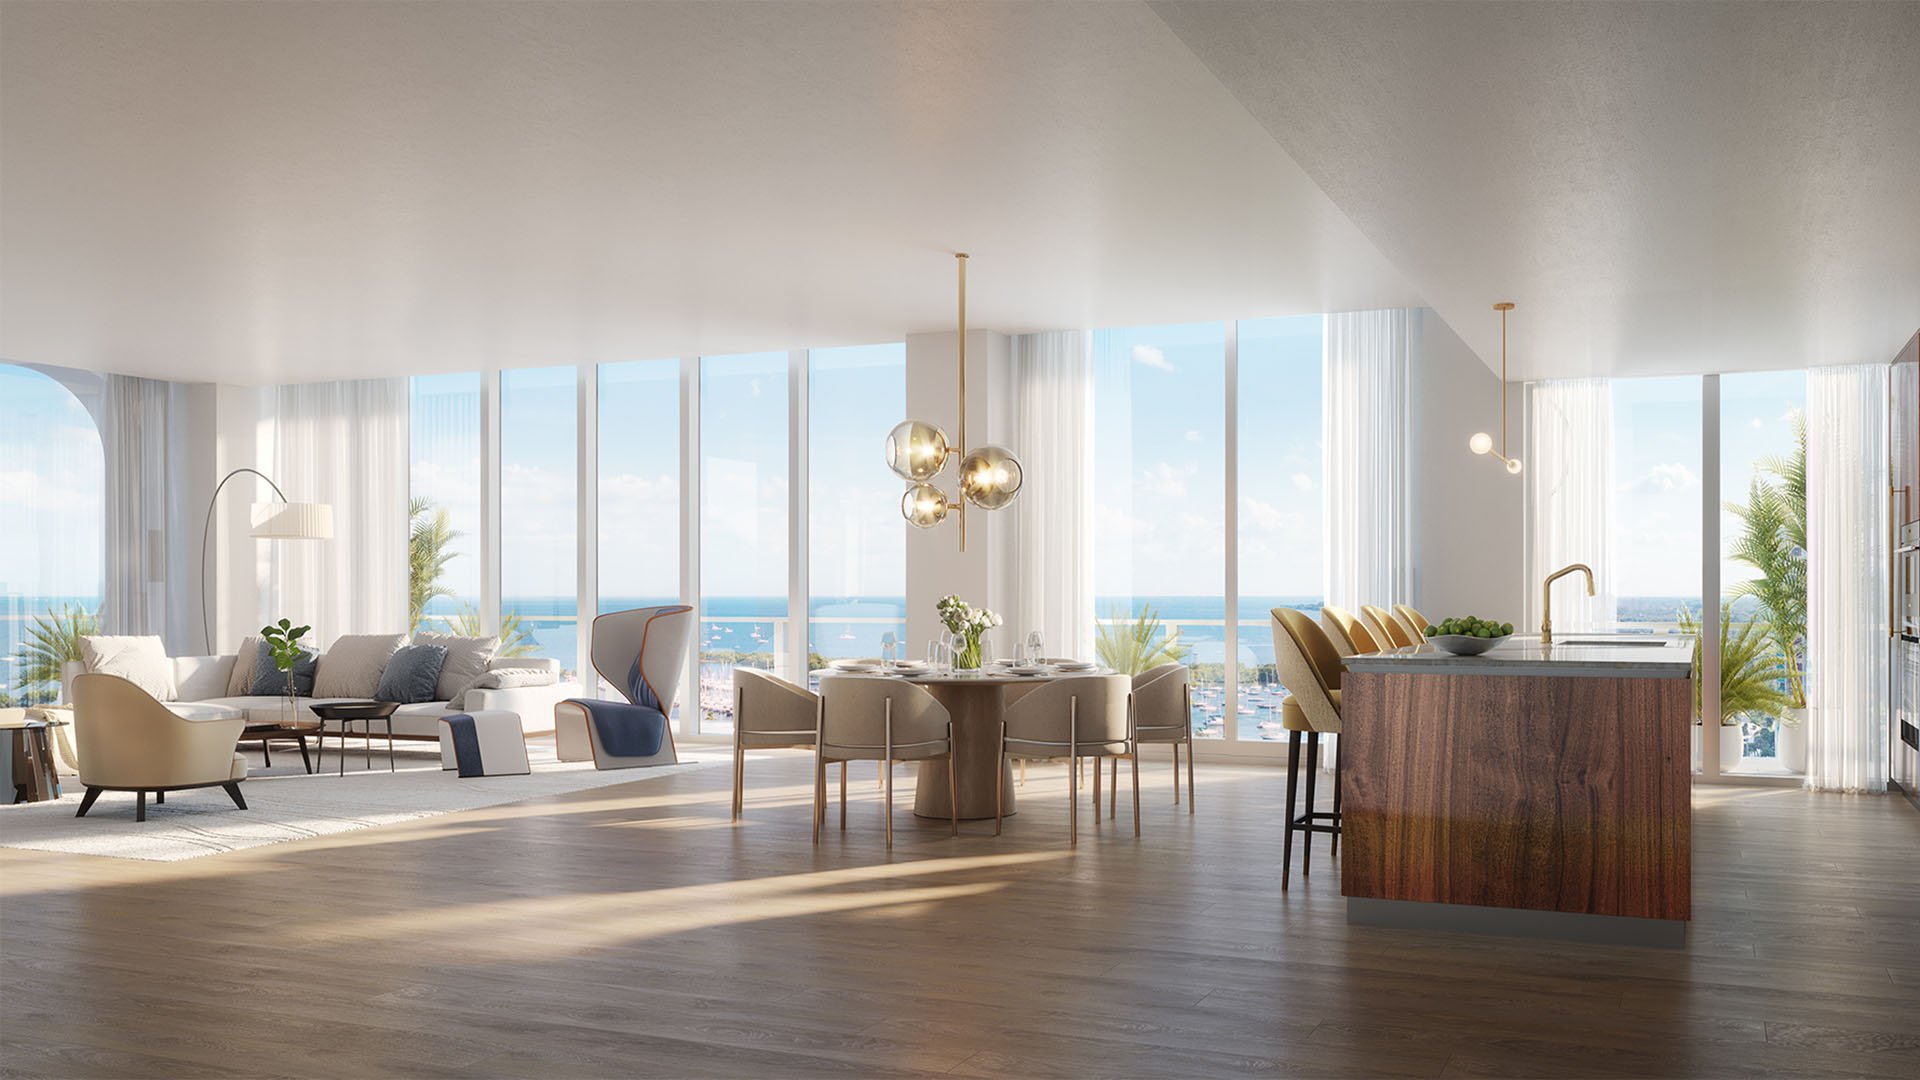
For a Geneva-based household considering Coconut Grove, the central question is not simply whether the residence is affordable. It is whether the purchase leaves enough accessible capital to sustain life in both locations, meet existing commitments and preserve investment choices. A beautiful home should not make an otherwise sound portfolio fragile.
The residence belongs in a household balance-sheet review even when it sits outside the investment portfolio. That distinction matters: a percentage calculated against investable assets describes a different exposure from one calculated against total wealth, including personal property.
A buyer considering Four Seasons Residences Coconut Grove can begin with two separate decisions: whether the home suits the intended life, and whether the funding plan leaves the remaining balance sheet resilient. Neither decision should substitute for the other.
A practical framework separates closing liquidity, ongoing operating reserves and long-term investment capital. These are planning categories, not regulatory requirements or mandatory account structures.
Closing liquidity funds the acquisition. Operating reserves support life after purchase, including household spending, ownership obligations and taxes. Long-term capital remains invested for objectives that can tolerate uncertainty and, where appropriate, limited access.
The discipline is to avoid counting the same funds twice. Money earmarked for closing should not also serve as the household's spending cushion. Liquid assets supporting private-investment commitments should not be treated as entirely available for discretionary purchases.
Before reallocating assets, ask the advisory team to prepare a single schedule showing each pool's purpose, amount, currency, expected use and funding source. Identify which obligations are confirmed and which still require estimates. The schedule should distinguish accessible wealth from capital already committed.
Closing funds require a defined execution plan, not an assumption that portfolio liquidity will be available when needed. Ask the transaction team to confirm the required amounts and payment dates, then have the investment and banking teams identify how those obligations will be funded.
For a household whose resources include Swiss francs, separate the investment decision from the currency and transfer decisions. Confirm conversion arrangements, transfer procedures and availability directly with the institutions involved. Do not build the purchase around an assumed CHF/USD rate or a generic cross-border transfer timetable.
Whether the shortlist includes Park Grove Coconut Grove or another residence, compare the actual funding schedules for the contemplated transactions. A property's appeal does not establish when cash must be available.
Ask advisers to examine the consequences of proposed asset sales before execution, including tax questions requiring Swiss and U.S. advice. Closing-cost estimates, ownership structures and cross-border tax treatment require transaction-specific professional review, not a portfolio allocation rule.
After closing, reserve capital should reflect the household's continuing obligations, not merely what remains in the account. Liquidity supports daily spending, tax payments and rebalancing. It also helps determine how long the household can tolerate illiquid investments.
Ask advisers to size reserves around expected spending, payment dates and other accessible resources rather than a fixed number of years. Match reserve currencies to the obligations they will fund. Liquid investments are not synonymous with cash, and their suitability depends on the intended use.
For a prospective purchase at Opus Coconut Grove, request property-specific ownership information before settling the reserve budget. Keep the home's expected outgoings distinct from broader household spending, then combine them without double-counting.
Separate predictable spending from discretionary plans as well. A reserve intended to preserve financial continuity should not quietly become the budget for every post-purchase choice. Agree in advance which expenditures can be deferred if cash demands rise.
The purchase changes the household balance sheet even if the investment account's stated allocation remains unchanged. Review the residence alongside existing property, private investments and liquid holdings, keeping the categories clearly labeled. A home used personally is not interchangeable with a private real-estate fund.
Begin the illiquidity review with capital the household can afford to leave inaccessible, and for how long. Assess proposed commitments against cash-flow needs and risk tolerance rather than treating a percentage allocation as a universal target.
The better question is how much long-term capital remains after accounting for the acquisition, spending reserves and existing commitments. If that capacity is modest, postponing additional private investments may make more sense than pursuing a percentage detached from household needs.
Unfunded private-investment commitments deserve their own line in the plan. Future capital calls compete with other cash needs. Monitor them against liquid assets rather than overlooking them because the money has not yet been requested.
Before committing to The Well Coconut Grove, a buyer with private-market exposure can ask advisers to test a demanding combination: the acquisition completes, household spending continues and capital calls arrive while markets are volatile. This is a planning scenario, not a forecast.
The exercise should identify which resources fund each obligation and which discretionary decisions would be delayed. Its purpose is to expose competing claims on liquidity before they become urgent.
Once the purchase is complete, replace estimates with actual figures and reconcile the remaining liquid assets. Revisit the household allocation, outstanding commitments and reserve policy together. Closing is not the end of the financial work.
Agree with advisers when to review the plan and which changes should prompt another discussion. Changes in spending, new commitments and altered family objectives are useful considerations; avoid applying a performance-linked rebalancing schedule mechanically. Keep diversification and estate planning within that conversation.
The objective is neither maximum cash nor maximum deployment. It is a residence that enriches daily life while leaving the household free to make its next decision deliberately.
Explore Coconut Grove residences with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationInclude it in the household balance-sheet review, even if it remains outside the investment portfolio. Keep percentages based on investable assets separate from those based on total wealth.
Separate funds for closing, ongoing operating reserves and long-term investments. These are practical planning categories, not regulatory requirements.
Use the amounts and payment dates confirmed for the specific transaction. A general investment allocation cannot establish the required closing funds.
Base reserves on expected household spending, ownership obligations, taxes and other accessible resources. Ask advisers to assess payment timing rather than rely on a fixed number of years.
Discuss reserve currencies with advisers in relation to the obligations they will fund. Do not assume every household obligation requires U.S. dollars.
Identify how long the household can afford to leave capital inaccessible. Assess funds needed for closing or foreseeable spending separately.
No; assess commitments against household cash-flow needs, risk tolerance and remaining liquidity. A percentage target should not replace that review.
Liquid investments are not synonymous with cash. Assess their suitability against the timing and purpose of the planned expenditure.
Future capital calls compete with spending, taxes and other cash needs. Monitor those commitments against the liquid assets remaining after the acquisition.
Reconcile actual post-closing balances and agree a review policy with advisers. Changes in spending, commitments or family objectives should prompt another discussion.