For collectors balancing art acquisitions and condominium ownership, disciplined documentation separates personal securities-backed borrowing from association finance, connects reserve plans to budgets, and preserves the owner-notice record.
For an art collector, a South Florida residence sits within a broader financial picture: acquisition commitments, investment collateral, and the continuing cost of ownership. A securities-backed line adds another set of terms. The essential distinction is between the collector’s personal borrowing and the condominium association’s financing.
A personal credit facility is not an association loan. A collector borrowing to acquire art or pay an assessment should maintain a private financing file and separately review the association’s reserve study, budget, assessment approvals, and notices. The framework addressed here establishes no special condominium compliance regime for art collectors.
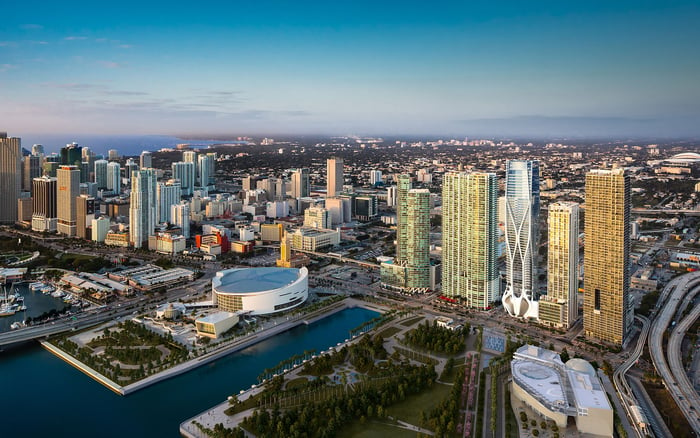
For a Miami Beach buyer considering Faena House Miami Beach, that distinction is a starting point for diligence, not a statement about the property’s finances. A personal borrowing decision does not itself trigger an association reserve-study update.
Under Florida’s 2025 statutory framework, qualifying residential condominium buildings of three or more habitable stories require a Structural Integrity Reserve Study, or SIRS, at least every 10 years. The study evaluates required components, reserve balances, projected repair or replacement costs, and future funding needs.
Required components include roofs, load-bearing walls, foundations, fireproofing and fire-protection systems, plumbing, electrical systems, waterproofing and exterior painting, windows, and exterior doors. For an owner, the study is both a financial planning document and a record of building needs.
Existing unit-owner-controlled associations generally faced an initial deadline of December 31, 2025, subject to statutory exceptions. Associations required to complete a milestone inspection by December 31, 2026, may coordinate the initial SIRS with that inspection, provided both are completed by that date. Do not assume this coordination option applies to every building.
Request the latest study, its receipt date, subsequent updates, and the budget built around it. Retain earlier versions so changes in assumptions remain visible.
The financing-related update triggers outlined here are framed as of January 2026 and should be confirmed with condominium counsel under the law applicable when the association acts. They are distinct from the 10-year study interval and should not be read as a blanket statement about later legislative changes.
Within that framing, a SIRS completed before approval of an association special assessment, line of credit, or loan requires an update to reflect the financing method and its effect on reserves and regular assessments. An update is also required before budget adoption when actual funding no longer matches the latest study’s funding plan.
As a recommended documentation practice, keep the study date, approval date, financing amount, payment schedule, and revised funding assumptions together. Ask whether the update reflects the approved arrangement rather than an earlier proposal.
When reviewing a Surfside residence such as The Surf Club Four Seasons Surfside, frame these as requests for association-specific records. The project reference implies neither borrowing nor an assessment at that building.
For the collector’s personal facility, retain the signed credit agreement, amendments, commitment and draw amounts, pricing, maturity, pledged collateral, covenants, intended use of proceeds, and repayment source. Keep art-purchase records separate, cross-referencing the relevant draw where appropriate.
Pay particular attention to collateral-call and liquidation provisions. Declining securities values can trigger demands for additional collateral or forced investment sales, with possible tax consequences and losses magnified by market volatility. Make those terms easy to locate before a payment deadline arrives.
For association borrowing, request the relevant approval records and financing terms: commitment, draws, interest, maturity, covenants, repayment source, and intended expenditure. Retain the assessment payment schedule alongside them where relevant.
These are recommended records, not a universal statutory checklist. Their purpose is to establish who owes the money, what secures it, and which cash flows repay it. Keep personal collateral exposure distinct from the association’s reserve position.
A useful reconciliation places original and revised SIRS assumptions alongside actual funding. It should show opening reserve balances, regular reserve contributions, special-assessment collections, financing proceeds, repair expenditures, interest, debt service, and projected remaining funding needs.
Distinguish amounts approved from amounts collected or drawn. An approved credit commitment does not mean the full amount has funded repairs. The reconciliation should also explain how repayment obligations fit the budget, rather than presenting loan proceeds without their associated costs.
For a Brickell purchaser evaluating Una Residences Brickell, the question is not simply whether reserves exist, but whether the current budget and latest study describe the same funding plan. This is a diligence principle, not a finding about that association.
As a recommended audit trail, link draws and expenditures to contracts, invoices, projects, and relevant SIRS components. A dated reconciliation helps the owner and advisers follow each change without reconstructing it from separate documents.
The reserve framework includes a limited allowance to pause or reduce funding for no more than two consecutive annual budgets when necessary to fund milestone-inspection repairs, subject to statutory conditions. A milestone inspection identifying no repairs does not authorize a pause or reduction on that basis.
Where a pause is involved, request its documented basis, affected budgets, repair funding arrangements, and planned resumption of contributions. Treat resumption as another point at which to review the reserve plan with counsel and the study professional.
For the collector, a temporarily lower contribution should not become the unquestioned basis for future ownership costs. Include the planned return to contributions in the personal liquidity calendar alongside borrowing costs and assessment installments.
Keep three notice events distinct. Within 45 days after receiving the SIRS, the association must distribute it to owners or notify them of its availability for inspection and copying upon written request.
Notice of a meeting considering a special assessment must reach the required mailing, delivery, or electronic-transmission stage at least 14 days before the meeting. It must state that assessments will be considered and include the estimated cost and a description of the purpose.
An approved special assessment also requires written notice to each owner identifying its specific purpose or purposes. As a recommended recordkeeping practice, retain the meeting notice, approval minutes, post-approval notice, payment schedule, and evidence of delivery or transmission.
Before committing capital, assemble the latest study, reconciliation, financing records, and notice chronology for review by the appropriate legal, tax, and investment advisers. The objective is clarity: documented building obligations and a personal funding plan that anticipates collateral pressure rather than relying solely on available credit.
Explore South Florida residences with a more deliberate ownership perspective through MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationThe framework discussed here does not establish one. The collector’s personal borrowing and art-purchase records should remain separate from association reserve and financing records.
A personal draw does not itself establish an association update trigger. The financing-related triggers concern changes to the association’s funding arrangements.
Under the 2025 statutory framework, qualifying Florida residential condominium buildings of three or more habitable stories require a SIRS at least every 10 years. Financing-related updates are a separate consideration.
January 2026 legal guidance calls for updates when a study predates approved association financing or actual funding diverges from the study’s plan before budget adoption. Counsel should confirm the applicable requirements.
Recommended records include the agreement, draw amounts, pricing, maturity, collateral terms, covenants, intended use, and repayment source. Keep related art-purchase records separately and cross-reference relevant draws.
Show original and revised study assumptions, reserve balances, contributions, assessment collections, financing proceeds, repair spending, interest, debt service, and remaining funding needs. Distinguish approved commitments from funds actually received.
No. The limited allowance concerns necessary milestone-inspection repairs, is subject to statutory conditions, and covers no more than two consecutive annual budgets; an inspection identifying no repairs does not authorize it on that basis.
Within 45 days after the association receives the SIRS, it must distribute it or notify owners that it is available for inspection and copying upon written request.
Retain the meeting notice sent at least 14 days in advance, including estimated cost and purpose, and the written notice identifying the approved assessment’s specific purposes. Keeping approval minutes and delivery evidence is also recommended.
A decline in pledged securities can trigger a collateral call or forced liquidation. Investment sales may create tax consequences, and market volatility can magnify losses.