
For family-office buyers, an oceanfront condominium deserves operational diligence as exacting as its financial review. Written humidity controls, moisture-response procedures, absence-care agreements, and emergency authority should be understood before closing.
For a family office considering an oceanfront condominium in Fort Lauderdale, the decisive questions extend beyond the terrace, arrival experience, and interior specifications. A residence also warrants scrutiny for what happens when it is empty: how moisture is detected, who can enter, who authorizes mitigation, and how the owner learns something has gone wrong.
The purchase file should include an operating dossier alongside the financial and legal documents. For a Fort Lauderdale Beach shortlist that includes Auberge Beach Residences & Spa Fort Lauderdale, apply the same evidence-based questions to every candidate. Neither a residential brand nor an amenity description establishes a particular humidity-control or absence-care service.
The objective is straightforward: turn reassuring language into written responsibilities, measurable triggers, and a clear chain of authority. These are buyer diligence requests, not assertions about services at any named property.
A cool room is not proof of adequate moisture control. Humid air meeting cold surfaces can create condensation and concealed moisture without an obvious leak. An immaculate showing is no substitute for a review of summer operating practices.
A practical summer reference is 45-55% indoor relative humidity; sustained readings above 60% favor mold growth. Treat those figures as nonstatutory guidance, not a legally mandated condominium standard or a guarantee against mold. Ask the building’s technical team to explain the appropriate operating approach for the residence.
Request written HVAC settings for occupied and vacant periods, dehumidification guidance, and an explanation of how humidity is managed within units and common areas. Confirm guidance on leaving air conditioning running during absences; do not assume an empty residence can remain unconditioned.
Monitoring needs an accountable recipient. Ask whether readings are logged, who reviews them, what threshold triggers action, and how elevated readings are handled when the owner is overseas. A sensor without a defined response is not a complete care arrangement.
Review window and door sealing, roof and drainage inspections, recurring leaks, and repairs following major storms. Request supporting maintenance records rather than relying on a general assurance that the building is well maintained.
The unit-level file should include available mold complaints, moisture investigations, remediation work, and testing. Where the history or inspection warrants it, consider an independent moisture-and-mold assessment as a purchase contingency. Have advisers distinguish an unresolved moisture source from a documented event whose cause was corrected.
Next, review the declaration and maintenance provisions with condominium counsel. Identify where association responsibility ends and owner responsibility begins for affected building components and interior finishes. Responsibility for stopping a leak, restoring cabinetry, and paying for the work does not necessarily fall to the same party.
For a family office, translate this allocation into an operational contact sheet: who receives notice, who approves work, and which questions require counsel or insurance review.
Ask management to describe the sequence from discovery through assessment, emergency drying, remediation, and verification. The protocol should identify decision-makers and the response times the association actually commits to, including after-hours arrangements. Do not infer a universal service standard from a staffed lobby.
When reviewing Four Seasons Hotel & Private Residences Fort Lauderdale, distinguish the services described for residents from any separately documented in-unit moisture response. Apply the same distinction to every comparison of branded and unbranded residences.
Request vendor licensing details, applicable remediation standards, containment procedures, and post-remediation verification requirements. The proposed scope should address the underlying leak, condensation, or HVAC problem-not merely the cleaning of visible growth.
Establish what can proceed before the principal is reached. Access authority, permission to shut off water, and authorization for emergency drying should be explicit, so the family office understands the response without having to improvise during an incident.
Keyholding is not the same as scheduled inspection. Confirm whether management provides both, whether post-storm checks are included, or whether an authorized third-party manager must be retained. Put the agreed scope and inspection frequency in writing.
An absence checklist should document A/C operation, humidity readings, visible leaks, musty odors, and whether windows and doors are closed. Request a consistent inspection record for the family-office representative to review, with exceptions escalated rather than buried in routine correspondence.
For an unattended unit, document who may enter, authorize water shutoff or drying, and notify the owner. Designate the family office’s primary and alternate contacts, and agree on how unresolved alerts move between them.
For buyers considering St. Regis® Residences Bahia Mar Fort Lauderdale, the useful question is not simply whether care is available, but which duties will be documented for the residence. A service expectation should become an agreement before it becomes a dependency.
For a Broward purchase, request the association’s building-specific hurricane-protection specifications and clarify approved systems and owner obligations. Florida’s condominium framework requires specifications that comply with the applicable building code. That alone does not establish that every existing window or shutter must be replaced to today’s new-construction standard.
Technical specifications are not an operational plan. Do not assume written preparedness procedures exist simply because hurricane protection is addressed in the governing framework.
Request the actual sequence for pre-storm preparation, evacuation, elevator shutdown, garage flood precautions, and post-storm inspection and repair. Confirm resident notification channels and how management coordinates evacuation and post-storm safety information with local emergency services.
Ask who communicates access restrictions and when an absence-care provider may inspect. Emergency powers do not replace an everyday leak-response procedure or a contractual inspection service.
Section 718.1265 provides conditional emergency powers, including emergency meetings, unsafe-area restrictions, and mitigation work, subject to declared-emergency and necessity limits. Under those conditions, an association may remove wet drywall, insulation, carpet, cabinetry, and other materials to mitigate mold or mildew, including items ordinarily maintained by owners.
The statute also permits special assessments and borrowing without an owner vote under specified conditions. Have counsel explain those limits and review the association’s financial capacity alongside its operational readiness.
Request current property, windstorm, and flood coverage, premium changes, and assessments associated with storm repairs or remediation. Before closing, resolve material gaps in the humidity plan, incident history, maintenance allocation, absence-care agreement, and emergency procedures. The goal is not a promise of zero risk, but an ownership arrangement with explicit responsibilities.
For a discreet conversation about your Fort Lauderdale oceanfront search, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationA practical summer reference is 45–55% relative humidity, with sustained readings above 60% considered mold-favorable. This is nonstatutory guidance, not a legally mandated condominium operating range.
Yes. Humid air meeting cold surfaces can cause condensation and concealed moisture even when no obvious leak is present.
It should specify summer and vacancy settings, dehumidification guidance, and how humidity is controlled in units and common areas. Ask who reviews readings and what triggers intervention.
Request available complaints, investigations, remediation work, testing, and documentation of repairs to underlying moisture sources. Consider an independent moisture-and-mold assessment as a purchase contingency.
Review the declaration and maintenance provisions with counsel to identify association and owner responsibilities for affected components and finishes. Do not assume all aspects of a repair belong to one party.
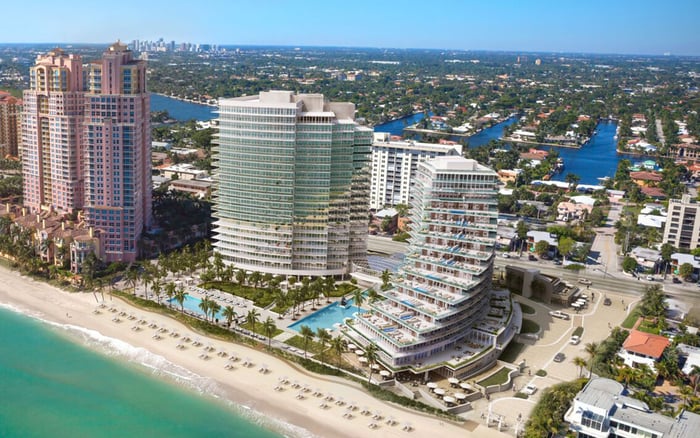
Request vendor licensing details, applicable standards, containment procedures, and post-remediation verification requirements. The scope should also correct the underlying leak, condensation, or HVAC problem.
Do not assume it does. Confirm scheduled inspections, post-storm checks, and emergency access in writing, including whether an authorized third party is needed.
It should document A/C operation, humidity, visible leaks, musty odors, and closed windows and doors. Exceptions should reach the designated owner or family-office contact.
No. Separately request procedures for preparation, evacuation, elevator shutdown, garage flood precautions, resident communications, and post-storm inspections.
Section 718.1265 permits special assessments and borrowing without an owner vote under specified emergency conditions. Counsel should review those limits alongside the association’s insurance and financial capacity.