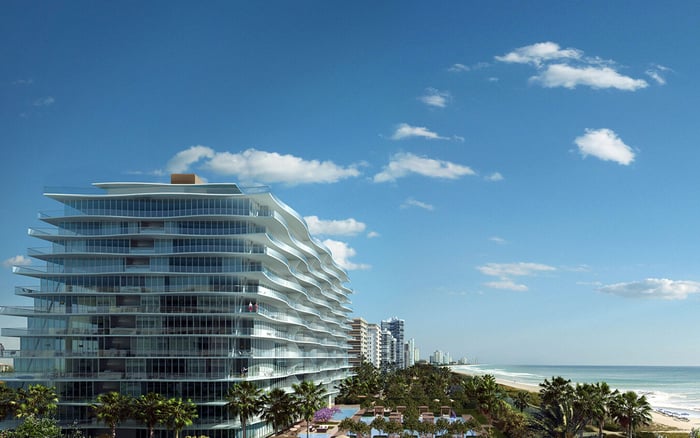
A funding-first buying brief for Surfside residences, focused on the financial documentation buyers should request before treating any property as a lower-exposure choice.
For a Surfside buyer, a beautifully resolved residence is only part of the acquisition decision. The ownership commitment deserves equal scrutiny. When the objective is lower exposure to special assessments, the question is not which address carries the most persuasive identity. It is which funding plan can withstand detailed review before a purchase becomes binding.
This is a funding-first buying brief, not a certification that any named residence has lower special-assessment exposure. A ranking on that basis should follow financial review, not precede it. Treat the names below as starting points for individual inquiries. Do not assume they share the same structure, funding position, or eligibility for a branded-residence comparison.
If The Surf Club Four Seasons Surfside is on your shortlist, begin by requesting the applicable association financial documents. Keep the lifestyle decision and the funding decision separate until each has been examined on its own terms.
A defensible top-five property selection needs evidence behind every position. Rather than assign financial superiority to an address without that foundation, use the following ordered review priorities. These are funding tests, not a ranking of residences or an assurance against future assessments.
1. Adopted funding commitments: distinguish approval from intention
Ask for the current adopted budget and the reserve contributions it authorizes. Distinguish approved spending from funding under discussion and changes that still require a decision. These categories are not interchangeable.
Favor an explanation that connects an identified obligation to an approved funding mechanism. Ask who approved it, when it takes effect, and whether the financial documents reflect that commitment. A verbal description should prompt a request for documentation, not conclude the review.
2. Reserve support: connect balances to anticipated needs
Request the relevant reserve study, its date, and the assumptions behind its recommendations. Ask your advisers to compare those recommendations with current balances and scheduled contributions. A reserve balance alone is not proof of adequacy.
The review should answer a practical question: what work is the money intended to support, and on what timetable? Where assumptions have changed, ask how the funding plan addresses those changes. Keep unresolved differences explicit in your purchase analysis.
3. Capital-work planning: require scope, timing, and funding
Ask for a schedule of planned capital work, available cost estimates, and proposed payment arrangements. Separate work with a defined scope and approved funding from preliminary projects. Seek clarification whenever documents describe the same project differently.
For each significant item, ask what happens if timing or cost changes. The objective is not an assurance that every estimate will hold. It is to understand the proposed response before relying on the plan in a purchase decision.
4. Assessment visibility: separate existing obligations from possibilities
Request written details of existing and proposed special assessments, including payment schedules and the work each assessment is intended to fund. Ask separately about projects under discussion for which no funding decision has been made.
Have counsel clarify how any identified obligation would be allocated between buyer and seller under the proposed transaction documents. Keep that allocation distinct from future ownership exposure. Resolving a payment at closing does not resolve every question about the association's subsequent funding needs.
5. Consistency over time: reconcile the financial narrative
Compare the current plan with prior budgets, available financial statements, and relevant meeting minutes. Ask for explanations of changes in project scope, contributions, and anticipated spending. Request reconciliation rather than assuming every difference signals strength or weakness.
Before placing a property on your shortlist, have your advisers identify what is resolved and what remains conditional. A useful comparison distinguishes documented answers from open questions without turning either into an unsupported prediction.
For a buyer considering Fendi Château Residences Surfside, the next step is a property-specific review, not a conclusion drawn from the name. Ask which entity carries each relevant obligation and which documents govern the purchaser's contribution. Seek written clarification rather than assuming a brand relationship provides financial protection.
Apply the same discipline to any ownership or operating arrangement presented during the sales process. Ask whether obligations rest with one association or involve additional entities, and have counsel explain any applicable allocation. Resolve these questions for the particular purchase; do not presume the answers apply across properties.
Keep design preference in the conversation, but not as a substitute for financial evidence. A residence can remain compelling while requiring further investigation before an offer is finalized.
When reviewing Arte Surfside alongside another candidate, request the same categories of information for both. Create a worksheet with separate fields for adopted contributions, reserve recommendations, planned work, assessment obligations, and unresolved questions. Record each document's date so advisers know which period they are comparing.
Do not let the worksheet become a contest for the lowest stated monthly payment. Ask what each payment covers, what falls outside it, and which assumptions support the proposed ownership budget. Keep approved figures separate from projections, even when they appear in the same presentation.
Request a purchase-specific summary from your legal and financial advisers. It should identify the obligations you would accept, the questions still requiring answers, and any contractual protections they recommend pursuing.
The goal is a shortlist supported by documented obligations and clear plans, not an assessment-free label. Decide in advance which unresolved issues would warrant further review, a revised offer, or a pause. That discipline keeps the residence's appeal from determining the financial conclusion.
Before closing, ask whether any relevant budget, project, or assessment decision has changed since the initial review. Make your final choice with a clear distinction between what has been established and what remains uncertain.
Explore your Surfside residence search with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. It presents five funding-review priorities and does not certify any named residence as a lower-exposure choice.
Start with the current adopted budget, reserve documentation, planned capital-work schedule, and written information about existing or proposed assessments.
Do not use brand recognition as evidence of funding strength. Request documentation specific to the ownership obligations you would accept.
Ask your advisers to compare balances and scheduled contributions with the relevant reserve study and anticipated work, rather than evaluating the balance alone.
Request evidence of approval, an effective date, and the corresponding treatment in the financial documents. Keep proposals separate from adopted commitments.
Request scope, timing, available cost estimates, and payment arrangements. Ask how the plan would respond to changes in cost or timing.
Obtain its purpose and payment schedule, then have counsel clarify the buyer's and seller's obligations under the proposed transaction documents.
Ask which projects remain under discussion and what funding decisions are unresolved. Keep those questions visible in the purchase analysis.
Request the same document categories for each candidate and record document dates. Separate approved figures, projections, and unanswered questions in the comparison.
Ask whether relevant budget, capital-work, or assessment decisions have changed. Have advisers review any changes before finalizing the purchase.