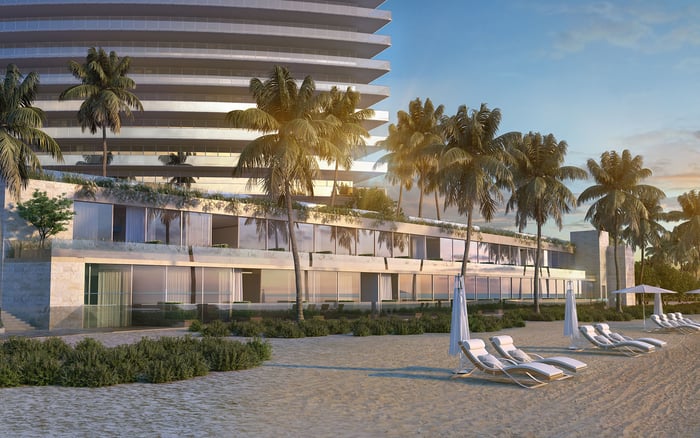
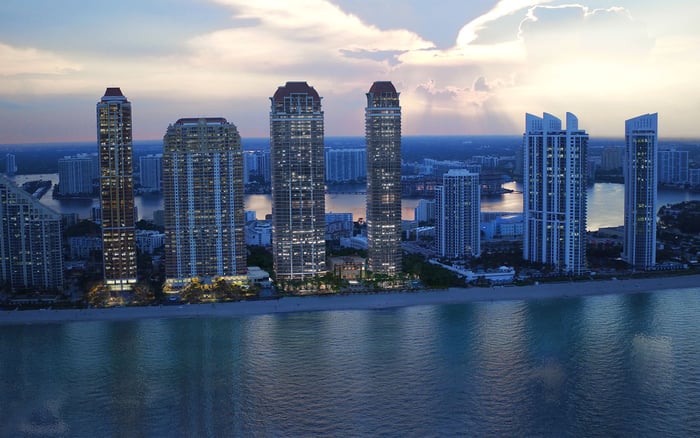
Five Sunny Isles Beach residences offer distinct starting points for financing diligence, from substantial construction backing to resale expense benchmarks. This buyer-focused ranking separates those signals from actual unit-mortgage eligibility and identifies the documentation worth reviewing before committing.
For a Sunny Isles Beach buyer, the most consequential luxury may be flexibility: the ability to finance an acquisition without letting the property’s documentation dictate the transaction. An oceanfront address and a distinguished brand can shape a shortlist. Neither establishes that a lender will accept the building or the individual residence.
This ranking prioritizes disclosed construction financing, available expense information and issues that warrant early lender review. It does not rank verified mortgage approvals or completed association document packages. Sunny Isles luxury-condo purchases often involve jumbo products, with lenders examining owner-occupancy ratios, reserve funding and litigation.
The distinction is especially important at Bentley Residences Sunny Isles: substantial developer financing offers a concrete measure of project backing, but buyers still need an independent assessment of their intended loan. For purchasers considering portfolio financing, the question is not simply whether a tower has attracted capital. It is whether the tower’s current records satisfy their chosen lender.
1. Bentley Residences: strongest disclosed construction-financing metric
Dezer Development secured a $630 million construction loan from Madison Realty Capital for Bentley Residences on the Sunny Isles Beach oceanfront. Among these five properties, it is the largest disclosed construction-financing figure-and the basis for Bentley’s first-place position.
For buyers, that financing demonstrates substantial project-level backing, not a substitute for residential underwriting. It does not establish individual-unit mortgage eligibility, agency warrantability or document-package completeness. The next step is to ask the intended lender which project information it requires and whether it can evaluate the proposed purchase before the buyer makes financing assumptions.
2. The St. Regis Residences, Sunny Isles Beach: substantial Bank OZK backing
Fortune International Group and Château Group secured $418.3 million in Bank OZK construction financing for this oceanfront development. The financing increased from a previous $219 million commitment, offering a second substantial project-capital benchmark within the ranking.
That expanded commitment strengthens the documented financing picture at the development level. It does not establish that Bank OZK, or another lender, will finance a particular buyer’s residence. Purchasers should keep the construction facility and their acquisition loan in separate diligence files, with the latter assessed against the lender’s own requirements.
3. Porsche Design Tower: useful expense and resale benchmarks
At 18555 Collins Avenue, Sunny Isles Beach, FL 33160, Porsche Design Tower offers concrete starting points for financial modeling. An average association fee of $2.28 per square foot per month provides a preliminary carrying-cost benchmark. A listing snapshot showed 34 residences offered between $3,999,000 and $14,597,000.
These figures support an initial acquisition discussion, not a finished underwriting model. The fee average is not a unit-specific assessment, and the advertised prices are neither closed-sale comparables nor guaranteed current inventory. Porsche’s third-place position reflects the availability of expense and market information, not evidence of easier mortgage approval.
4. Turnberry Ocean Club: ownership concentration warrants early screening
Turnberry Ocean Club stands at 18501 Collins Avenue, Sunny Isles Beach, FL 33160. An ownership sample suggested approximately 94% investor ownership among the sampled units. That makes ownership concentration a priority question for buyers considering financing.
The sample is not a verified association-wide occupancy certification and does not establish non-warrantability or an automatic lending disqualification. Investor concentration can, however, complicate conventional financing. Before making an offer, buyers should seek current association-level information and ask their lender how it would evaluate the ownership profile, including whether a portfolio product merits consideration.
5. The Ritz-Carlton Residences, Sunny Isles Beach: documented sponsorship and service identity
Developed by Château Group and Fortune International Group, this Collins Avenue oceanfront property combines a documented development partnership with Ritz-Carlton concierge services. Its fifth-place position rests on those established attributes, not on demonstrated present-day residential lending conditions.
Historical launch terms should not guide a current financing model. A January 2015 planned deposit schedule called for 25% at contract, 15% at groundbreaking, 10% later and 50% at closing. Those development-stage arrangements are not present-day resale down-payment requirements. Buyers should obtain transaction-specific terms rather than treat historical marketing conditions as current credit guidance.
For purchasers comparing The St. Regis Residences, Sunny Isles Beach with Bentley, the financing figures draw a meaningful distinction in disclosed project backing. They do not establish which building offers faster approvals, lower down payments or more accommodating portfolio terms.
A disciplined comparison separates three questions: what financing supports the development, what the lender requires from the property and what it requires from the purchaser. Disclosed construction financing answers only the first. Ask the lender to identify the remaining review steps and distinguish an initial discussion from an actual lending decision.
This avoids a common analytical shortcut: treating the size of a developer’s loan as evidence that a buyer’s mortgage will be straightforward.
The objective is a file the intended lender can evaluate, not merely a collection of attractive project materials. Ask which current documents it needs, including the condo questionnaire, association budget, reserve study, insurance certificates and litigation disclosures. Establish who will supply them and which items remain subject to review.
At Turnberry Ocean Club Sunny Isles, ownership information deserves particular attention: the sampled investor figure is a diligence flag, not a final underwriting answer. Request the association’s current information and let the lender determine its relevance to the proposed loan.
For Porsche Design Tower, begin with the actual residence’s association charges rather than turn a building-wide average into a firm budget. Across all five properties, seek written clarity on the lender’s assessment before treating financing as settled. A recognizable name should never stand in for that confirmation.
Project-level financing criteria can influence both today’s loan process and demand from future purchasers. Buyers planning to hold a residence should therefore make financing diligence part of their exit analysis, without assuming that today’s lending conditions will persist.
At The Ritz-Carlton Residences, Sunny Isles Beach, the sponsorship and concierge identity are established considerations. Whether a particular acquisition meets a lender’s current criteria remains a separate question. The same distinction applies throughout this shortlist: appreciate the address, but evaluate the records independently.
For a discreet perspective on matching your Sunny Isles Beach shortlist to your acquisition priorities, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationBentley Residences ranks first for its $630 million construction loan from Madison Realty Capital. That ranking reflects disclosed project backing, not verified buyer mortgage access.
No. Construction financing does not establish individual-unit mortgage eligibility, agency warrantability or a complete association document package.
The St. Regis Residences, Sunny Isles Beach secured $418.3 million from Bank OZK, increased from a previous $219 million commitment.
An average of $2.28 per square foot per month offers a preliminary expense benchmark. Buyers should confirm the actual charges for their intended residence.
No. The snapshot of 34 listings at $3,999,000 to $14,597,000 reflects advertised prices, not completed sales or guaranteed current availability.
The approximately 94% figure came from a sample of units, not a verified association-wide occupancy certification. Current ownership information should be reviewed with the buyer’s lender.
The sampled Turnberry figure does not establish automatic disqualification or non-warrantability. Investor concentration can complicate conventional financing and deserves early lender review.
Ask about a current condo questionnaire, association budget, reserve study, insurance certificates and litigation disclosures. The intended lender should specify its requirements.
No. The January 2015 planned deposit schedule was a development-stage arrangement, not a present-day resale down-payment requirement.
Project-level lending criteria can affect demand from future purchasers as well as the current buyer’s loan process. Current financing conditions should not be assumed to persist.