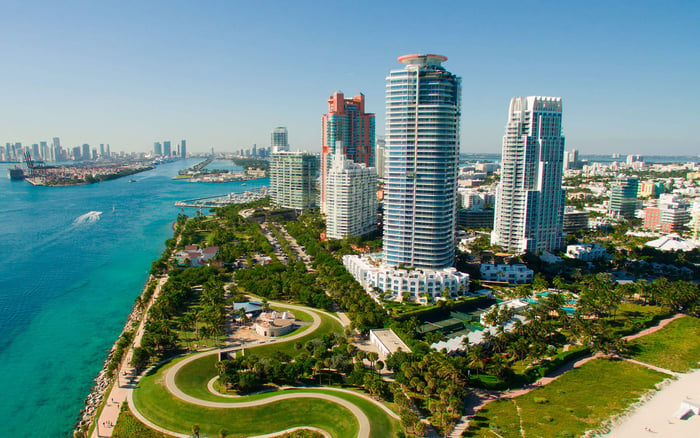
A five-project starting point for multigenerational buyers, with a document-first approach to reserves, insurance, assessment exposure, and the practical requirements of shared family living. Inclusion is not a finding of financial strength or lower risk.
For a multigenerational household, a luxury condominium purchase calls for two distinct conversations. One concerns daily life: privacy for grandparents, room for children, and space to gather without surrendering independence. The other concerns stewardship: what the family will own, what it will fund, and how clearly it can understand those obligations before closing.
The five projects below are starting points for individual evaluation, not an established ranking of reserve strength, insurance quality, or assessment exposure. Inclusion is not a finding that any project meets those standards. The right choice for a family should emerge from current documents and a residence-specific review, not its position on a list.
Financial confidence should be a condition of selection, not an assumption attached to a prestigious address.
1. 2200 Brickell: establish the ownership-cost baseline
For a family considering 2200 Brickell, begin with a written ownership-cost worksheet. Ask which expenses belong to the association, which fall directly to the owner, and which remain estimates. Request the applicable budget, reserve information, and explanations for any projected contributions.
Then test the intended residence against the household’s actual arrangements. Identify who will live there full time, who will visit, and whether the sleeping and gathering spaces support those patterns. Neither affordability nor family suitability should be inferred from the project name.
2. Apogee South Beach: examine capital obligations
Apply the same financial review to Apogee South Beach, with particular attention to planned work. Request written details of approved projects, proposed projects, available funding, and any remaining obligations associated with the residence under consideration.
For the family review, map the route from arrival to the front door and through the home. Ask about access, visitors, and any household assistance the family expects to use. Confirm the applicable rules rather than assuming a preferred arrangement will be permitted.
3. Oceana Bal Harbour: clarify insurance responsibilities
For Oceana Bal Harbour, request a clear explanation of the applicable association coverage and the owner’s separate responsibilities. Ask an insurance professional to examine policy terms, exclusions, deductibles, and the treatment of improvements within the residence.
Pair that review with practical questions about shared ownership. Decide who will receive notices, coordinate insurance, authorize work, and respond when other family members are away. Evaluate the residence alongside the family’s ability to manage it consistently.
4. Park Grove Coconut Grove: test long-term household fit
Evaluate Park Grove Coconut Grove against both today’s household and plausible future needs. Ask whether the specific residence can accommodate changing privacy requirements, visiting relatives, or assistance with daily activities. Verify dimensions and permissions rather than treating a floor plan as sufficient confirmation.
Apply the same reserve and assessment questions used for every other candidate. A compelling lifestyle impression should not displace a review of funding, maintenance obligations, and unresolved financial questions.
5. Turnberry Ocean Club Sunny Isles: review disruption as well as cost
For Turnberry Ocean Club Sunny Isles, ask about any contemplated work and the documentation supporting its scope, timing, and funding. Separate approved obligations from preliminary discussions, and have the family’s advisers identify what remains unresolved.
Consider the household’s tolerance for disruption alongside its financial capacity. Ask how any identified work might affect access, quiet hours, or the family’s intended use of the property. These are diligence questions, not statements that such work or restrictions exist.
When considering 2200 Brickell, resist reducing the reserve discussion to a single balance. Request the underlying schedule of anticipated work, the assumptions behind estimated costs, and the proposed funding timetable. Ask a qualified adviser to reconcile those materials with the current financial statements and budget.
Use the same approach when reviewing Park Grove Coconut Grove. Distinguish money already held from contributions expected later. Ask whether identified obligations have funding assigned to them and which decisions remain outstanding. Treat unanswered questions as open items, not evidence of either strength or weakness.
For a multigenerational purchase, agree on the family’s own funding arrangements as well. Decide who contributes to recurring expenses and how an extraordinary request would be handled before the family becomes emotionally committed to a purchase.
A Miami Beach search that includes Apogee South Beach should include a specific insurance review. Request applicable policy documents and a written explanation of coverage limits, deductibles, exclusions, and renewal timing. Have an insurance professional identify the owner coverage appropriate to the contemplated residence and use.
Confirmation that a building is insured should not end the conversation. Ask how responsibility would be allocated under the governing documents and relevant policies. Seek clarification of unresolved coverage or claim questions rather than attempting to interpret technical language alone.
Keep this review separate from the monthly carrying-cost comparison until the relevant figures and responsibilities are clear.
For a Bal Harbour candidate such as Oceana Bal Harbour, request written details of approved assessments, any unpaid balance attributable to the residence, and proposed expenditures still awaiting a decision. Ask counsel to review the transaction documents for the allocation of responsibility between buyer and seller.
Also request the relevant meeting minutes, maintenance information, and capital plans for professional review. The objective is to distinguish a defined obligation from an unresolved proposal, not to label every discussion a future charge.
Do not treat limited exposure as a promise of no future assessments. Instead, establish how much uncertainty the family will accept and which unresolved matters require clarification before proceeding.
For a Sunny Isles Beach search that includes Turnberry Ocean Club Sunny Isles, prepare a household brief before touring. Include privacy, sleeping arrangements, step-free access needs, visiting relatives, pets, and assistance arrangements. Check each requirement against the particular residence and applicable rules.
Give every generation a voice, but keep the decision criteria consistent. A beautiful gathering room should not distract from an unsuitable bedroom arrangement, just as an attractive monthly figure should not replace a complete ownership review.
The final choice should satisfy both briefs: a home the family can comfortably share and obligations its advisers have helped it understand.
For a discreet conversation about your family’s Miami-Dade condominium search, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. Inclusion does not establish comparative reserve strength, insurance quality, or assessment exposure; each candidate requires a current document review.
Request reserve information, current financial statements, the budget, and the schedule and funding assumptions for anticipated work. Ask a qualified adviser to reconcile those materials.
Do not use the balance alone as your decision criterion. Ask how it relates to anticipated obligations, timing, and future contributions.
Request applicable policy documents and clarification of limits, deductibles, exclusions, and renewal timing. Have an insurance professional explain the owner's separate responsibilities.
Ask for written information on approved assessments, unpaid amounts associated with the residence, and proposed expenditures. Have counsel review how the transaction allocates responsibility.
Do not interpret that phrase as a guarantee. Establish acceptable uncertainty and resolve material questions before proceeding.
Test the specific home against the household's privacy, sleeping, accessibility, and gathering needs. Verify dimensions and applicable rules rather than assuming suitability.
Yes. Include assistance arrangements in the household brief and confirm applicable access, occupancy, and visitor rules.
Agree on recurring contributions, responsibility for notices and insurance, and a process for extraordinary expenses before committing to the purchase.
Use both a residence-specific family assessment and a professional review of financial and ownership obligations. Neither prestige nor list position should substitute for those evaluations.