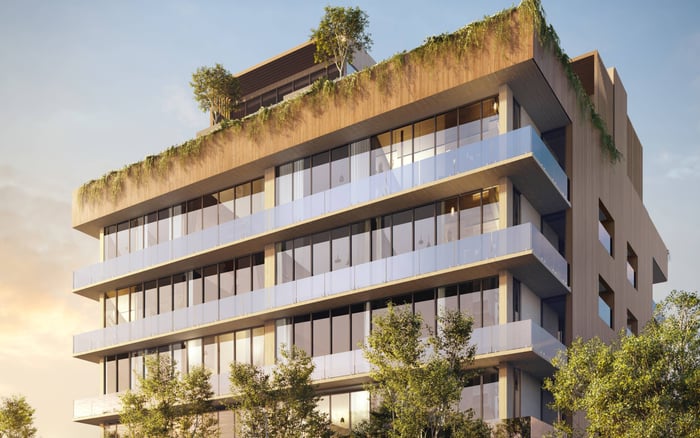
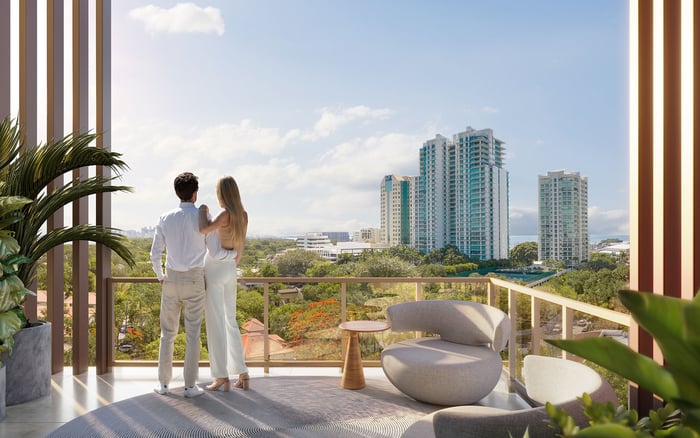
A disciplined first-year budget for The Lincoln Coconut Grove separates purchase-price payments, closing costs and recurring ownership expenses, with particular scrutiny of any proposed working-capital charge.
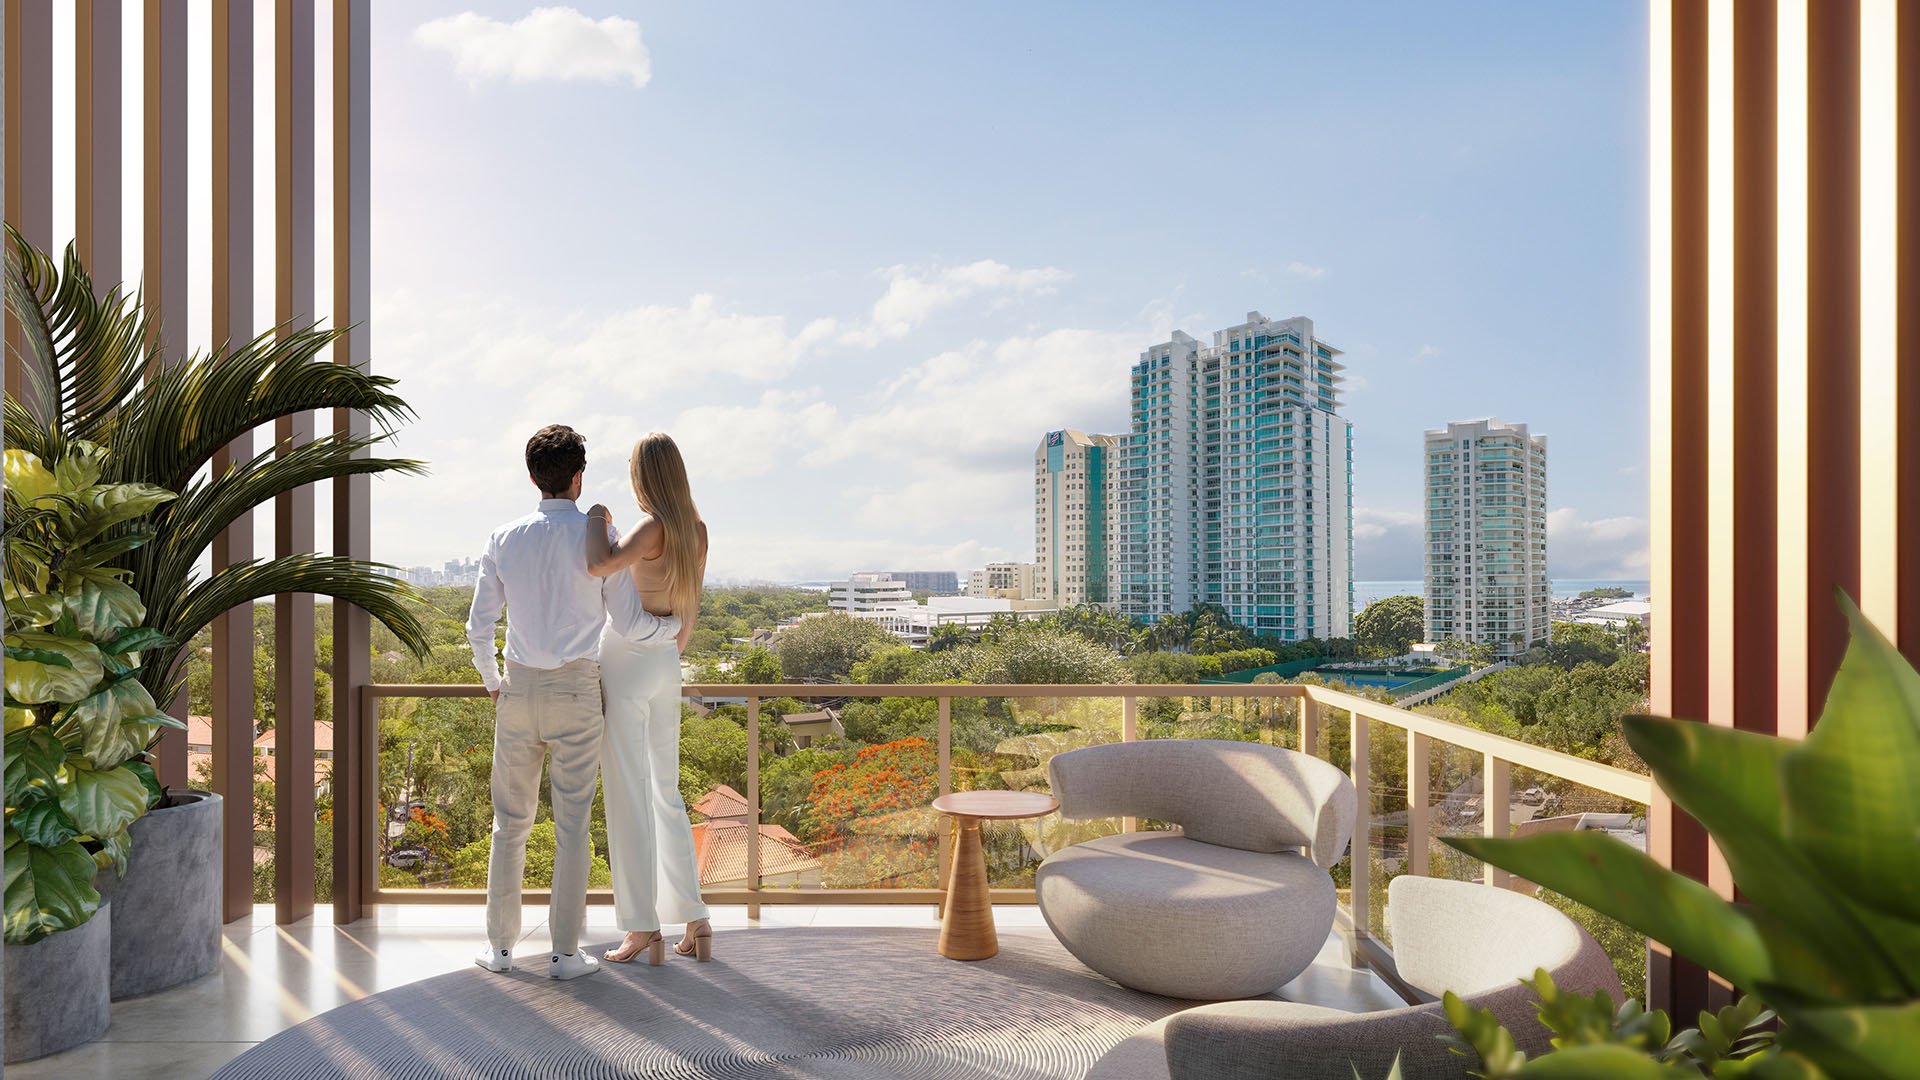
At The Lincoln Coconut Grove, an eight-story, 48-residence condominium at 2650 Lincoln Avenue, the serious buyer’s financial checklist extends beyond the purchase price. It should separate payments credited toward the purchase price, transaction expenses and the recurring cost of holding the residence.
Here, “first year” means the first 12 months after closing. Pre-closing deposits belong on a separate timeline; closing-day liquidity bridges the acquisition and ownership budgets. Any proposed working-capital payment needs its own explanation, not merely a place within a broad percentage allowance.
Do not treat a Lincoln working-capital charge as established.
Before budgeting it as an obligation, obtain the applicable contract provision, amount, recipient and legal review. A prudent allowance does not establish that a particular fee is payable.
The marketed deposit schedule is 20% at contract, 10% at groundbreaking, 10% at the fifth-floor pour and 60% at closing. Confirm both the percentages and milestone triggers in the executed purchase agreement rather than relying on promotional timing.
These payments apply to the purchase price. They are not closing costs, association dues or contributions to an operating fund.
For an illustrative $2.5 million purchase, the schedule would require $500,000 at contract, two subsequent payments of $250,000 and a $1.5 million purchase-price balance at closing. This is an arithmetic example, not a quoted Lincoln residence price or financing proposal. Reconcile any loan proceeds separately with the buyer’s required cash.
Keep three distinct categories in the acquisition worksheet:
Purchase-price payments, including deposits already paid.
Closing expenses, itemized by charge and recipient.
Ownership expenses for the following 12 months.
This separation prevents deposits from being mistaken for incremental expenses and makes closing-day liquidity easier to manage.
The Lincoln’s advertised association-fee range is $1,664-$3,461 monthly, equivalent to $19,968-$41,532 over 12 months before any assessment changes. No single advertised monthly figure should be assigned to every residence.
Two residences illustrate the difference. Residence 205 carries advertised dues of $3,461 monthly, or $41,532 annually. Residence 406 carries advertised dues of $2,180 monthly, or $26,160 annually. These figures are planning inputs, not guaranteed post-closing assessments or substitutes for the proposed association budget.
Request the budget applicable to the selected residence and ask how its assessment is calculated. Confirm what the charge covers and which ownership expenses remain outside it.
For a buyer also considering Arbor Coconut Grove, use the same residence-specific worksheet rather than comparing headline monthly figures. Compare documented expense exposure; do not assume nearby condominiums share a fee structure.
A proposed working-capital fund contribution should be examined as a separate payment intended for operations or other purposes specified in the governing documents. Its purpose and authorization matter more than its label.
For illustration, a contribution equal to two to three months of association dues would represent $6,000-$9,000 at assumed dues of $3,000 monthly, separate from $36,000 in annual dues. That is not a confirmed Lincoln requirement.
Capital contributions require particular care. Generic homeowners’ association guidance describing a routine, buyer-paid contribution does not establish that a proposed condominium charge is permissible. Counsel should examine the proposed charge’s actual structure, not just its label, and determine whether it complies with applicable Florida condominium law.
Before accepting any contribution, have counsel establish:
Who receives and controls the money.
Which contractual or governing provision authorizes it.
What purposes the funds may serve.
Whether the structure complies with Florida condominium law.
Do not assume a payment is valid, refundable or non-refundable simply because it is called working capital. Apply the same document-first discipline when comparing Opus Coconut Grove, without transferring one project’s terms to another.
Using an illustrative closing-cost allowance of 3%-4.5% of the purchase price, a $2.5 million acquisition would require $75,000-$112,500 before first-year dues and other ownership costs. This is an arithmetic planning example, not a Lincoln-specific quote or a confirmed market benchmark.
The purchase agreement and actual transaction structure determine whether a development fee applies. Do not automatically add a separate development-fee allowance to the broader closing-cost allowance: first establish whether it is already included.
Request an estimate identifying any applicable development fee, documentary stamp taxes, title charges, legal and recording costs, and proposed working-capital payment. Each applicable item should specify an amount, responsible payer and explanation.
Count working capital once. If the closing estimate includes it, do not add a second contribution line outside that total. If the estimate excludes a legally supported payment, add the actual amount separately.
The same discipline applies when evaluating Four Seasons Residences Coconut Grove: a comparable worksheet is useful; an assumed comparable fee package is not.
Using the illustrative $2.5 million price and assumed $3,000 monthly dues, the illustrative closing-cost allowance plus 12 months of association payments totals $111,000-$148,500. This is a transaction-and-dues subtotal, not the full cash requirement for acquiring and owning the residence.
Place any working-capital amount inside or outside that subtotal according to whether the closing allowance includes it-never both. Purchase-price equity remains separate, as do mortgage payments, property taxes, insurance and other carrying costs.
The final worksheet should show closing-day cash separately from the following 12 months of ownership outflows. Reconcile deposits already paid against the purchase price, identify any financing proceeds and replace estimates with documented amounts as the transaction progresses.
An upfront operating contribution does not establish adequate long-term reserves or eliminate special-assessment risk. Review the proposed association budget alongside the governing provisions for any working-capital fund. Ask what supports current operations and what addresses longer-term capital needs.
Counsel should also examine any resale contribution or transfer-fee provisions under applicable condominium law rather than relying on homeowners’ association guidance. Neither a familiar label nor a generic fee convention settles the issue.
The strongest checklist ends with documented obligations: a confirmed deposit schedule, residence-specific dues, an itemized closing estimate and a legally reviewed explanation of any contribution. Financial clarity preserves the pleasure of the purchase by separating what is known, what is illustrative and what still requires contractual confirmation.
For a discreet conversation about your Coconut Grove acquisition and buyer checklist, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationDo not treat one as an established obligation without the applicable contract provision, amount and recipient. Counsel should review any proposed payment’s authorization and legality.
The marketed schedule is 20% at contract, 10% at groundbreaking, 10% at the fifth-floor pour and 60% at closing. Confirm the percentages and milestone triggers in the executed agreement.
No, deposits apply toward the purchase price. Track them separately from transaction expenses and ownership costs.
The advertised range is $1,664–$3,461 monthly, equivalent to $19,968–$41,532 for 12 months before changes. Confirm the assessment for the selected residence against the proposed budget.
Residence 205 has advertised dues of $3,461 monthly, or $41,532 annually. Residence 406 has advertised dues of $2,180 monthly, or $26,160 annually; neither listing guarantees future assessments.
At assumed dues of $3,000 monthly, a two- to three-month contribution would equal $6,000–$9,000. This is an arithmetic planning example, not a confirmed Lincoln charge.
A fee label alone does not establish that a proposed payment is permissible under applicable Florida condominium law. Counsel should examine its recipient, authorization and actual structure.
An illustrative allowance of 3%–4.5% equals $75,000–$112,500 on a $2.5 million purchase, but it is not a Lincoln-specific quote or a confirmed market benchmark. Replace it with an itemized transaction estimate.
Confirm whether the closing-cost estimate already includes the payment. Add it separately only if it is excluded and is a legally supported obligation.
An upfront contribution does not establish adequate long-term reserves or eliminate special-assessment risk. Review the budget and the fund’s governing provisions separately.