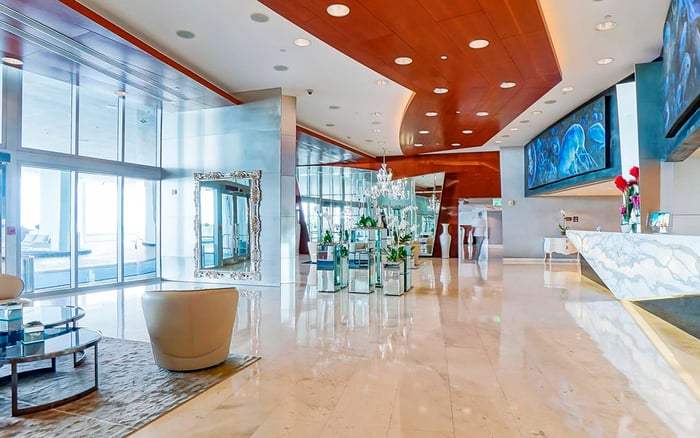
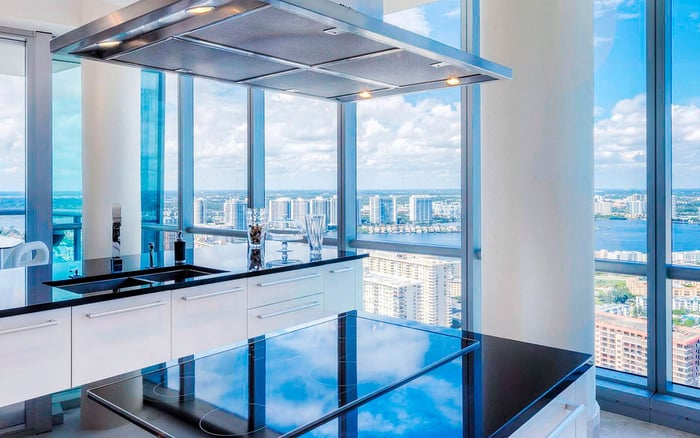
A primary-residence purchase at Jade Signature calls for more than an agreed price. Review association records, arrange unit-owner insurance, reconcile every closing adjustment, and have counsel address funding delays before move-in plans become commitments.
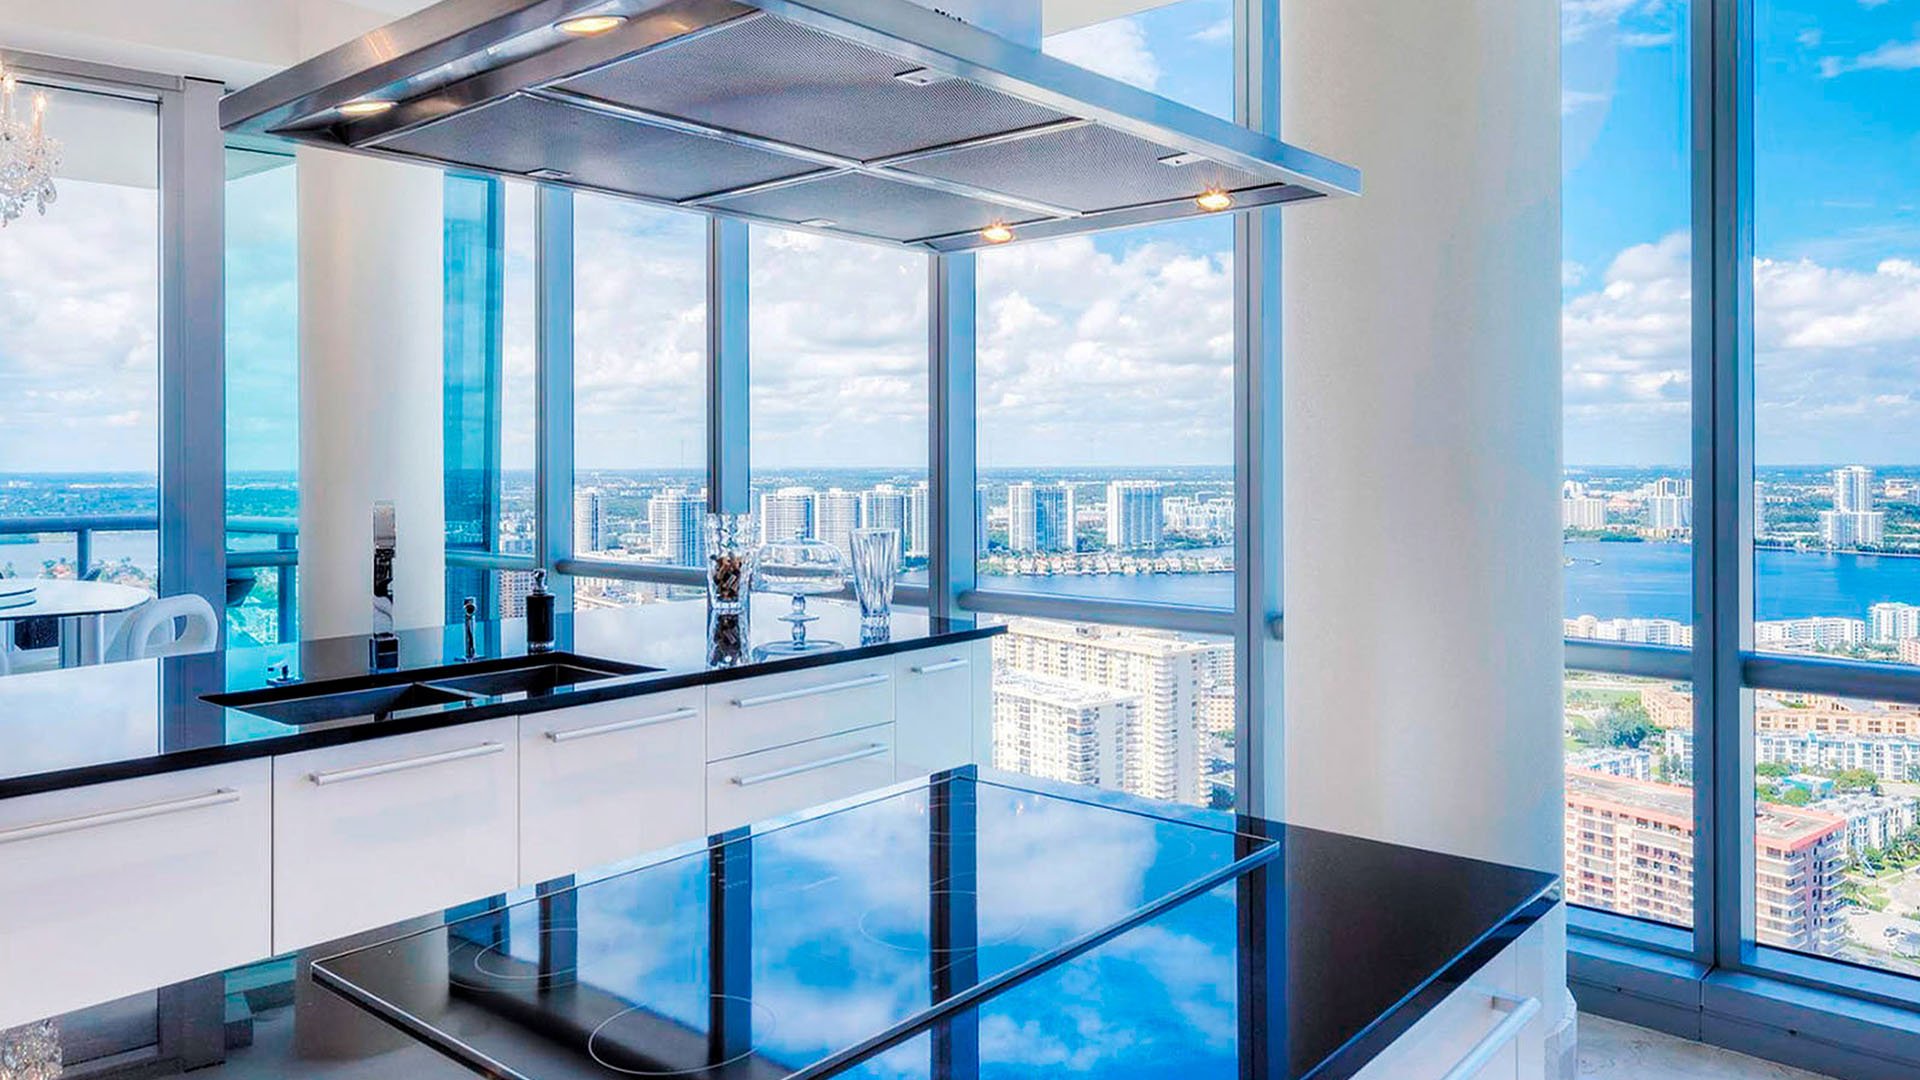
For a primary-residence buyer, the decisive luxury is certainty: knowing what is insured, what remains payable, and when the transaction can support possession. At Jade Signature Sunny Isles Beach, the review should connect three workstreams too often handled separately: insurance evidence, cash-to-close reconciliation, and a plan for funding delays.
The property is located at 16901 Collins Avenue, Sunny Isles Beach, FL 33160, with a completion year of 2018. Buyers should confirm the construction date and legal condominium identity through association records. Neither the address nor the building's relative youth answers the questions that matter at settlement.
The most useful buyer's guides distinguish a property's appeal from the documents needed to acquire it confidently. For a household planning a move, the objective is to resolve financial and timing questions before releasing contingencies-not while coordinating furniture deliveries.
Jade Signature Condominium Association, Inc., is identified by condominium registration PR75900 and managing-entity number MA70959. Those identifiers help establish which association records to request. They do not establish current management, insurance sufficiency, financial condition, rules, or inspection compliance.
Request the current operating budget, reserve balances, reserve-funding information, recent meeting minutes, assessment notices, and insurance documentation. Read them together. A budget is more useful alongside reserve funding and planned capital work; an assessment notice must be reconciled with the proposed closing adjustments.
Ask the association directly about active and pending special assessments. A newer luxury tower should not be presumed assessment-free. For a resale purchase, have the closing team confirm how any applicable assessment will be treated under the contract. Do not assume the seller's payment history resolves the buyer's exposure.
Buyers also considering Jade Ocean Sunny Isles Beach should apply the same document discipline independently. A nearby property's records cannot establish Jade Signature's obligations or financial position.
Association master insurance and a buyer's HO-6 unit-owner policy are separate. Evidence of the former is not a substitute for arranging the latter. Obtain the association's current insurance documentation and an actual unit-owner quote during due diligence, allowing the insurer and, where applicable, the lender to review the transaction's requirements.
The current master-policy limits and deductibles are not established here. Ask the association for the relevant documents and have an insurance professional explain how the proposed personal policy relates to them. Avoid building a household budget around a listing's insurance estimate.
Financed buyers should arrange HO-6 coverage and provide proof to the lender or title company at or before closing. Budget for the first year's premium as a potential upfront expense. Confirm whether it will be paid separately or reflected in the closing figures so it is not counted twice.
For any insurance binder proposed as closing evidence, ask the insurer to confirm the insured parties, unit identification, effective date, coverage terms, and payment status. Confirm with the recipient that the evidence is acceptable. These are diligence requests, not verified Jade Signature binder requirements. An anticipated document is not a completed insurance arrangement.
Review cash to close as a reconciliation, not a headline number. Start with the purchase price and deposits already paid, then trace financing proceeds, credits, charges, and adjustments through the closing documents. Have the closing team explain the amount due and identify any expenses outside it.
Keep the review organized around distinct categories:
Deposits and credits, including confirmation that previously paid funds are reflected correctly.
Tax prorations and any prepaid interest applicable to the financing.
Insurance premiums and lender escrow reserves, with separate payments identified.
Title and recording charges, using transaction-specific figures.
Condominium fees and assessment adjustments confirmed with the association.
Request an explanation for changes between preliminary and final figures. The aim is not to hold every early estimate fixed, but to understand each revision before authorizing funds. Public listing estimates do not establish actual association charges or insurance costs.
For a primary residence, maintain a separate household planning ledger for move-in expenses and any timing cushion. Keep those amounts distinct from contractual closing obligations. This clarifies available liquidity without presenting an informal allowance as a required settlement charge.
A scheduled signing is not a promise of same-day funding or possession. Before committing to a move, ask the lender, closing agent, and attorney to identify the expected sequence for document completion, funding authorization, receipt of funds, disbursement, and possession under the contract.
Obtain transaction-specific answers about applicable wire deadlines and what happens if a required step is delayed. No particular lender cutoff or same-day disbursement procedure is established for this purchase. Obtain written expectations from the responsible parties rather than rely on a general assurance that closing will occur that afternoon.
If same-day completion is essential, ask counsel whether an express provision is appropriate and negotiable. Counsel should address the relevant event, notice obligations, available remedies, and any extension mechanism. Do not assume the phrase “same-day funding contingency” creates enforceable protection without agreed contractual language.
As a planning exercise, identify which arrangements can be postponed if funding is not confirmed: deliveries, movers, temporary accommodation, and other possession-dependent commitments. This is a buyer's contingency plan, not a statement about Jade Signature's procedures or an automatic right to delay performance.
Request milestone-inspection and Structural Integrity Reserve Study documentation separately. Condominium registration is not evidence that either requirement has been satisfied. Florida's milestone framework generally covers buildings with three or more habitable stories, with age-based deadlines and a possible earlier local deadline under specified circumstances. Confirm applicability rather than infer it from an address or completion year.
Jade Signature's definitive inspection and SIRS compliance status is not established here. Ask for the relevant records and have qualified advisers assess them alongside reserve funding and planned capital work.
For buyers weighing Muse Residences Sunny Isles Beach as another possibility, compare the completeness of each property's transaction file-not presumed similarities between towers. The final decision should bring together verified association information, acceptable insurance evidence, reconciled funds, and a realistic possession plan.
For a discreet perspective on your next primary residence, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationJade Signature is located at 16901 Collins Avenue, Sunny Isles Beach, FL 33160.
Its publicly recorded completion year is 2018. Confirm the construction date and legal condominium identity through association records.
No. Registration identifies the association but does not establish its finances, insurance coverage, inspection compliance, rules, or current management.
Request the current budget, reserve balances, reserve-funding information, recent minutes, assessment notices, and insurance documentation before releasing purchase contingencies.
No. Association master insurance and unit-owner HO-6 coverage are separate, so buyers should arrange personal coverage appropriate to their transaction.
Ask the insurer to confirm the insured parties, unit identification, effective date, coverage terms, and payment status. Confirm with the lender or closing agent that the proposed evidence is acceptable.
Review deposits, credits, tax prorations, prepaid interest, insurance, escrow reserves, title and recording charges, condominium fees, and assessment adjustments. Identify expenses paid separately to avoid double counting.
No. Confirm active and pending special assessments directly with the association and have the closing team address their contractual treatment.
Do not assume it is. Ask counsel whether an express, negotiated provision is appropriate and obtain transaction-specific funding expectations from the lender and closing agent.
No. Request milestone-inspection and Structural Integrity Reserve Study documentation separately and have qualified advisers assess applicability and compliance.