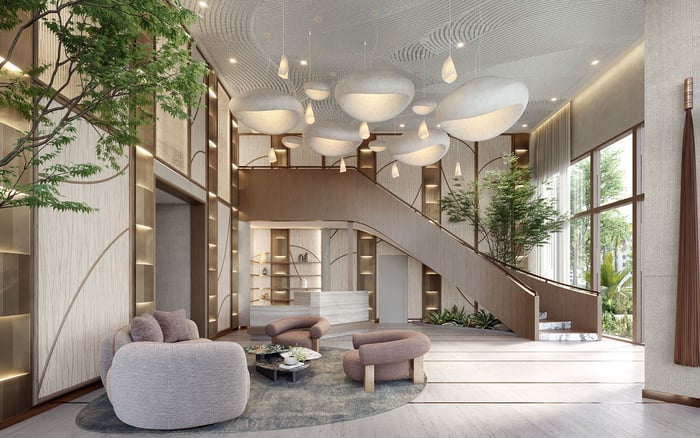
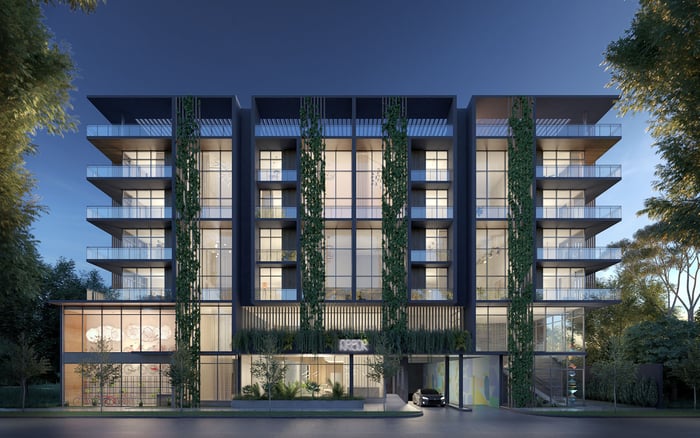
A buyer-oriented framework for separating Miami Tropic’s developer identity from private ownership records, family-office approvals, source-of-funds documentation, and independently verified wire instructions.
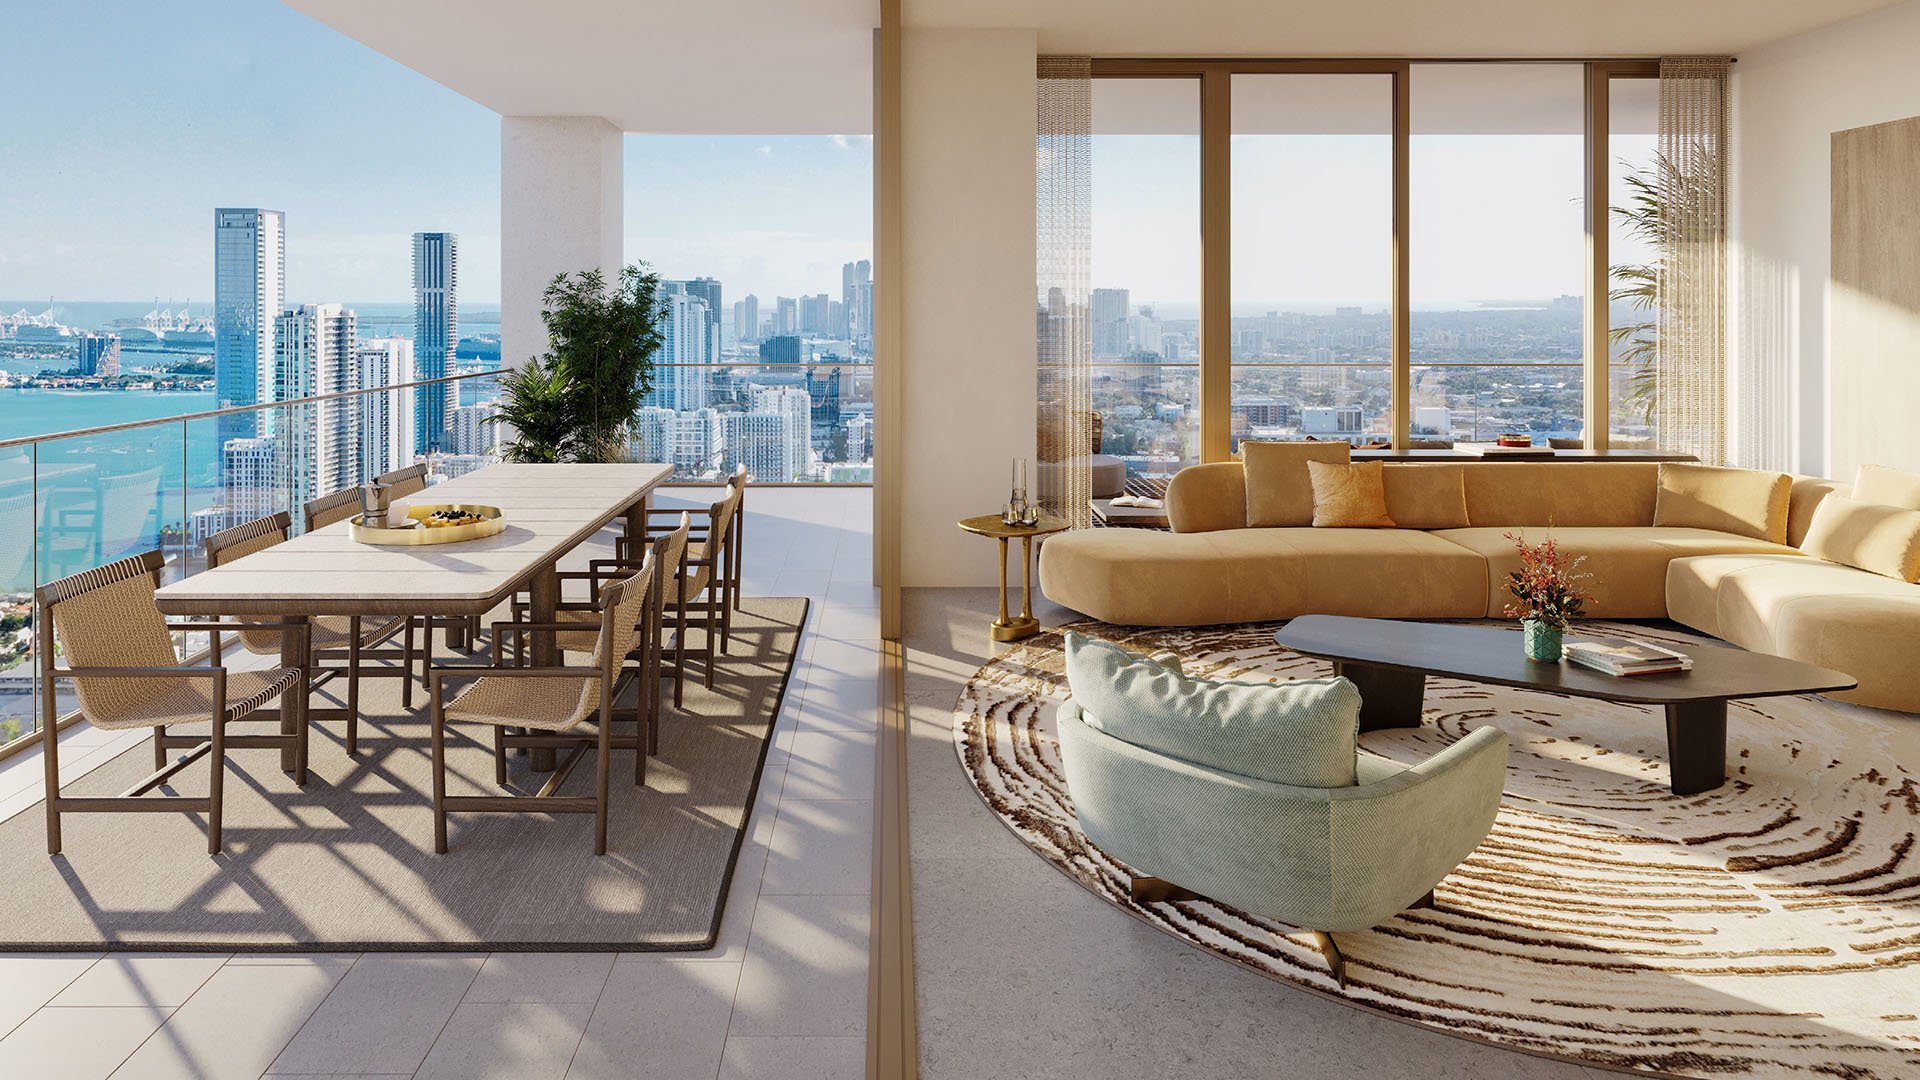
For a family office considering Miami Tropic Residences, the ownership file deserves the same attention as the residence itself. A compelling address and a distinctive hospitality partnership can generate interest. They cannot establish who owns each transaction entity, who may bind the buyer, or who may release funds. Those questions require separate, clearly documented records.
Jean-Georges Miami Tropic Residences is a Terra and Lion Development Group project developed in partnership with chef Jean-Georges. That identifies the development relationship. It does not establish a detailed capitalization table, a family-office investor roster, or an entity-by-entity beneficial ownership file.
The distinction is essential: developer identity is no substitute for transaction-level verification. The framework below sets out recommended buyer-side controls. It is neither a disclosed Miami Tropic approval system nor evidence of a problem involving the project.
A useful ownership file should distinguish four roles: the developer associated with the project, the owner identified for its website, the beneficial owners of the purchasing entity, and the individuals authorized to approve transfers. Each answers a different question. None should be inferred from another.
A website-owner identification should not be treated as a complete disclosure of the development’s beneficial ownership. Nor does knowing the buyer’s ultimate owners establish which employee or adviser may release a deposit.
To organize the file, create separate sections for counterparty identity, buyer identity, purchase authorization, and payment verification. Ask counsel to identify the contractual parties from the transaction documents rather than treating the project’s marketing name as its legal identity. Keep unresolved identity questions visible; familiarity with a brand should not settle them by assumption.
For an entity buyer, document and validate the ownership structure. Begin identity verification when the title or legal file opens, not when closing is imminent. Early review gives the team a defined place to resolve questions before payment instructions arrive.
A family office should separate the decision to acquire a residence from permission to send a particular payment. Purchase approval concerns the transaction. Wire approval concerns a specific movement of money to a verified recipient. One should not stand in for the other.
This framework does not establish a Miami Tropic-specific family-office approval workflow or underwriting memo format. Buyers should treat their internal approval process as their own governance framework and confirm contractual obligations separately with counsel.
A proposed approval matrix could identify who recommends the purchase, who approves it, who verifies payment instructions, and who authorizes release. It should also specify when a large transfer requires a second internal approval. That second approval is a recommended safeguard, not a confirmed Miami Tropic requirement.
Keep the record concise enough to use. An elaborate memorandum that leaves transfer authority ambiguous is less useful than a clear approval record supported by validated identity information. The objective is unmistakable responsibility before anyone is asked to act under time pressure.
This framework does not establish an exact Miami Tropic source-of-funds checklist. Buyers should not mistake a generic document package for a confirmed requirement or assume that internal family-office approval answers every question a transaction professional may ask.
Start by asking the relevant legal, title, and banking professionals what information they require, who should receive it, and how it should be transmitted. This is a recommended coordination step, not a statement that every participant imposes the same review.
For internal organization, the buyer could maintain a short funding summary alongside the ownership and authority records. It should explain the proposed payment arrangement clearly enough for advisers to identify unresolved questions. Supporting documents should follow the actual request, not an improvised universal checklist.
Keep these functions distinct. An ownership record explains who stands behind the buyer; an authority record explains who may act; a funding file addresses the requested information about the money. They are not interchangeable. If an adviser’s request is unclear, obtain clarification before circulating sensitive material or assuming the file is complete.
A recognizable residential identity can make a shortlist easier to navigate, but it should not change the standard of transaction verification. For a buyer also considering Cipriani Residences Brickell, the same principle applies: maintain a distinct file for each potential purchase rather than carrying assumptions from one opportunity to another.
Likewise, if Four Seasons Residences Coconut Grove is under consideration, that transaction should receive its own identity, authority, and payment checks. These comparisons concern buyer discipline, not either project’s ownership structure or compliance procedures.
The appeal of a residence and the evidence supporting a transfer belong in different parts of the decision. Keeping them separate preserves the pleasure of selecting a home without asking its branding to perform legal or financial verification.
Establish wire-fraud controls before instructions arrive. Independently verify wiring instructions using a trusted telephone number, not contact details supplied with the payment request. A callback serves its purpose only when the contact channel itself is independently trusted.
Avoid relying on emailed wire instructions alone. As a buyer-side safeguard, use documented verification procedures for every transfer and at least two verification methods before authorization. Multifactor authentication offers another recommended defense against account compromise, but it does not replace verification of the payment destination.
For large transfers, add a second internal approval. As a buyer-side operating recommendation, the record should identify who performed the checks and who authorized release. The approval matrix should leave no uncertainty about whether the person reviewing instructions also has authority to send funds.
Treat an instruction change as a reason to verify again, not as an administrative shortcut. If details cannot be independently confirmed, pause the release while the designated professionals resolve the question. These are general protective practices, not representations about Miami Tropic’s payment procedures or allegations of fraud.
The strongest ownership file is not necessarily the thickest. It lets an authorized reviewer distinguish established identities, outstanding questions, purchase approval, requested funding documentation, and verified payment instructions without reconstructing a chain of messages.
For Miami Tropic, that means appreciating the development partnership while keeping private ownership, buyer authority, and transfer controls distinct. Have the transaction’s legal and banking professionals confirm applicable requirements before relying on an internal checklist.
For a discreet perspective on South Florida residential opportunities, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationTerra and Lion Development Group are the identified developers, with the project developed in partnership with chef Jean-Georges.
No. Developer identity alone does not establish a detailed capitalization table or entity-by-entity beneficial ownership file.
A website-owner identification should not be treated as a complete beneficial ownership disclosure. Ask counsel to verify the relevant transaction entities separately.
No family-office investor roster is established here. Do not infer an investment relationship from the article’s discussion of buyer-side governance.
No. The approval framework is a buyer-side recommendation, not a confirmed project-specific workflow or underwriting memo format.
This framework does not establish an exact project-specific checklist. Buyers should confirm applicable requests with their legal, title, and banking professionals.
The recommended practice is to begin when the title or legal file opens rather than defer verification until closing. Entity buyers should also document and validate their ownership structure.
Use a trusted telephone number rather than contact details supplied with the payment request. As a buyer-side safeguard, apply documented checks and at least two verification methods before authorizing a transfer.
A second internal approval for large transfers is a recommended general safeguard. It is not presented here as a confirmed project requirement.
No. These controls are general protective recommendations, not allegations involving the project.