A disciplined closing file separates market-supported value from personal preference, defines the buyer’s appraisal-gap exposure, and puts hurricane-season questions to the professionals responsible for the transaction.
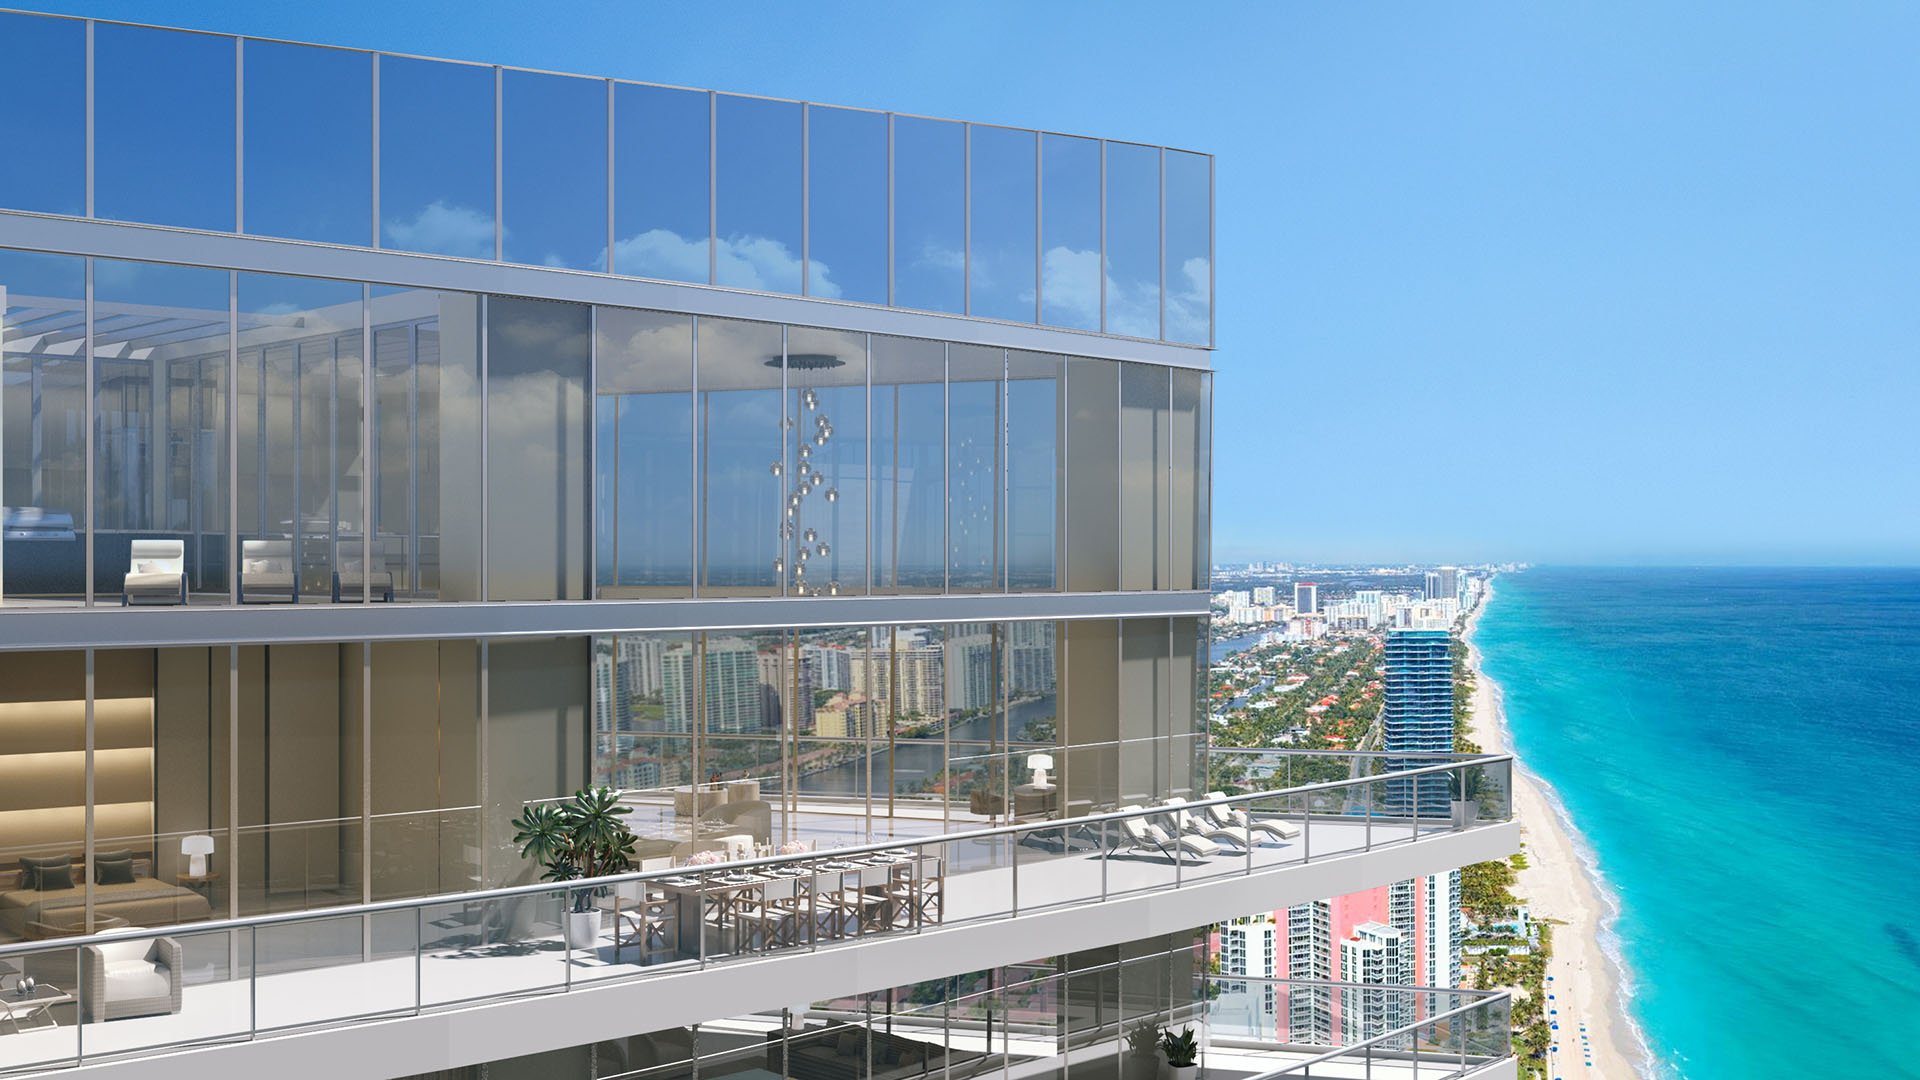
A luxury purchase can feel settled long before its financial documentation is complete. The terrace feels irreplaceable, the interiors reflect unusual craftsmanship, and the closing date is already on the calendar. Yet a closing scheduled during hurricane season demands a clear distinction between what the buyer loves, what the appraisal supports, and what the signed agreement requires.
The strongest file keeps those questions separate. It organizes evidence of the property’s value, identifies the buyer’s agreed exposure if the valuation falls short, and directs weather-related questions to counsel, the lender, and the insurance adviser. A compelling residence does not eliminate the need for precise terms. Nor does a calendar date prove that every contingency has been resolved.
The objective is not to diminish the property’s appeal. It is to clarify the purchase decision before a valuation dispute or weather concern complicates the final approach to closing.
The sales-comparison approach generally requires at least three closed comparable sales under the residential appraisal guidance considered here. Similarity matters across physical and legal characteristics, including site, room count, finished area, style, and condition. Flood-zone status is also an external consideration when selecting comparables. These principles should not be mistaken for identical requirements across every luxury financing arrangement.
Recency alone does not establish relevance. A sale older than 12 months may be appropriate when it is more similar to the subject property than newer alternatives. Active and pending listings can illuminate market context, but they do not replace the required closed transactions.
For a buyer considering Una Residences Brickell, the useful question is not simply what else is offered in Brickell. It is which completed sales provide a defensible comparison to the particular residence. An asking price expresses an expectation; a closed sale provides evidence of an agreed transaction.
Ask the appraisal team to explain material differences and the reasoning behind the selected comparables. A neighborhood average is not a complete answer.
Terrace value should be examined as a distinct component of the purchase, not folded into an automatic interior-space calculation. Under market-based adjustment principles, the relevant question is how buyers respond to the outdoor space relative to comparable properties. A fixed dollar-per-square-foot rule is inappropriate when market evidence supports a different adjustment.
For someone evaluating The Perigon Miami Beach, the distinction is useful: separate the personal appeal of outdoor living from the evidence supporting its contribution to value. Enthusiasm for Miami Beach is not itself an appraisal adjustment.
To prepare, organize available plans, measurements, photographs, and descriptions of the outdoor space for the appraisal team. Those materials describe what is being purchased; they do not establish a premium on their own. Ask how the terrace was considered and what market evidence supports that treatment. There is no universal interior-to-outdoor pricing ratio to assume here.
Design and architecture can be central to a luxury residence’s appeal without producing a dollar-for-dollar increase in appraised value. Bespoke improvements should be evaluated for their market contribution, not credited automatically at construction cost. The adjustment must reflect buyer response to differences between the subject property and comparable sales.
When reviewing a residence at One Thousand Museum Downtown Miami, a buyer can apply this distinction without making any assumption about that project’s valuation. Personal appreciation and market-supported contribution are different measures.
Consider preparing a concise improvement schedule with descriptions, available invoices, and photographs. Its purpose is to make the work understandable, not to instruct the appraiser to reimburse its cost through value. A highly individualized finish may matter to the buyer even when the available sales evidence does not support an equivalent adjustment.
This distinction allows a sophisticated purchaser to acknowledge personal value while keeping the financing decision anchored to the valuation actually delivered.
An appraisal gap arises when the appraised value falls below the agreed purchase price. Pricing and market trends may inform the buyer’s expectations, but the contract determines the agreed response to that shortfall.
One example of an appraisal-gap addendum caps the buyer’s obligation at an expressly stated maximum amount and prevents payment from exceeding the purchase price. It also directs the buyer to confirm with the lender whether the gap can be financed. That confirmation belongs before the commitment takes effect, not after the appraisal arrives.
The same example requires prompt delivery of the valuation to the seller. If the valuation plus the agreed gap remains below the purchase price, it provides a negotiation period, followed by termination and return of the deposit if no agreement is reached. These are features of that example, not remedies that automatically apply to every Florida purchase.
For a buyer considering Jade Signature Sunny Isles Beach, the practical lesson is to define the exposure in the signed documents. A preference for Sunny Isles Beach does not answer how much additional capital the buyer has committed to provide.
A hurricane-season closing calls for direct questions, not assumptions about automatic protections. Ask counsel what the executed contract says about casualty, timing, notices, and any requested extension. Ask the lender whether a weather event would trigger additional property-condition review. Ask the insurance adviser what must be confirmed for the intended closing date.
These are recommended lines of inquiry, not statements that a particular reinspection protocol, insurance requirement, delay right, or casualty remedy applies. Any proposed response should be checked against the actual transaction documents and confirmed requirements.
Keep weather-related correspondence separate from the appraisal-gap agreement. The gap provision addresses a valuation shortfall; it should not be presumed to resolve a separate issue involving property condition or closing timing. Clear separation helps the appropriate adviser identify the controlling terms.
Before closing, return to three questions. Does the appraisal explain its comparable sales and adjustments? Has the buyer confirmed how any agreed gap will be funded? Have counsel and the relevant advisers addressed the weather-related questions raised by this transaction?
A disciplined purchase can accommodate personal preference without confusing it with collateral value. It can also accommodate negotiated risk without leaving the amount or remedy undefined. For the luxury buyer, that clarity is as important as the residence itself: it preserves the distinction between a considered commitment and an assumption made under deadline pressure.
Explore South Florida’s luxury residential landscape with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationAn appraisal gap is the difference when the appraised value falls below the agreed purchase price. The signed contract determines the buyer’s agreed response.
The residential appraisal guidance discussed in the article generally requires at least three closed comparable sales in the sales-comparison approach. Requirements should be confirmed for the particular financing arrangement.
Yes. An older sale may be appropriate when it is more similar to the subject property than more recent alternatives.
No. Active and pending listings can provide market context, but they do not replace the required closed comparable sales.
Yes. Flood-zone status is an external factor to consider when selecting comparable sales.
Not automatically. Its contribution should be supported by market evidence rather than a fixed interior-to-outdoor pricing formula.
Not necessarily. Their contribution depends on market response, not an assumption that construction cost equals added value.
Yes. The example addendum discussed caps the buyer’s obligation at a stated maximum and prevents payment from exceeding the purchase price; the executed agreement controls the transaction.
The example addendum provides a negotiation period, then termination and return of the deposit if no agreement is reached. Those remedies are not automatic in every Florida transaction.
No automatic delay right is established here. Ask counsel to review the executed contract and confirm relevant requirements with the lender and insurance adviser.