For a family office considering a Manhattan-to-Key Biscayne move, ownership planning should begin before acquisition. U.S. tax classification, FIRPTA withholding, entity reporting, and future resale liquidity deserve the same attention as the residence itself.
For a family office contemplating a move from Manhattan to Key Biscayne, the residence is only part of the decision. Equally consequential is who will own it, in what capacity, and with what obligations when the family eventually sells. This is a planning scenario, not an account of a particular relocation or transaction.
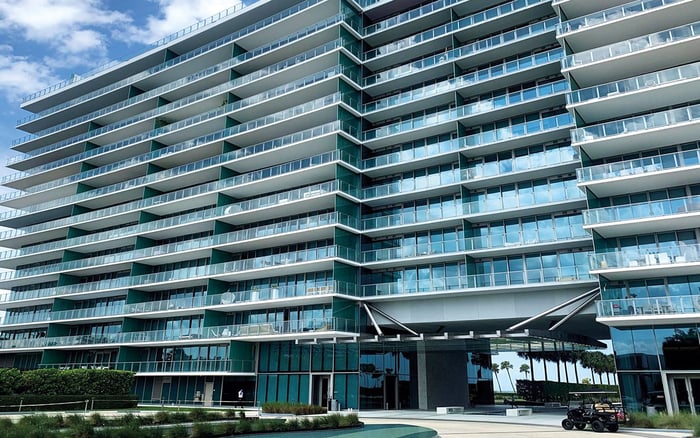
A residence at Oceana Key Biscayne can anchor the property discussion, but ownership planning belongs on a separate track. Neither a Manhattan mailing address nor a Florida residence settles the owner's U.S. tax classification. Foreign nationality alone is also insufficient. The intended owner needs a documented analysis, not an assumption drawn from the family's lifestyle.
The guiding principle is simple: design the acquisition with the exit in mind. That does not mean allowing tax considerations to dictate every residential preference. It means understanding the future cash-flow and documentation consequences before selecting the ownership vehicle.
Engage U.S. tax counsel before acquisition, coordinating international-tax, real-estate, and estate-planning advice around the same ownership proposal. Counsel should identify the intended owner, determine the relevant classification, and explain its implications for both ongoing compliance and an eventual disposition.
FIRPTA generally requires withholding when a foreign person disposes of a U.S. real-property interest. Foreign individuals, corporations, partnerships, trusts, and estates can fall within its foreign-person rules. The analysis therefore extends beyond the nationality of the family member who will occupy the residence.
For a disregarded entity, the entity itself is not treated as the seller for FIRPTA purposes; its owner's status determines whether the transferor is foreign. A domestic LLC address does not establish that the owner is a U.S. person.
Where appropriate, a qualifying non-foreign certification can establish that withholding is unnecessary. Informal assurances about where the seller lives or an entity conducts business do not replace the required documentation.
The standard FIRPTA withholding rate is generally 15% of the amount realized, not 15% of the seller's profit. Amount realized generally includes cash paid, the fair market value of other property transferred, and liabilities assumed by the buyer or to which the property remains subject.
That distinction matters when estimating sale proceeds. A family office should not calculate potential withholding by simply applying 15% to its expected gain, or assume that mortgage repayment makes net cash proceeds the relevant base.
Withholding is a collection mechanism, not necessarily the seller's final tax liability. Excess withholding may be recovered through the appropriate U.S. tax return. A potential recovery later, however, is not the same as having those funds available at closing.
The buyer generally acts as the withholding agent and can be liable if required withholding is not collected. Seller-status documentation therefore matters to both sides of the transaction; it is not merely an internal concern for the selling family.
Residential use can affect withholding, but the thresholds are specific. A qualifying purchase for residential use can be exempt when the amount realized is $300,000 or less. Above $300,000 and up to $1 million, a qualifying residential purchase generally receives a 10% rate rather than 15%.
Above $1 million, the residential-use provision does not reduce the standard 15% rate, although another exception or withholding-certificate relief may apply. The buyer's intention to live in the property is not, by itself, a reason to disregard withholding on a higher-value transaction.
Whether the family's search remains in Key Biscayne or includes Park Grove Coconut Grove in Coconut Grove, the planning question is the same: what rules apply to this seller and this transaction? A residential setting does not replace the federal tax analysis.
A U.S. corporation or partnership is not a blanket withholding solution. Domestic entities can have separate withholding obligations involving foreign owners. Certain interests in property-owning corporations can also constitute U.S. real-property interests, so selling ownership interests instead of the residence is not automatically outside FIRPTA.
A foreign-owned U.S. disregarded entity brings another compliance consideration. Such an entity is a domestic disregarded entity wholly owned by a foreign person and generally must file Form 5472 when it has reportable transactions with related parties. When required, that filing generally accompanies a pro forma Form 1120, despite the entity otherwise being disregarded for income-tax purposes.
Reportable transactions can include contributions, distributions, and amounts connected with formation, acquisition, or dissolution. Holding a residence without operating income should not be taken to mean that the entity has no reporting obligations.
For a family also considering Una Residences Brickell in Brickell, the same ownership questions deserve attention before the property choice becomes final. Counsel should compare structures by their actual consequences, not the appeal of an entity label.
A disciplined family office should preserve ownership records, seller-status documentation, basis support, and the information needed for estimated-gain calculations. Maintaining that file from acquisition makes future withholding and certificate planning more orderly.
Before a sale, counsel should review whether a withholding certificate could reduce or eliminate withholding. The IRS can issue one when the required collection would exceed the seller's anticipated tax liability or other qualifying circumstances apply. Relief should be evaluated, not presumed.
Timing matters. A withholding-certificate application submitted by the transfer date can alter the remittance deadline. Consider it alongside the closing schedule and the family's intended use of proceeds.
The withholding agent generally files Form 8288, submits Form 8288-A, and remits withholding within 20 days after the transfer, subject to applicable exceptions. Assign responsibility for these steps before closing rather than leaving the parties to resolve them afterward.
The objective is a residence that serves the family, supported by an ownership arrangement its advisers can explain and administer. Neither the property's location nor the family's move alone supports a universal recommendation on structure.
Key Biscayne-specific transfer taxes, Florida homestead eligibility, lender-consent requirements, and the estate-tax outcome of a particular structure require separate review. A FIRPTA plan is not a conclusion on those questions.
For a discreet conversation about your South Florida residential search, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. A relocation or mailing address does not itself settle the intended owner's U.S. tax classification, which should be reviewed by U.S. tax counsel.
FIRPTA generally requires withholding when a foreign person disposes of a U.S. real-property interest. The eventual seller's tax status is central to the analysis.
No. The standard rate generally applies to the amount realized, which can include cash, other property transferred, and certain liabilities.
The buyer generally acts as the withholding agent. The buyer can be liable if required withholding is not collected.
No. For FIRPTA purposes, the disregarded entity is not treated as the seller; its owner's status determines whether the transferor is foreign.
Qualifying residential purchases can be exempt at $300,000 or less and generally receive a 10% rate above $300,000 through $1 million. Above $1 million, residential use does not reduce the standard 15% rate.
No. It is a collection mechanism, and excess withholding may be recovered through the appropriate U.S. tax return.
The IRS can issue a certificate reducing or eliminating withholding in qualifying circumstances. An application submitted by the transfer date can alter the remittance deadline.
The withholding agent generally files Form 8288, submits Form 8288-A, and remits withholding within 20 days after transfer, subject to applicable exceptions.
Yes. Reportable related-party transactions can include contributions, distributions, and formation or acquisition amounts, potentially requiring Form 5472 attached to a pro forma Form 1120.