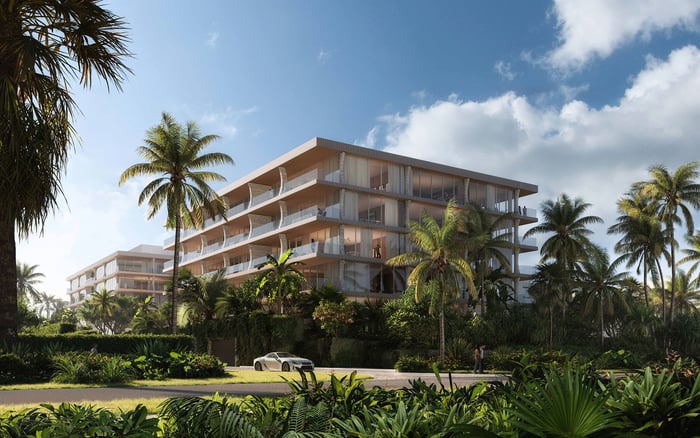
For a Houston family establishing a Palm Beach home, the purchase is only one part of the transition. Domicile, deed vesting, homestead restrictions, fiduciary authority, insurance review, and succession documents deserve a coordinated Texas and Florida legal review.
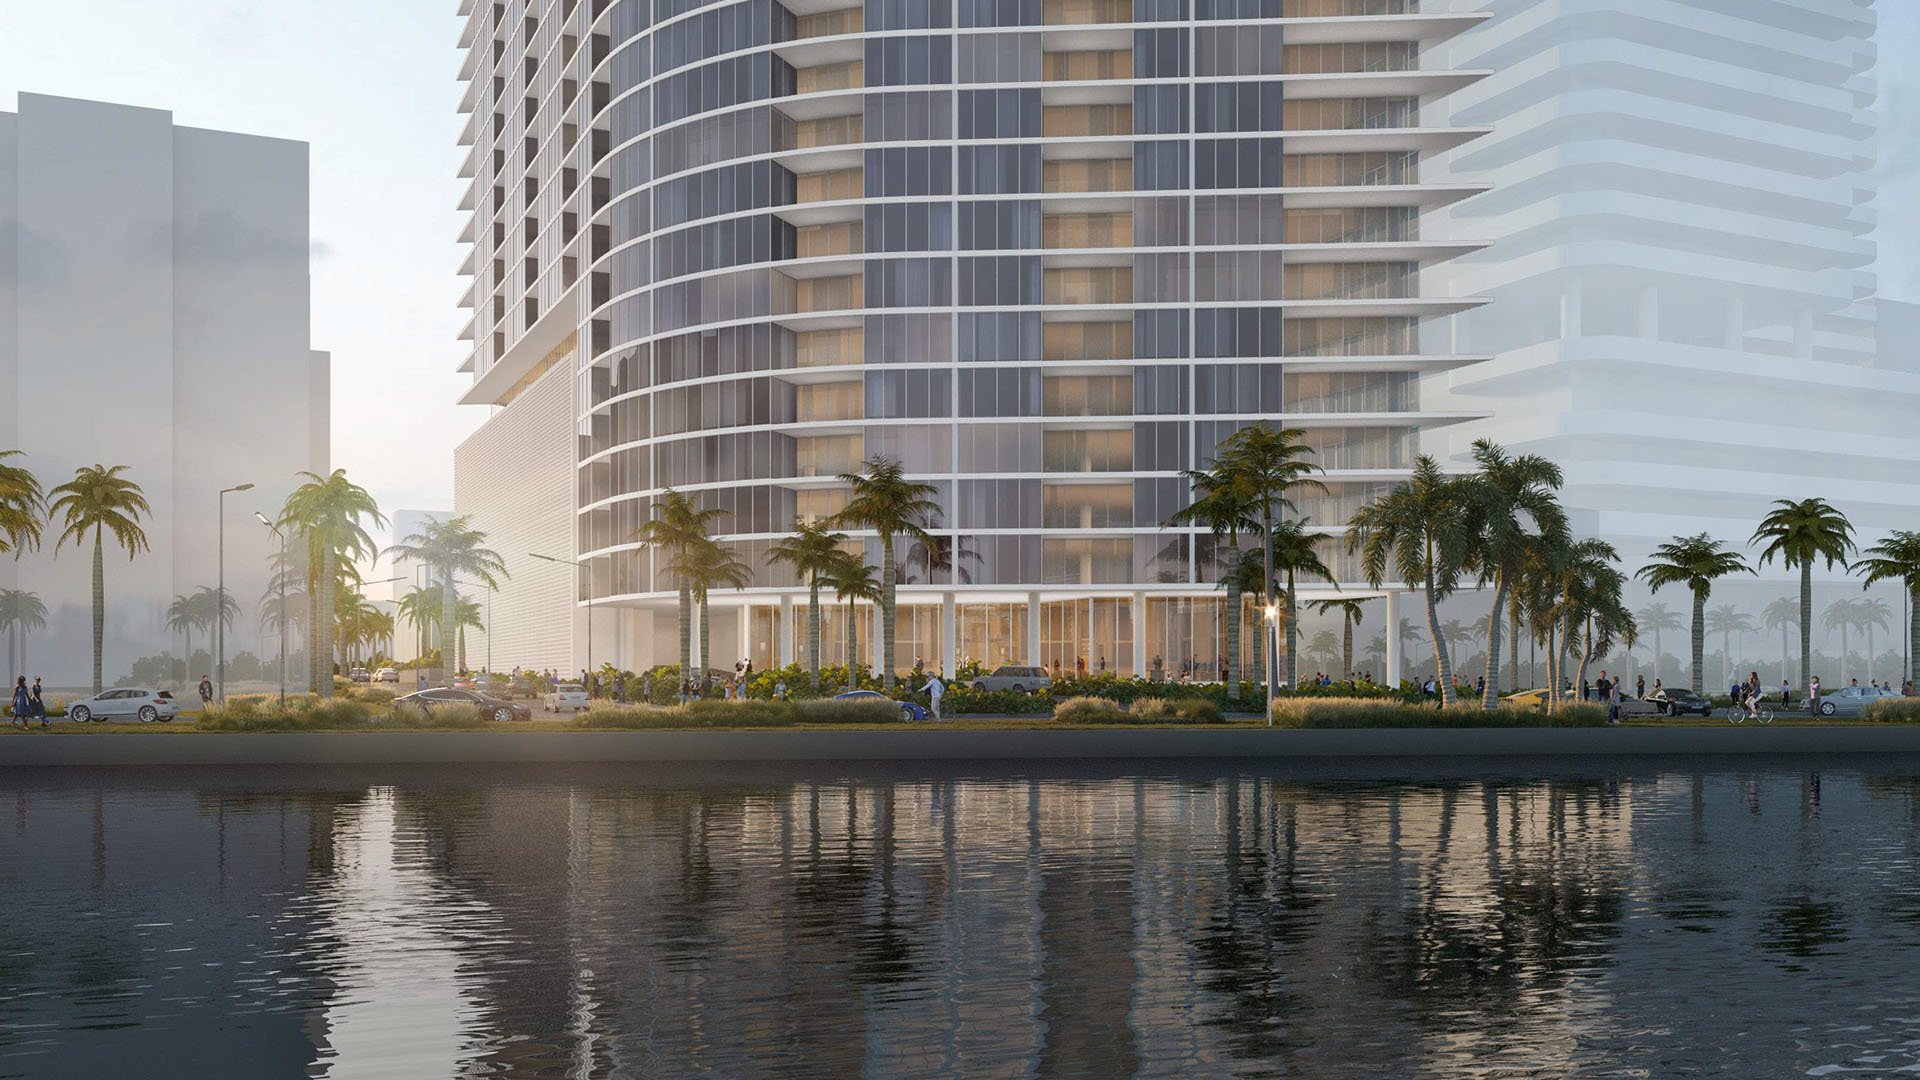
For a Houston family establishing a home in Palm Beach, selecting the residence is the visible part of a more consequential transition. The quieter work is aligning domicile, ownership, trust instructions, and decision-making authority. A beautifully chosen property should not leave the family office uncertain about who can act during incapacity or who receives the home at death.
Whether the search centers on Palm Beach Residences or a home in West Palm Beach, the planning principle is the same: review the acquisition and the estate structure together. Moving does not automatically invalidate documents created in Texas, but continuing validity is not the same as suitability for Florida.
The objective is continuity, not wholesale replacement. Texas and Florida counsel should identify what can remain, what needs revision, and which decisions require coordination with the trustee, CPA, wealth manager, title company, and insurance broker.
Residence and domicile are different concepts. A person may maintain several residences but has only one domicile: the fixed, permanent home to which that person intends to return. Buying a Florida property does not, by itself, resolve that distinction.
For a family retaining meaningful Houston connections, the practical task is consistency. Driver’s licenses, voter registration, vehicle records, tax filings, and estate-planning documents should reflect the intended Florida domicile. Counsel should review these records alongside the family’s actual intentions, rather than treating any single document as conclusive.
A purchase at Alba West Palm Beach belongs within that broader review without implying anything about a particular buyer’s legal status. The property decision and the domicile decision are related, but not interchangeable.
The family office should also distinguish an individual’s domicile from the office’s own relocation arrangements. The estate review concerns the people, property, and documents involved-not simply the address used for administration.
A Texas will or trust may remain legally valid after a Florida move. Even so, state-specific differences warrant a coordinated review of governing-law provisions, fiduciary appointments, execution requirements, and references to former-state property or institutions.
Read the documents together rather than approving each in isolation. A trust’s instructions, a will’s disposition, and a power of attorney’s delegation should be evaluated against the family’s intended arrangements for the Florida residence. The question is not merely whether a document survives the move, but whether it supports the intended outcome.
For the family office, a useful planning agenda identifies the documents requiring legal review and the institutions expected to rely on them. That focuses the conversation on authority and implementation without presuming that every instrument needs to be rewritten.
Deed vesting deserves legal attention alongside the estate documents. Do not assume that placing a residence in a trust settles how it will pass at death. Florida’s homestead-devise restrictions can limit the result even when the trust’s instructions appear explicit.
A surviving spouse or minor child can constrain disposition of the homestead. If a trust’s devise violates the constitutional limitations, title passes at death under Florida’s statutory homestead succession rules rather than following the conflicting trust direction.
For a buyer evaluating Forté on Flagler West Palm Beach, the question is not which ownership structure sounds most sophisticated. It is whether counsel has reconciled the proposed vesting, intended use, family circumstances, and succession provisions.
No single vesting recommendation fits every household. The title company and legal advisers should address the proposed deed together; neither an entity label nor a trust designation should substitute for individualized analysis.
Homestead is not a single, undifferentiated protection. Restrictions on disposition at death, creditor protection, and property-tax exemptions involve distinct questions. A conclusion about one should not be treated as a conclusion about all three.
Trust language also requires careful interpretation. A general direction to pay debts, expenses, and claims, or a power of sale, does not by itself subject protected homestead to those claims. Broad administrative language should not automatically be read as surrendering that protection.
A specific sale direction raises a different issue. If otherwise protected homestead is outside the constitutional devise limitations and the trust directs its sale, title may remain vested in the trustee under the trust terms. The distinction between general administrative authority and a directed sale matters when counsel evaluates what happens after death.
These are questions for document-specific review, not assurances that a particular residence or ownership arrangement qualifies for every homestead benefit.
Successor-trustee provisions should be tested against the family’s intended administration. Confirm who acts after incapacity, how co-trustees exercise authority, and how a successor or corporate trustee is appointed and recognized. Naming a successor is only part of the review; the mechanics of assuming and exercising authority deserve equal attention.
Powers of attorney require a parallel examination. Legal validity alone may not ensure practical acceptance. Review Florida compatibility and the requirements of the institutions expected to rely on the document.
Refresh health-care planning at the same time. Health-care surrogate designations, living wills, HIPAA authorizations, and related instructions should be reviewed for use in Florida. Financial succession and medical decision-making are separate responsibilities, but both should reflect the family’s intended decision-makers.
Insurance belongs in the relocation discussion, but coverage decisions should remain specific to the family and property. Include the insurance broker in the same review as counsel, the trustee, and the title company, rather than treating coverage as unrelated to ownership and administration.
A family considering Mr. C Residences West Palm Beach should bring its proposed ownership and intended use into that conversation. Those are matters for discussion, not grounds for assuming a particular policy requirement, coverage outcome, or premium.
The disciplined approach is to obtain individualized advice. The estate plan should not stand in for an insurance assessment, nor should an insurance assessment stand in for legal review.
If Florida remains a second home rather than the intended domicile, make that distinction explicit in the planning discussion. If the move is intended to establish Florida domicile, align the records and estate review accordingly.
Before treating the transition as complete, bring the advisers together to address the unresolved decisions: domicile consistency, proposed deed vesting, homestead succession, trustee authority, powers of attorney, health-care instructions, and insurance review. The aim is a coherent arrangement that supports the family’s wishes without overlooking state-specific constraints.
Explore your next South Florida residence with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNot by itself. Domicile is the fixed, permanent home to which a person intends to return, and personal records should consistently reflect that intention.
A person may maintain multiple residences but has only one domicile. The estate review should distinguish a second home from an intended change of domicile.
Relocation does not automatically invalidate the plan. Texas documents may remain legally valid but still need review for Florida-specific differences.
Review governing-law provisions, fiduciary appointments, execution requirements, and references to former-state property or institutions. Evaluate the documents together rather than in isolation.
No. If a trust’s devise violates the constitutional limitations, title passes at death under Florida’s statutory homestead succession rules.
A surviving spouse or minor child can constrain homestead disposition. A will or trust may not control the residence as drafted if its provisions conflict with Florida’s restrictions.
A general direction to pay debts, expenses, and claims, or a power of sale, does not by itself subject protected homestead to those claims. A specific direction to sell requires separate analysis.
Confirm who acts after incapacity, how co-trustees exercise authority, and how successor or corporate trustees are appointed and recognized.
Yes. Review powers of attorney for Florida compatibility and practical institutional acceptance, alongside health-care surrogate designations, living wills, HIPAA authorizations, and related instructions.
Florida and Texas counsel should coordinate with the trustee, CPA, insurance broker, title company, and wealth manager. Insurance and ownership decisions require individualized review rather than a universal recommendation.