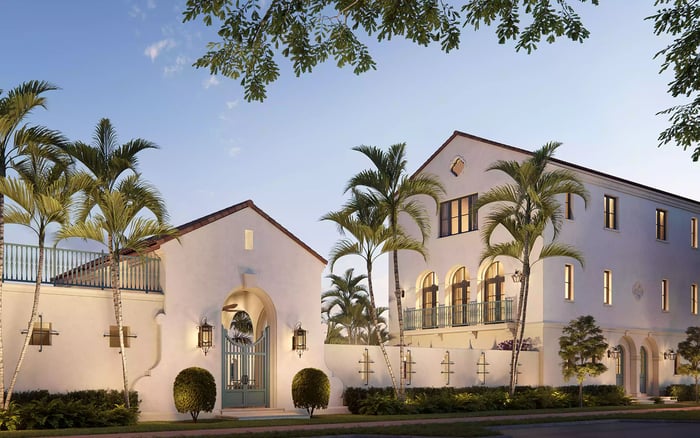
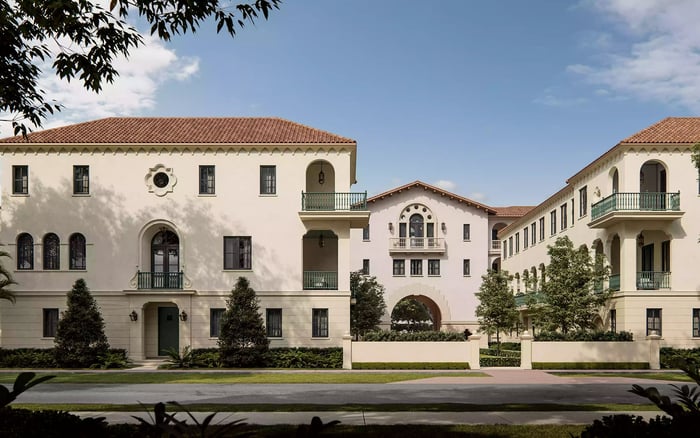
A Sydney-to-Coral Gables move deserves two coordinated plans: one for the life a family wants to build, another for the cross-border tax decisions that shape its first year. Travel records, the Sydney home and asset timing belong in a shared adviser conversation before departure.
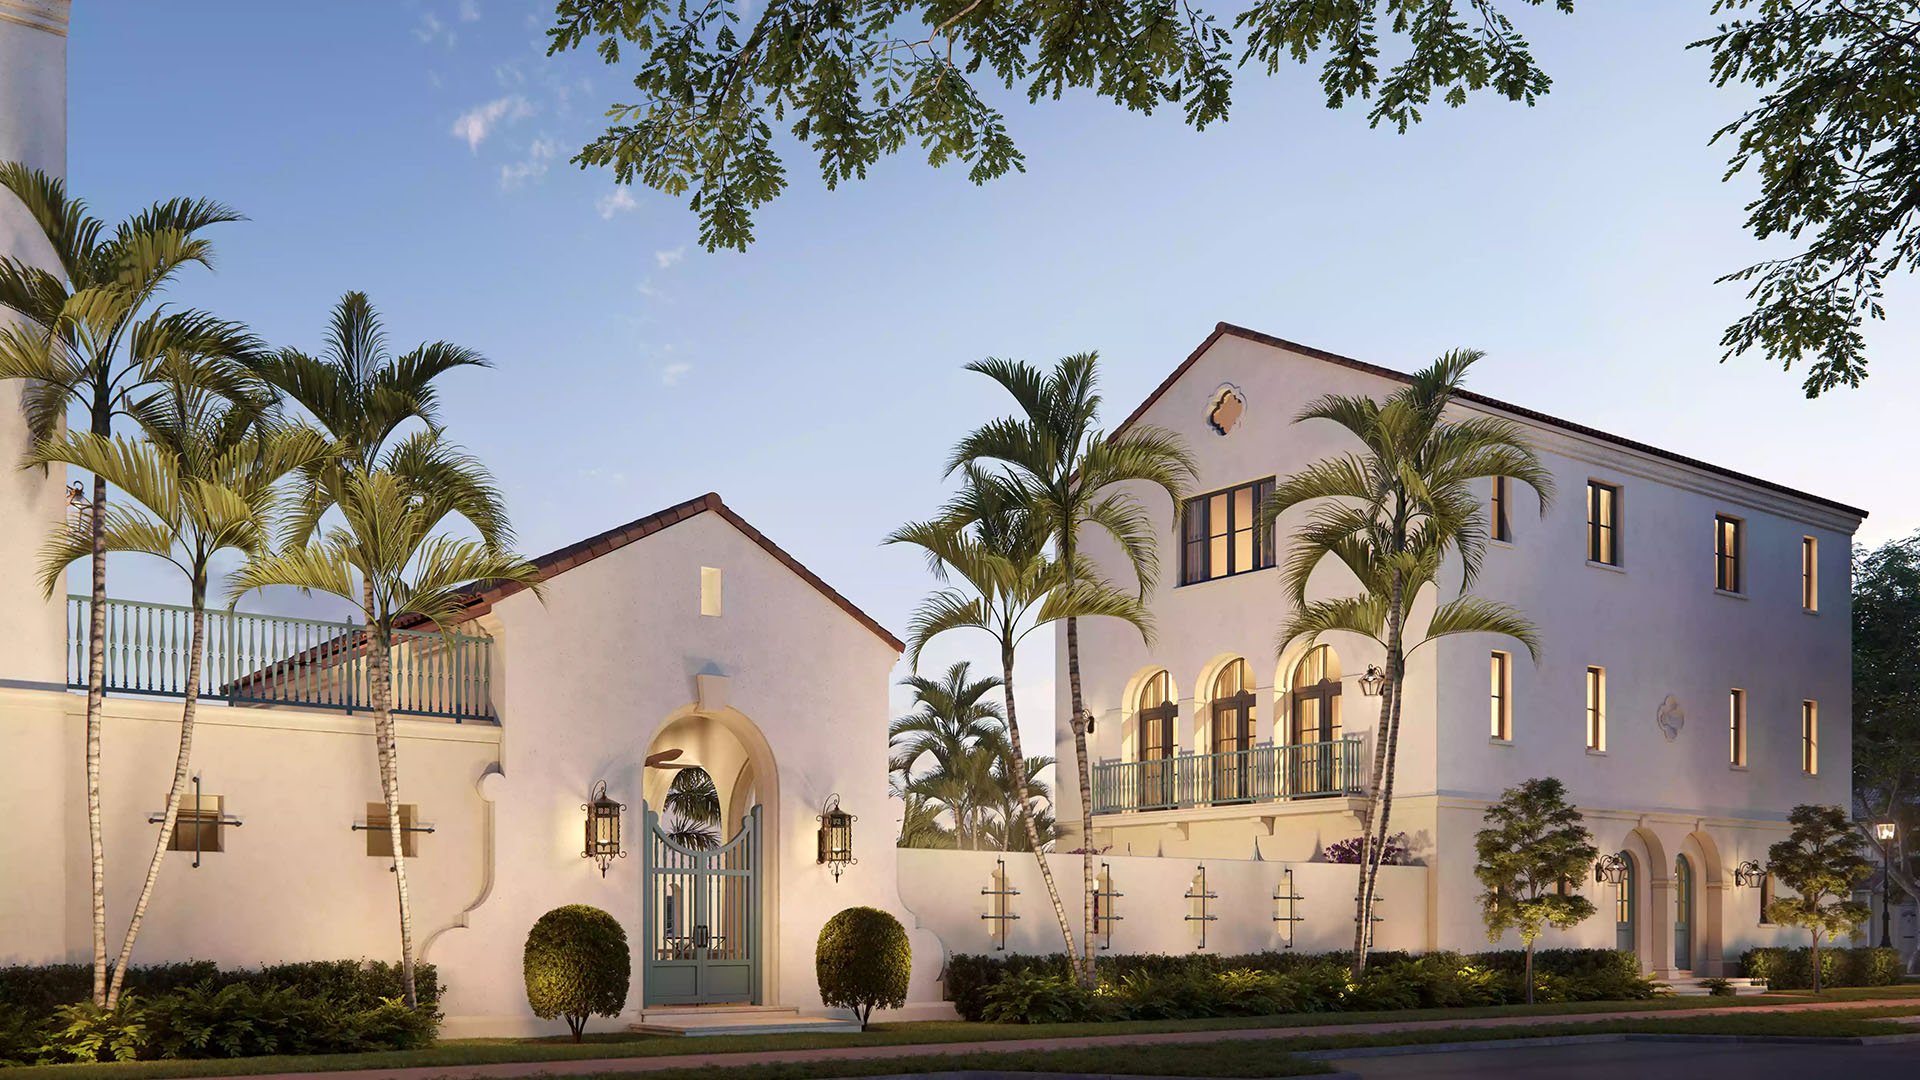
Relocating from Sydney to Coral Gables begins with how a household wants to live: where family routines will settle, how business commitments will work and what kind of residence will feel right beyond the first season. Tax coordination should protect that decision, not substitute for it.
A buyer considering The Village at Coral Gables should begin with a personal brief: space, privacy, visiting family, working from home and the intended duration of the move. Those priorities belong beside the financial analysis, not beneath it. The right residence must work on an ordinary Tuesday, not merely on a tax spreadsheet.
The first-year challenge is that travel, tax residency, property ownership and asset transactions can follow different timelines. Australian and U.S. advisers should reconcile them before the household makes decisions that are difficult to reverse.
For a non-U.S. citizen, U.S. resident-alien status generally arises through either the green-card test or the substantial presence test, subject to exceptions. Under substantial presence, the calculation requires at least 31 U.S. days in the current year and 183 weighted days across three years.
The weighting counts all current-year days, one-third of the preceding year's days and one-sixth of the second preceding year's days. Counting only from the permanent relocation date can therefore miss earlier visits that matter.
Ask the U.S. adviser to review a day-by-day travel history, including property-search trips and business visits. For someone becoming resident under substantial presence, the residency starting date is generally the first U.S. day in the qualifying year, subject to exceptions-not necessarily the day the family permanently arrives.
That distinction can change which income falls within the resident period. A midyear change can also create a dual-status tax year, with different rules for resident and nonresident periods. The practical objective is a written timeline before planned transactions proceed.
Australian tax residency is separate from immigration status or the physical act of moving overseas. Departure alone should not be assumed to establish the tax outcome.
Australian tax residents generally declare worldwide income, including foreign income earned while living overseas. Australian foreign residents generally declare Australian-source income, including rental income and capital gains on taxable Australian property. U.S. resident aliens, meanwhile, generally face federal income tax on worldwide income.
Both adviser teams therefore need the same account of the household's circumstances, not two independently assembled versions. Ask each team to explain its domestic residency position, the dates it considers relevant and where further analysis is required.
For the buyer evaluating Ponce Park Coral Gables, the purchase decision and the residency analysis should inform each other while remaining distinct. Selecting a residence does not, by itself, resolve the cross-border tax position.
Keeping a Sydney residence while establishing a Coral Gables home may preserve flexibility. It can also require closer treaty analysis if both countries treat the individual as resident under their domestic rules.
The Australia-U.S. income-tax treaty contains individual residence tie-breakers that consider permanent home, then habitual abode, then the country with which personal and economic relations are closer. If homes remain available in both countries, the permanent-home criterion may not settle the question.
That is a reason to document actual living arrangements and have both advisers assess the same facts-not to select a property merely to support a preferred tax narrative.
Treaty residence should not be confused with an automatic release from domestic reporting. Mechanisms to relieve double taxation depend on the relevant treaty provisions and applicable tax-credit rules; they do not simply erase liability in one country.
The Sydney property deserves a separate decision meeting. Keeping it available, renting it or selling it can serve different family and investment objectives. Understand the tax implications before committing.
Retaining and renting the home can leave Australian rental-income reporting obligations after Australian tax residency ends. If the owner is also a U.S. resident alien, the general U.S. worldwide-income rules make that rental income relevant to the U.S. analysis too. Both teams should review how any double-tax relief applies.
A proposed sale requires particular care. Foreign residents selling Australian residential property generally cannot claim the main-residence capital-gains exemption unless a limited exception applies. Review the proposed sale before changing residency, not only before settlement.
Foreign-resident capital-gains withholding may also apply. Clearance certificates are relevant to eligible Australian-resident sellers; they are not a universal solution for foreign residents. Ask the Australian adviser to distinguish the potential tax liability from any withholding that may affect the transaction's proceeds.
Ceasing Australian tax residency can trigger a deemed disposal of certain assets that are not taxable Australian property, even when no actual sale occurs. A plan focused exclusively on the two homes may therefore overlook a material departure issue.
Before departure, have both adviser teams reconcile asset classifications, supporting valuations and planned disposals. Australian foreign residents are generally subject to Australian capital-gains tax only on taxable Australian property, including Australian real estate and certain business assets. The residency transition itself, however, requires separate attention.
The objective is not a blanket instruction to sell or retain. It is to understand each proposed action before it becomes irreversible.
Return to the residence brief once the technical issues are mapped. A household considering Cora Merrick Park should still test its choice against daily routines, space requirements and longer-term intentions. Would the residence remain attractive without the hoped-for tax outcome?
For the first year, maintain one shared record of travel, income, Sydney rental activity, asset transactions and supporting valuations. Update both adviser teams when plans change, especially before a disposal or a decision about the Sydney home. A shared record gives each team a consistent basis for its work.
Treat this framework as general information, not individualized tax advice. Qualified Australian and U.S. advisers should establish the household's specific position. Their role is to make the consequences clear so the family can choose its home with confidence.
For a residence search shaped around your family's priorities, explore Coral Gables with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. Australian tax residency is distinct from immigration status, and the physical move alone does not establish the tax outcome.
It generally requires at least 31 U.S. days in the current year and 183 weighted days across three years. The weighting includes all current-year days, one-third of the preceding year's days and one-sixth of the second preceding year's days.
Yes. U.S. visits before permanent relocation can affect the substantial-presence calculation, so advisers should review a day-by-day travel record.
No. Under substantial presence, the starting date is generally the first U.S. day in the qualifying year, subject to exceptions.
A midyear change in U.S. tax residency can create a year with resident and nonresident periods. Different tax rules apply to those periods.
Yes. Australian foreign residents generally must declare Australian-source rental income, even after Australian tax residency ends.
Foreign residents selling Australian residential property generally cannot claim the main-residence capital-gains exemption unless a limited exception applies. Reviewing the sale beforehand helps clarify the potential consequences.
Yes. Ceasing Australian tax residency can trigger a deemed disposal of certain assets that are not taxable Australian property.
No. Relief depends on the relevant treaty provisions and applicable tax-credit rules, and treaty residence is not an automatic exemption from domestic reporting.
Maintain a shared record of travel, income, rental activity, asset transactions and supporting valuations. Both teams should reconcile residency positions and review planned disposals before action is taken.