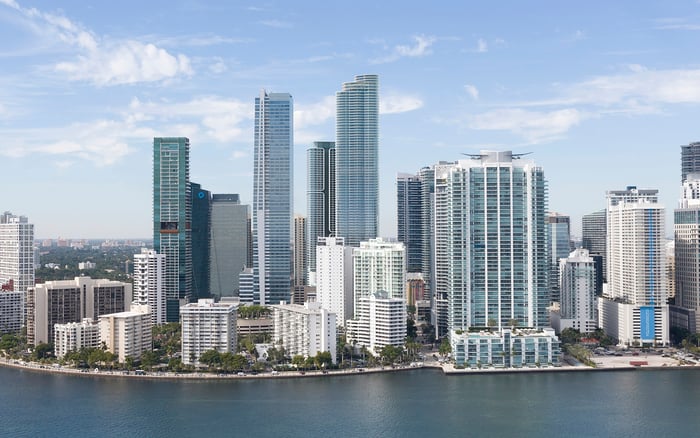
A Los Angeles-to-Brickell relocation calls for more than a property purchase. Consistent residency records, carefully defined decision-making authority, contract-specific closing preparation, and considered vendor oversight can help a family office organize the first year without confusing internal policy with legal requirements.

A move from Los Angeles to Brickell can begin with a residence, but its administrative foundation rests on everyday decisions: which home the family actually occupies, which address appears on financial records, and who can authorize the next commitment. For a household supported by a family office, the first year deserves the same attention as the acquisition itself.
Establishing Florida domicile requires evidence of an actual move. A forwarding address is insufficient, and buying a condominium does not automatically establish homestead eligibility. The task is to align the family's lived circumstances with its records while distinguishing legal requirements from optional family-office procedures.
Whether considering 2200 Brickell or another residence, buyers should separate three questions: where they will live, how the purchase will close, and how the household will operate afterward. Answering one does not resolve the others.
A family-office approval framework can be useful, but it is a chosen governance tool, not a Florida relocation requirement. The family might assign different decision-makers to property commitments, moving expenses, furnishing purchases, and recurring household services. Spending thresholds should reflect the family's arrangements, not a presumed industry standard.
The essential distinction is between permission to spend and authority to bind the buyer. Internal approval does not, by itself, establish that the person giving it can sign purchase documents. Before commitments are made, counsel should confirm who may sign for the intended purchaser and what documentation the closing team will need.
For a purchase under consideration at Cipriani Residences Brickell, the office could maintain a concise decision record identifying the proposed purchaser, responsible adviser, authorized signatory, and person approving funds. This is an organizational recommendation, not a statement about the project's procedures. The buyer's own documents must govern.
The most useful relocation file connects the home occupied with the records generated by living there. Retain the deed or lease, moving records, utility information, and insurance documentation. These materials help document the transition, not merely the intention to relocate.
Consistency matters across housing, driver licensing, vehicle registration, financial accounts, utilities, insurance, and tax records. Updating addresses with financial institutions, insurers, creditors, and government agencies helps align administrative records with the move. A family office can coordinate those updates, but each entry should accurately reflect the family's circumstances.
A sworn Declaration of Domicile can document the move. It remains one piece of evidence, not a substitute for actual residence or consistent records. Likewise, assembling Florida documentation does not establish that California tax residency has ended. That question requires separate advice tailored to the family's circumstances.
As an optional organizational practice, keep a dated index showing what changed, when it changed, and where the supporting document is stored. An index makes the file easier for advisers to review; it does not itself prove domicile.
Collecting records and deciding how long to retain them are separate tasks. Keeping documents that demonstrate residence supports the relocation file, but does not establish a universal family-office retention schedule. Avoid assigning a single destruction date to every category of material.
Instead, ask legal and tax advisers to define appropriate retention periods for ownership documents, executed agreements, residency evidence, financial records, and vendor paperwork. The office can then assign responsibility for maintaining the archive and controlling access. These are recommended administrative choices, not stated statutory obligations.
For a family evaluating The Residences at 1428 Brickell, the same distinction applies: a property-selection file serves a different purpose from evidence of the home actually occupied. Keeping those categories separate can help prevent a reservation, purchase agreement, or future housing plan from being mistaken for proof of present residence.
Closing readiness should begin with the buyer's executed agreement, not assumptions about Brickell transactions. Ask counsel to review who may schedule the closing, how notice must be delivered, and which conditions must be satisfied before the buyer is required to close.
Treat notice periods and closing conditions as contract-specific. Do not apply a deadline from another transaction to any of the residential projects discussed here without reviewing the buyer's own agreement.
For the family office, the planning implication is straightforward: identify who receives notices, who reviews them, who signs, and who approves the release of funds. Consider a backup decision-maker, subject to counsel confirming the necessary authority. If the office chooses to require two approvals for a wire, document that as an internal control, not a legal mandate established here.
Internal procedures should work within contractual deadlines. An elaborate approval process has little practical value if the designated approver is unavailable when a valid notice arrives.
The move-in phase is a natural point to consider household vendor oversight. A family office might choose written scopes of work, named budget approvers, documented payment instructions, and a record of who can authorize changes. These are optional controls to discuss with advisers, not requirements established for every Brickell residence.
When planning a household at Una Residences Brickell, ask the relevant building team about applicable access and move-in procedures rather than assuming them. Separately, decide who within the household may commission work and who reviews invoices. Building permission and family approval answer different questions.
For payment oversight, the office could choose to verify new or changed instructions through an independently established contact channel. Any such practice should be expressly adopted and understood by those using it, not assumed to exist.
Permanent-residence planning should remain distinct from second-home ownership. Florida homestead eligibility depends on qualifying ownership and permanent residence as of January 1. Purchasing a Brickell condominium alone does not establish eligibility. Florida's original application for homestead and related tax exemptions is Form DR-501.
The property appraiser may request evidence of previous out-of-state residency, when it ended, and relinquishment of an out-of-state driver license. Florida identification, vehicle and voter registration, bank statements, the address on the latest federal income-tax return, utility-payment records, and school records can also support the residency review.
An optional first-year review can bring these matters together: confirm that records remain accurate, revisit unresolved signing authority, and check that vendor approvals match the family's intentions. The objective is not paperwork for its own sake, but a home whose administration is as considered as its selection.
Explore your Brickell residential options with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationA purchase alone does not establish domicile. Evidence of an actual move and consistent residency records matters; a forwarding address is insufficient.
No, it can document the move, but it is one piece of evidence rather than a substitute for actual residence and consistent records.
Retain the deed or lease for the home actually occupied, moving records, utilities, and insurance information. Keep supporting address and residency records organized alongside them.
No universal schedule is established here. Legal and tax advisers should help determine appropriate retention periods for each document category.
They should be treated as separate questions. Counsel should confirm who can bind the purchaser and what authority documentation the closing team needs.
Have counsel review the notice provisions and closing conditions in the buyer's executed agreement. Identify who receives notices and ensure internal approvals can meet the contractual deadlines.
They are presented here as an optional internal control, not an established legal requirement. A family office can decide whether to adopt them with its advisers.
Eligibility depends on qualifying ownership and permanent residence as of January 1. A condominium purchase alone does not establish eligibility.
Form DR-501 is Florida's original application for homestead and related tax exemptions. Supporting residency evidence may also be requested.
No, California tax residency requires a separate assessment tailored to the family's circumstances.