A buyer-focused review of Auberge Beach ownership, separating advertised association fees from transaction-specific obligations and outlining questions for insurance, closing reconciliation, and funding readiness.
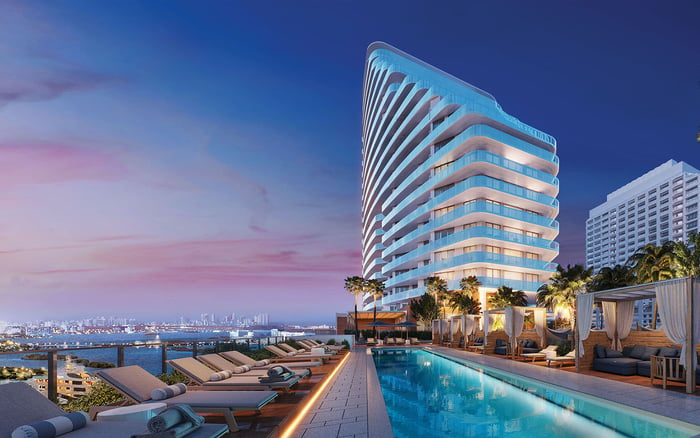
At Auberge Beach Residences & Spa Fort Lauderdale, the ownership conversation should extend beyond the appeal of an oceanfront address. The condominium stands at 2200 N. Ocean Boulevard, Fort Lauderdale, FL 33305. For a prospective purchaser, the more consequential questions concern the recurring budget, the division of insurance responsibility, and the documents supporting the final transfer of funds.
A disciplined purchase review separates three decisions: whether the residence suits the buyer, whether its ownership obligations are acceptable, and whether the closing arrangements are ready. None substitutes for another. An appealing residence does not establish an acceptable insurance position; an agreed purchase price does not establish the final buyer contribution.
The objective is not to complicate ownership. It is to make the obligations clear before they become commitments.
Advertised figures illustrate why unit-specific review matters. Unit S506 lists maintenance of $4,646 per month, while S1406 lists an association fee of $4,969 per month. S1802 and S2301 list association fees of $6,165 and $8,140, respectively. Do not assign those latter figures a payment frequency without confirmation.
Building-wide monthly ranges are less useful for a purchase decision. Two advertised ranges, $1,700-$8,400 and $3,274-$10,148, are not interchangeable with the assessment attached to a particular residence. Nor do advertised figures replace a current association ledger or transaction-specific estoppel certificate.
Request the governing documents, current budget, and reserve study early, ideally before making an offer. Then ask the association or appropriate transaction adviser to confirm the selected unit's assessment, payment frequency, outstanding balance, and any assessment obligations relevant to the purchase. Keep the advertised figure alongside the confirmed figure rather than silently replacing it. The comparison makes unexplained changes easier to identify and discuss.
The listed inclusions provide useful context, but they differ by residence. S1802 identifies common areas, insurance, grounds and structural maintenance, pools, sewer, trash, and water. S1406 also identifies security, gas, and pest control among its inclusions. S506 identifies water and reserve funding, while N404 identifies insurance, exterior maintenance, security, elevators, management, and legal/accounting.
These descriptions should prompt document review, not conclusions about comprehensive protection. The presence of “insurance” in a maintenance description does not establish the scope of the master policy or the terms of an owner's coverage. Similarly, “reserve funding” does not establish the current reserve balance or its adequacy.
Association financials and reserves deserve particular attention in an oceanfront, full-service ownership review. Ask how the current budget addresses those obligations and whether the documents support the recurring cost you intend to underwrite. A service-rich setting still requires a clearly understood operating budget.
Begin with the association's master-policy declarations, deductible schedule, exclusions, and evidence of coverage. Budget separately for owner insurance, obtain quotes early, and check whether the address lies in a FEMA flood zone. An oceanfront location alone does not establish a flood classification or coverage requirement.
For the proposed owner binder, ask the insurance adviser to confirm the insured name, residence identification, effective date, coverage selections, exclusions, deductibles, and premium arrangements. Where financing is involved, ask the lender to identify its transaction-specific insurance requirements in writing. These are review questions, not a statement of binder terms required for every Auberge purchase.
For buyers also considering Four Seasons Hotel & Private Residences Fort Lauderdale, apply the same document-first approach separately. A comparison along Fort Lauderdale Beach should not assume that one property's insurance arrangements describe another's. Compare the responsibility the buyer would actually accept, not simply the insurance language in a marketing description.
Reconciliation should provide a transparent, transaction-specific account of the buyer's contribution. Ask the settlement agent to walk through the purchase price, deposit treatment, any financing contribution, applicable charges, credits, prorations, and association-related amounts. Connect each included line to its supporting document or agreed instruction.
The practical question is simple: can the buyer explain why the final requested amount differs from the earlier estimate? Do not substitute a residence's advertised maintenance figure for the association amount used in the closing calculation. Ask which assessment period and confirmed balance support any association-related adjustment, and have the responsible adviser resolve discrepancies.
If an insurance payment appears in the calculation, ask whether that payment is also being requested separately. If a credit changes, ask who approved it and where the approval is recorded. These are reconciliation prompts, not a prescribed settlement formula. The signed agreement, applicable transaction documents, and professional instructions should control the actual calculation.
Discuss same-day funding as a transaction-specific plan, not an assumed feature of the purchase. Ask the settlement agent and, where applicable, the lender what must happen before funds can be accepted, released, and applied to the closing. Obtain confirmation of relevant timing instructions directly from those parties.
Ask who will confirm receipt, who will communicate unresolved conditions, and how the parties propose to respond if the intended funding sequence cannot be completed that day. Have counsel address the contractual implications of a delay rather than relying on informal assurances of flexibility.
Before acting on payment instructions, ask the settlement agent to confirm its approved verification procedure. Distinguish clearly between the amount the buyer has approved and the instructions for delivering it. The goal is a coordinated decision about readiness, not merely a transfer initiated on the intended date. Do not presume a universal cutoff, guaranteed release time, or automatic extension.
A useful ownership review leaves the buyer with a coherent set of documents: confirmed unit obligations, an understood insurance position, an explained closing amount, and a funding plan agreed with the responsible professionals. Waterfront appeal belongs in the decision, alongside those practical commitments.
If Andare Residences Fort Lauderdale is also on the shortlist, apply the same questions without carrying over Auberge's fee figures or insurance assumptions. Each candidate deserves its own review. For Auberge, the final test is whether the particular residence remains compelling once its ownership obligations and closing arrangements are understood.
For a discreet perspective on your next South Florida residence, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationThe oceanfront condominium is at 2200 N. Ocean Boulevard, Fort Lauderdale, FL 33305.
S506 lists maintenance of $4,646 per month, and S1406 lists an association fee of $4,969 per month. These listing figures are not confirmed closing balances.
No. Confirm the assessment, payment frequency, and relevant balances for the specific residence rather than relying on a building-wide range.
Do not assume it does. Review the master-policy documents with an insurance adviser and budget separately for owner coverage.
Request the master-policy declarations, deductible schedule, exclusions, and evidence of coverage. Use them to discuss the division of responsibility with your insurance adviser.
Ask your adviser to confirm the insured name, residence identification, effective date, coverage selections, deductibles, exclusions, and premium arrangements. Ask any lender to specify its requirements separately.
No flood classification is established here. Check the address's FEMA flood-zone status and discuss the insurance implications with your adviser.
Request the governing documents, current budget, and reserve study, ideally before making an offer. Confirm the selected unit's obligations separately.
Ask the settlement agent to explain each included charge, credit, deposit, and adjustment against the transaction documents. Resolve unexplained differences before approving the final contribution.
Ask the responsible parties to confirm timing instructions, receipt confirmation, unresolved conditions, and the proposed response to a delay. Have counsel address any contract implications.