For Frankfurt buyers establishing a home in Coconut Grove, Florida domicile requires more than ownership or a day count. A disciplined relocation chronology, evidence of permanent residence, and separate cross-border advice help create a coherent supporting file.
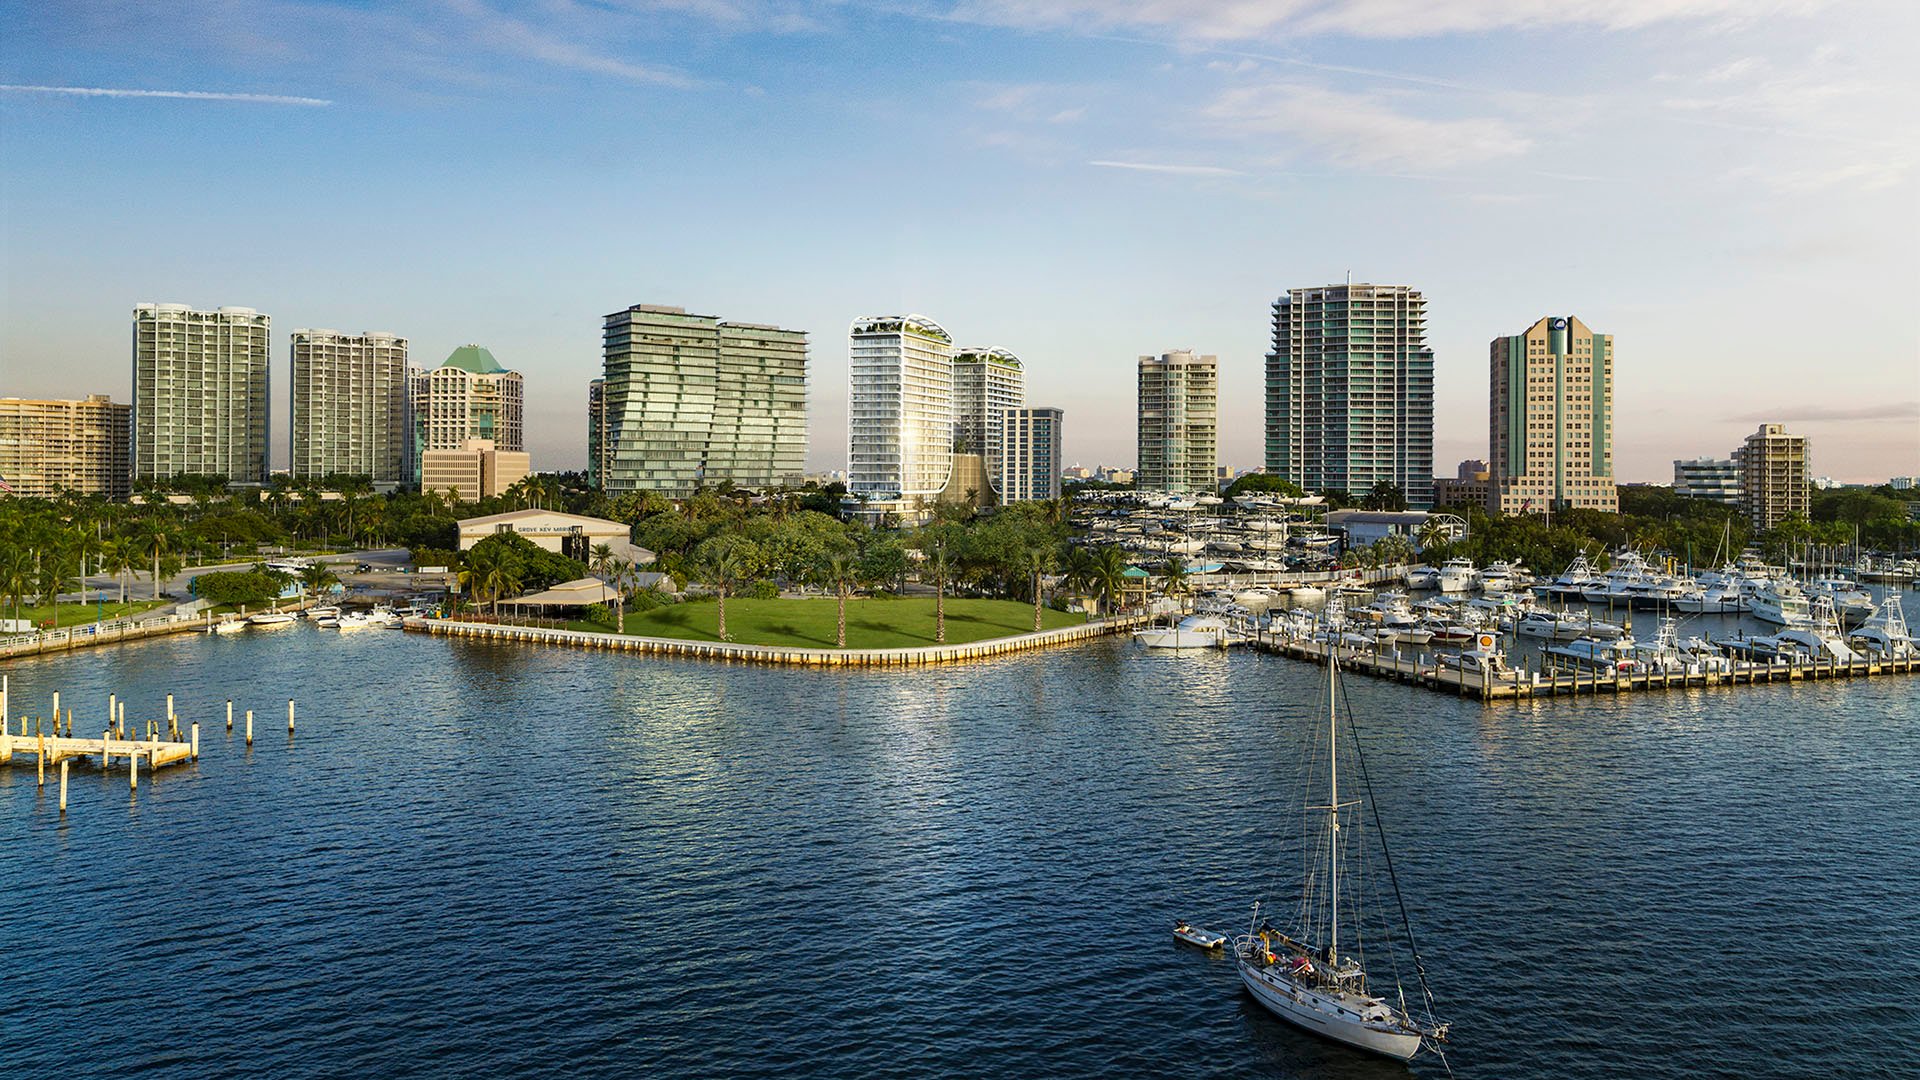
For a buyer moving from Frankfurt to Coconut Grove, choosing a residence is the most tangible decision. Establishing its legal significance deserves equal attention. A purchase can secure a home without establishing Florida domicile, qualifying the property for homestead, or resolving the buyer’s cross-border tax position.
Florida has no individual state income tax and no minimum-day requirement for domicile. Spending 183 days in Florida does not, by itself, establish domicile. The better starting point is whether Coconut Grove has genuinely become the buyer’s principal home, with records that support the transition.
An audit-ready file is a body of organized supporting evidence, not a guarantee of acceptance by every authority. Its purpose is to make the chronology and actual use of the residence clear-not to substitute paperwork for everyday life.
Three distinct questions should guide the purchase. First, has Florida domicile been established? Second, does the property qualify for Florida’s homestead property-tax exemption? Third, what are the buyer’s German and U.S. federal tax positions and immigration eligibility?
Evidence useful for the first two questions does not settle the third. A Florida address, homestead application, or Declaration of Domicile should not be treated as proof that German tax residence has ended. Nor does it resolve U.S. federal tax residence, treaty treatment, or permission to live in the United States.
Before aligning a closing with an intended relocation, obtain coordinated advice on these separate issues. The property search can then follow a considered plan, free of expectations that ownership alone cannot fulfill.
When considering Four Seasons Residences Coconut Grove, the relevant domicile question is not the name on the building. It is whether the particular residence can become the buyer’s actual principal home within the intended timeline.
The same distinction applies to Arbor Coconut Grove. Evaluate the purchase against daily routines, household needs, and the practical ability to establish permanent residence. A purchase commitment and an occupied home are not interchangeable milestones.
Neither a condominium nor a single-family home is inherently stronger proof of domicile. For this purpose, the residence matters through ownership, use, and its connection to the buyer’s life. Architectural preference can remain personal; the supporting record must remain factual.
For a buyer claiming homestead on their own residence, Florida law generally requires legal or beneficial ownership and use as a permanent residence on January 1 of the tax year. In Miami-Dade, buying the property is not enough: it must be the homeowner’s permanent primary residence.
A late-year closing alone therefore does not establish eligibility for the following tax year. Permanent residence must also be established by January 1. Buyers should distinguish the acquisition date from the date the home actually became their permanent residence, rather than assuming both occurred at closing.
That distinction belongs in the relocation chronology. The homestead application asks about previous residency outside Florida and when it ended. Answers should reflect the facts, not a date selected to match a desired exemption year. That entry should not be confused with a determination of when German tax residence ended.
Once Florida domicile has been established, a sworn Declaration of Domicile can serve as evidence through filing with the circuit court clerk in the county of residence. The declaration documents an established position; it should not be treated as creating one regardless of the facts.
For someone maintaining another residence outside Florida, the declaration framework addresses identifying the Florida abode as the predominant and principal home. Retaining a Frankfurt residence therefore calls for careful attention in the file and separate cross-border advice-not silence or an assumption that a Florida filing resolves every consequence.
A practical file can organize relevant evidence into four groups:
Ownership and chronology: ownership documents, closing records, and a factual timeline of establishing permanent residence.
Identification and registration: the Declaration of Domicile, Florida driver license or identification card, and Florida vehicle registration, as applicable.
Address and household records: bank-account registration, utility payments at the residence, and the address on federal income-tax returns where applicable.
Everyday connections: employment location and where dependent children attend school, where relevant.
Voter registration is another residency factor, but it belongs on the checklist only for a buyer eligible to register. No document should be pursued or presented merely to make the file appear more complete.
A contemporaneous day-and-travel log can corroborate actual occupancy. It is supporting evidence, not a substitute for establishing domicile or a universal test of tax residence.
In practice, note locations and travel dates as they occur, and retain corresponding travel documentation. Keep arrival and departure details clear enough for advisers to apply each jurisdiction’s rules. Do not assume every authority uses the same counting convention.
The log should align with the broader relocation chronology. If the file identifies Coconut Grove as the principal home, the travel record should help explain how that home was actually used, including periods abroad. A calendar reconstructed only when questions arise is less useful as a working record than one maintained throughout the move.
For a household considering Park Grove Coconut Grove, the useful exercise is to connect ordinary life to the residence. Where does work take place? Where do dependent children attend school? Which address appears on banking and applicable tax records? These connections are relevant to the permanent-residence assessment.
For buyers exploring The Well Coconut Grove, the principle is unchanged: choose for the life intended, then document the life actually established. Consistency does not mean changing records ahead of the facts. It means maintaining accurate information and a clear explanation of the transition.
Residency documentation should not end with the first application. In Miami-Dade, online homestead applications and a dedicated cancellation process are available for properties that no longer qualify. A reporting channel also exists for potentially improper exemptions, including concerns involving rented properties or homes that are not the owner’s permanent residence.
If the property’s use changes, reassess eligibility rather than assuming an earlier exemption continues unchanged. The strongest approach is straightforward: a residence genuinely used as home, an accurate chronology, and advice that keeps Florida, German, federal, and immigration questions distinct.
For a discreet property search aligned with your relocation priorities, explore Coconut Grove with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. Florida has no minimum-day requirement for domicile, and spending 183 days there does not, by itself, establish it.
No. The property must be the homeowner’s permanent primary residence, and the applicable ownership and eligibility requirements must be met.
For a buyer claiming homestead on their own residence, legal or beneficial ownership and permanent residence generally must exist on January 1 of the tax year.
No. A late-year closing alone is insufficient; permanent residence must also be established by January 1.
It provides sworn evidence of established Florida domicile when filed with the circuit court clerk in the county of residence. It does not substitute for the underlying facts.
Relevant evidence includes bank-account registration, utility payments at the residence, and the address on federal income-tax returns, where applicable.
No. Voter registration belongs in the residency checklist only when the buyer is eligible to register.
A contemporaneous log can corroborate actual occupancy and support a residency examination. It does not independently establish domicile or supply a universal tax-residence threshold.
No. German tax residence, U.S. federal tax status, treaty treatment, and immigration eligibility require separate analysis.
Reassess eligibility and use the dedicated Miami-Dade homestead-cancellation process when appropriate. An earlier exemption should not be assumed to continue unchanged.