A Chicago-to-South Beach move requires more than a new address and a favorable day count. A carefully documented transition, accurate travel calendar, and consistent domicile records can help distinguish a permanent relocation from a seasonal stay, while Illinois-source income requires separate attention.
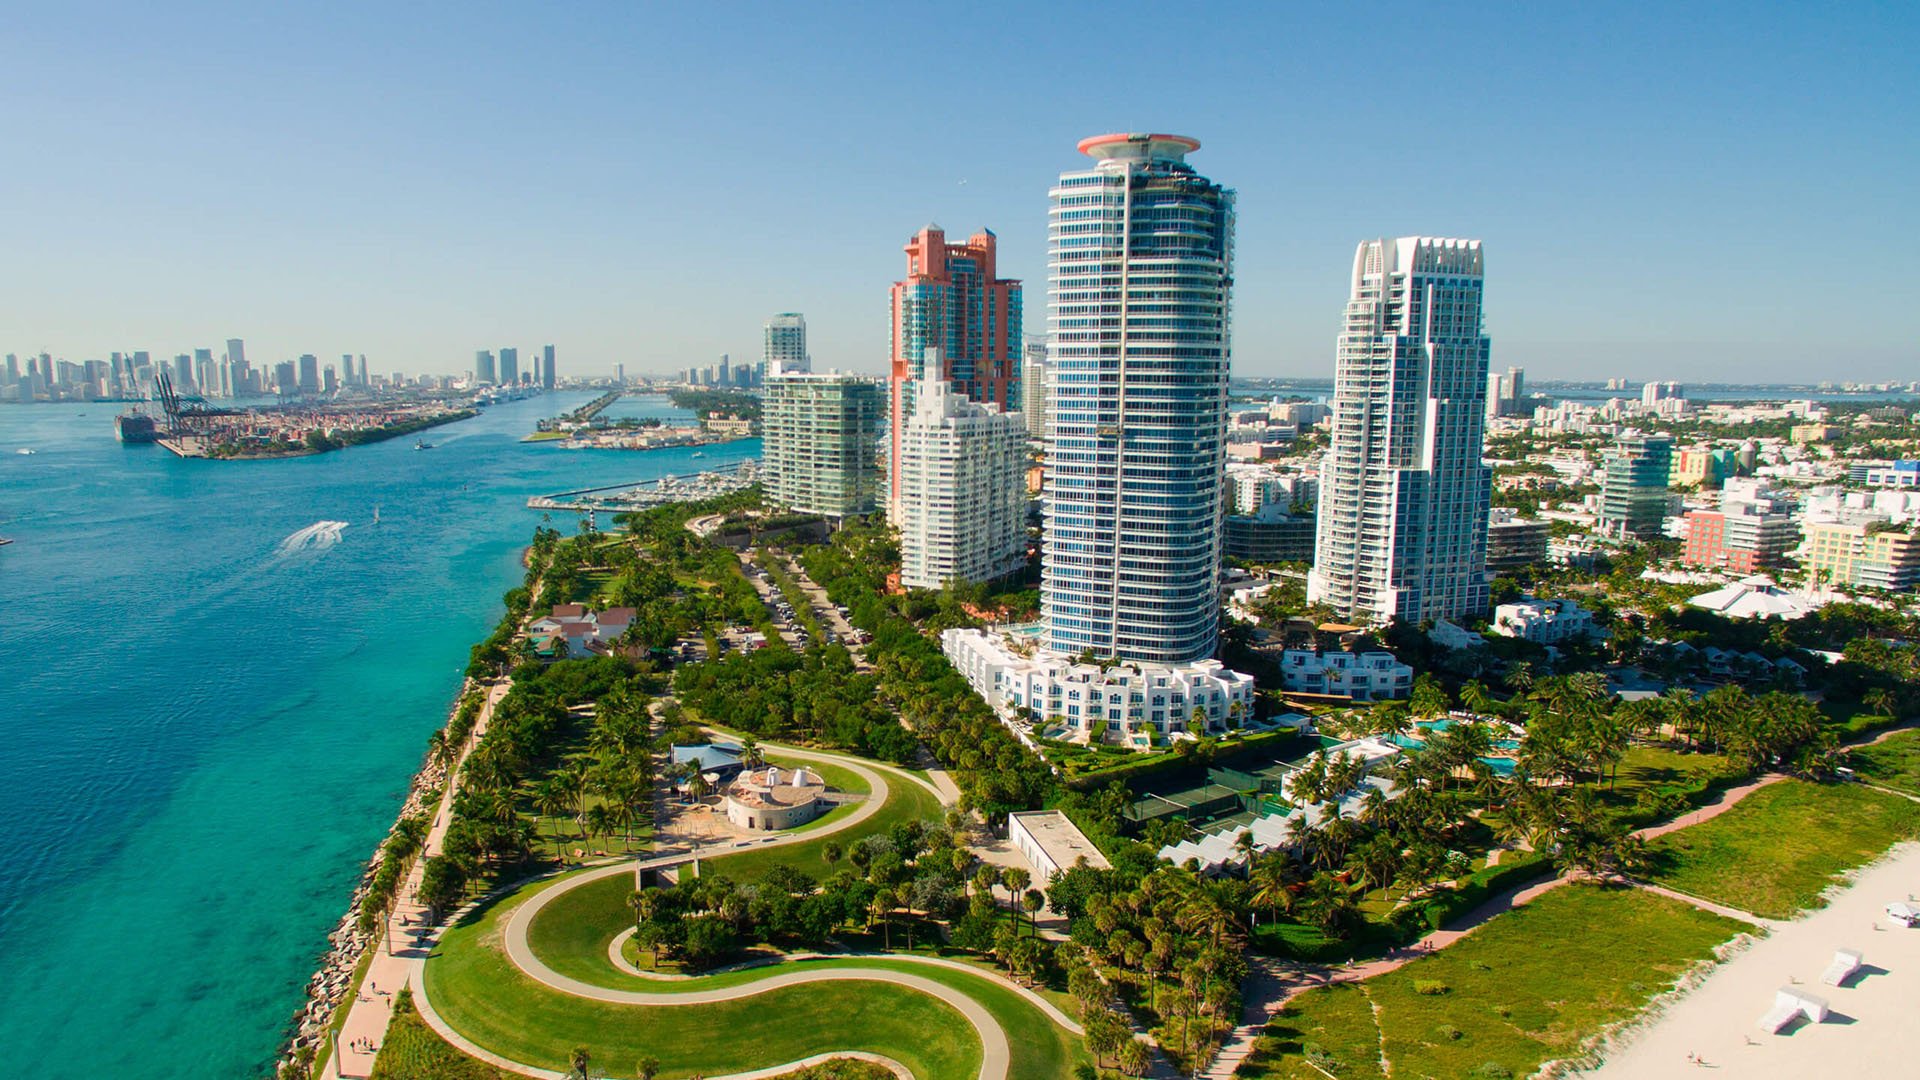
For a Chicago household relocating to South Beach, choosing a residence is only one part of establishing a permanent home. The first year also calls for a coherent account of when the move became permanent, how each property was used, and why travel back to Illinois continued.
Florida imposes no individual state income tax and requires no personal state income-tax return. That advantage does not, by itself, settle whether Illinois continues to treat someone as a resident. Nor does a day count alone resolve Illinois residency.
Whether the search centers on Apogee South Beach or another residence, the essential distinction is between acquiring a Florida property and making Florida the place to which one intends to return after temporary absences. The purchase and the change of domicile are not necessarily the same event.
Illinois defines domicile as the place where a person resides and intends to return after temporary absences. Its definition of a resident includes individuals present in Illinois for a non-temporary purpose, as well as those domiciled there who are absent for a temporary or transitory purpose.
Physically moving to South Beach therefore does not necessarily end Illinois residency if the Florida stay remains temporary and Illinois remains the person's domicile. Changing domicile requires an intention to abandon the former domicile and establish a new one, supported by actual conduct.
Planning around a presumed numerical threshold can be misleading. Time in each state matters, but so do the purpose of each stay and the evidence of where permanent home life is established. The federal substantial-presence test for non-U.S. citizens, which uses a weighted three-year U.S.-presence calculation, addresses a separate question. It is not the Illinois-versus-Florida domicile test.
The first-year file should explain when the South Beach residence became the permanent home-not merely where the household spent the most nights. Illinois distinguishes full-year residents, part-year residents, and nonresidents, making the timing of a genuine change important.
A buyer considering Continuum on South Beach should distinguish the property transaction timeline from the household relocation timeline. Closing documents belong in the file, alongside records showing the actual move and changes in how both homes were used.
As a practical step, assemble a dated chronology supported by the Florida lease or closing statement, moving invoices, utility changes, and insurance updates. Add Chicago sale or lease-termination documents where applicable. If the Chicago home is retained, document that reality rather than implying a complete departure from Chicago housing.
Administrative changes need not all occur on one date. Record the actual dates accurately rather than making later updates appear simultaneous with the claimed domicile change.
A useful travel calendar records more than Florida days and Illinois days. It should capture dates, locations, travel purpose, lodging, and use of the Chicago property. The aim is to document both physical presence and the circumstances surrounding it.
Maintain the calendar contemporaneously. Tickets, hotel invoices, toll records, and financial transactions can corroborate entries. Preserve enough detail for an adviser to understand the pattern without reconstructing an entire year from memory.
For return trips to Chicago, distinguish business visits from family stays or extended periods living in the retained home. Those descriptions should reflect what happened, not what sounds most favorable. When a travel day spans locations, record the itinerary rather than assuming a counting convention.
This is practical recordkeeping, not a statutory checklist or a guarantee of nonresidency. A meticulously totaled calendar cannot replace evidence of domicile or explain away conduct inconsistent with a permanent Florida move.
A Florida driver's license is evidence of intent to establish residency, not conclusive proof on its own. A declaration of domicile can likewise document intention, but it should align with the person's actual home and behavior.
Review housing documents, driver’s licenses, voter and vehicle registrations, financial-account addresses, insurance, and estate-planning documents. The objective is appropriate, accurate consistency across records that describe where the person lives and maintains a permanent home.
For someone selecting Five Park Miami Beach as a permanent residence, administrative work deserves its own place on the relocation calendar. Keep address-change confirmations. When the dates differ, distinguish when a request was submitted from when the update took effect.
Consistency does not mean disguising legitimate Illinois connections. It means ensuring that the records-and the life behind them-support rather than contradict the claimed Florida domicile.
The lifestyle appeal of Miami Beach is separate from the evidence needed to establish domicile. When evaluating Setai Residences Miami Beach, ask how the residence would function as the household's permanent home, not simply how appealing it would be for seasonal visits.
Retaining a Chicago residence requires particular attention to its actual use. Continued use as the practical permanent home can undermine a claimed Florida domicile. A Florida address on important documents is less persuasive when the household's conduct points elsewhere.
Keep an accurate record of Chicago stays and the purpose of each visit. If the transition unfolds in stages, preserve that chronology. A complex but truthful account is more useful than a simplified one that conflicts with travel or housing records.
Florida domicile does not automatically eliminate Illinois tax obligations. Illinois-source income may remain reportable after the move, even when the domicile change is genuine.
Potential categories include income from Illinois real estate, businesses, and services performed in Illinois. Treatment depends on the income category and applicable rules. The residency analysis and the income-sourcing analysis should therefore remain distinct.
For households returning to Chicago for work, the travel calendar can also help identify where services were performed. Preserve the underlying detail and have an adviser assess its significance rather than assuming all post-move income receives the same treatment.
Before finalizing the transition-year tax position, reconcile the travel calendar, financial transactions, housing use, and administrative updates. Separately identify potential Illinois-source income. Resolve discrepancies with accurate explanations and supporting records, not retrospective alterations.
Retained Chicago housing, business interests, trusts, or frequent interstate work warrant professional review. These recommendations are general information, not individualized tax or legal advice. The strongest first-year plan is one in which intention, conduct, and documentation describe the same permanent move.
Explore South Beach residences with MILLION as you plan a home that supports your next chapter.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationFlorida does not impose an individual state income tax and has no personal state income-tax return filing requirement. That does not eliminate possible Illinois obligations.
No. Illinois residency also depends on domicile evidence and whether presence or absence is temporary or non-temporary.
Domicile is the place where a person resides and intends to return after temporary absences. Changing it requires intent to abandon the former domicile and establish a new one, supported by actual conduct.
No. Acquiring a residence and making it a permanent home are distinct events, and the documented transition should reflect actual conduct.
Record dates, locations, travel purpose, lodging, and Chicago-property use. Preserve supporting items such as tickets, hotel invoices, toll records, and transactions.
No. It is evidence of intent to establish residency, but it should be considered alongside housing use, other records, and actual behavior.
Retaining a Chicago residence requires attention to its actual use. Continued use as the practical permanent home can undermine the claimed Florida domicile.
Administrative updates need not all occur on the same date. Record their actual dates accurately and preserve confirmations that support the relocation chronology.
Potential Illinois-source income includes income from Illinois real estate, businesses, and services performed in Illinois. Treatment depends on the income category and applicable rules.
Reconcile travel records, financial transactions, housing use, and administrative updates, while separately identifying Illinois-source income. Retained housing, business interests, trusts, or frequent interstate work warrant professional review.