A considered move from Abu Dhabi to Fort Lauderdale begins before the first property transfer. Account verification, a coherent funding file, clear entity ownership and disciplined wire approvals deserve a place alongside the residential search.
For a household relocating from Abu Dhabi to Fort Lauderdale, the first year is more than a change of address. It is an opportunity to align personal banking, property ownership and cross-border administration before a purchase becomes time-sensitive. The aim is not more paperwork, but a clear account of who is buying, where the money originated and who may authorize its movement.
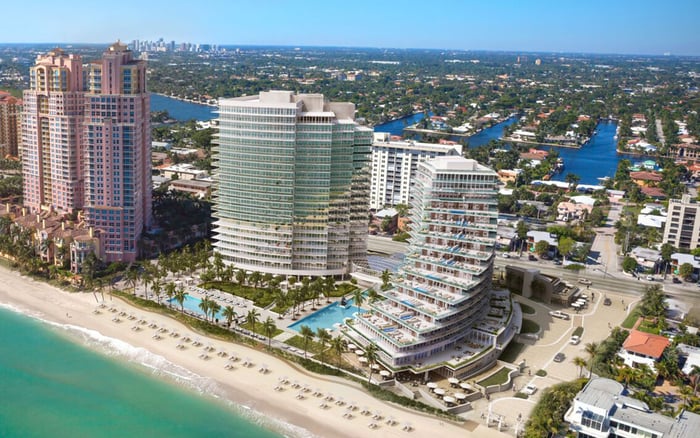
Whether the shortlist includes Four Seasons Hotel & Private Residences Fort Lauderdale or another Broward address, prepare for banking alongside the residential search-not during closing week. A residence can be selected on lifestyle grounds; its funding arrangements deserve a separate review with banking, legal and tax advisers.
U.S. banks generally must collect a customer's name, date of birth for an individual, address and identification number before opening an account. For a non-U.S. person, permitted identification can include a passport number and issuing country, an alien-identification number or qualifying government-issued nationality or residence documentation.
That federal baseline does not establish a universal requirement for a U.S. residential address. Ask the intended bank which address evidence it accepts in your circumstances. An acceptable passport does not guarantee approval: banks apply risk-based identity-verification procedures.
Before arranging an appointment, request the institution's checklist for the proposed customer and account type. Distinguish a personal account from an entity account, and explain its intended use. Do not assume that an account suitable for household spending also resolves the documentation questions surrounding an entity-funded property purchase.
A chronological source-of-funds file is a practical recommendation, not a universally prescribed format. Organize it to connect the origin of the purchase money, its movement between accounts and the proposed payment to the recipient.
Consider an index, relevant account statements and documents explaining the event that generated the funds, such as a sale or distribution where applicable. Let the bank and legal advisers determine which evidence is needed. The objective is a traceable sequence, not an indiscriminate archive.
For a buyer considering Sixth & Rio Fort Lauderdale, that preparation should accompany a review of the actual payment obligations. Do not equate an available balance with completed bank review. Ask specifically about translation, certification, notarization or legalization requirements rather than treating them as universal rules for UAE documents.
If an entity will hold the residence or operate the funding account, its formation documents are only part of the discussion. Covered financial institutions generally must identify and verify individuals owning 25% or more of a covered legal-entity customer, together with one individual exercising significant management or control responsibility.
Customer due diligence also addresses the nature and purpose of the relationship and ongoing transaction monitoring. Prepare a concise explanation of the entity's intended account use alongside its ownership and control information. For a foreign business without an identification number, the bank must request alternative government-issued documentation certifying its existence.
Under the framework applicable to this September 2026 planning discussion, U.S.-formed companies are exempt from Corporate Transparency Act beneficial-ownership reporting; certain foreign companies registered to do business in the United States remain subject to reporting. That exemption does not extend to bank onboarding.
Exceptive relief also removes automatic repeat beneficial-owner identification and verification for every additional account. Checks remain at the first account opening, when information becomes unreliable and when risk-based procedures require them. Confirm the applicable position when acting.
A Florida LLC requires a registered agent with a Florida street address, not a post-office box, and cannot act as its own registered agent. Keep that address requirement separate from the bank's customer-address policy.
The first annual report falls in the calendar year after formation. The annual filing window runs from January 1 through May 1, with a $138.75 fee and an additional $400 late fee after May 1. Assign responsibility when the entity is formed, rather than after the residence is occupied.
An EIN applicant's responsible party generally must be an individual. Where that person lacks, and is ineligible to obtain, an SSN or ITIN, “foreign” or “N/A” is permitted on line 7b. This is a specific application provision, not a substitute for the bank's identity checks.
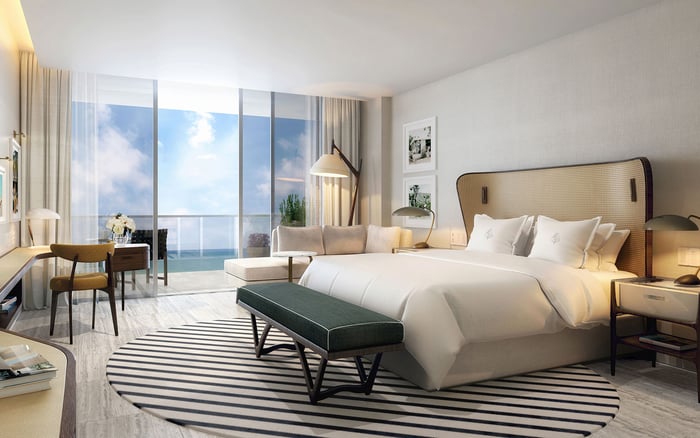
For a purchase involving St. Regis® Residences Bahia Mar Fort Lauderdale, as with any prospective acquisition, agree on the household's approval process before sending funds. The following are recommended safeguards, not universal legal requirements or project-specific procedures.
Independently verify payment instructions by telephone using a number established separately from the message requesting the transfer. Consider two-person approval: one person prepares the payment details, while another checks the recipient, amount and authorization. Treat changed instructions as a reason to pause and reverify.
Keep the approved instructions and transfer confirmation in the transaction file. These controls support disciplined execution; they do not replace bank review or guarantee a payment's timing.
The $10,000 thresholds apply to distinct obligations. Transporting, mailing or shipping more than $10,000 in currency or covered monetary instruments across the U.S. border, including foreign-currency equivalents, requires Form 105. Carrying that amount is not prohibited, but failing to declare it can expose funds to seizure and the traveler to penalties. This is not a blanket traveler-reporting requirement for ordinary bank-to-bank electronic wires.
Separately, a U.S. person generally must file an FBAR when foreign accounts in which they have a financial interest or reportable authority exceed $10,000 in aggregate at any time during the calendar year. The relevant questions concern status and account relationships, not simply whether an international wire occurred.
Bank-deposit interest paid to a nonresident alien is generally exempt from U.S. income tax unless effectively connected with a U.S. trade or business. Form W-8BEN can establish foreign status; tax exemption does not resolve separate information-reporting obligations. Review status with a tax adviser as the relocation progresses.
For a potential acquisition at Auberge Beach Residences & Spa Fort Lauderdale, keep closing taxes in a separate budget category. Fort Lauderdale deed transfers carry documentary stamp tax of $0.70 for each $100, or fraction thereof, of taxable consideration. It is a closing-cost item, not a wire-compliance charge.
Before arrival, clarify bank requirements and the proposed ownership structure. Before payment, reconcile the funding file and verify instructions. After closing, track entity deadlines and revisit foreign-account and tax-status questions. This sequence is a planning recommendation, not a promised onboarding timetable.
Explore your Fort Lauderdale residential options with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. A passport number and issuing country can satisfy a permitted identification category for a non-U.S. person, but banks also apply risk-based verification procedures.
The federal identification baseline does not establish that universal requirement. Ask the selected bank which address and supporting evidence it accepts.
It is a practical organizational recommendation, not a universal prescribed format. The bank and legal advisers should determine the evidence needed for the transaction.
Do not assume a universal requirement. Confirm translation, certification, notarization and legalization expectations with the institution reviewing the documents.
For a covered legal-entity customer, the framework generally requires identification and verification of individuals owning 25% or more and one individual with significant management or control responsibility.
No. The Corporate Transparency Act reporting exemption for U.S.-formed companies is separate from the beneficial-owner requirements that apply to covered financial institutions.
The first annual report is due in the calendar year after formation, within the January 1 to May 1 filing window. The fee is $138.75, with an additional $400 late fee after May 1.
Not merely because it exceeds that amount. Form 105 concerns cross-border transportation, mailing or shipment of currency and covered monetary instruments, rather than ordinary bank-to-bank electronic wires.
Yes, generally when a U.S. person has a financial interest or reportable authority over foreign accounts whose aggregate value exceeds $10,000 at any time during the calendar year. Status and account relationships require individual review.
The rate is $0.70 for each $100, or fraction thereof, of taxable consideration. This is a closing-cost item, not a wire-compliance charge.