A Paris-to-Pompano Beach move deserves two coordinated plans: one for the household’s daily life, another for its cross-border obligations. This private-client checklist separates residence decisions from tax determinations and sets out the advice, records, and timing questions to resolve before relocating.
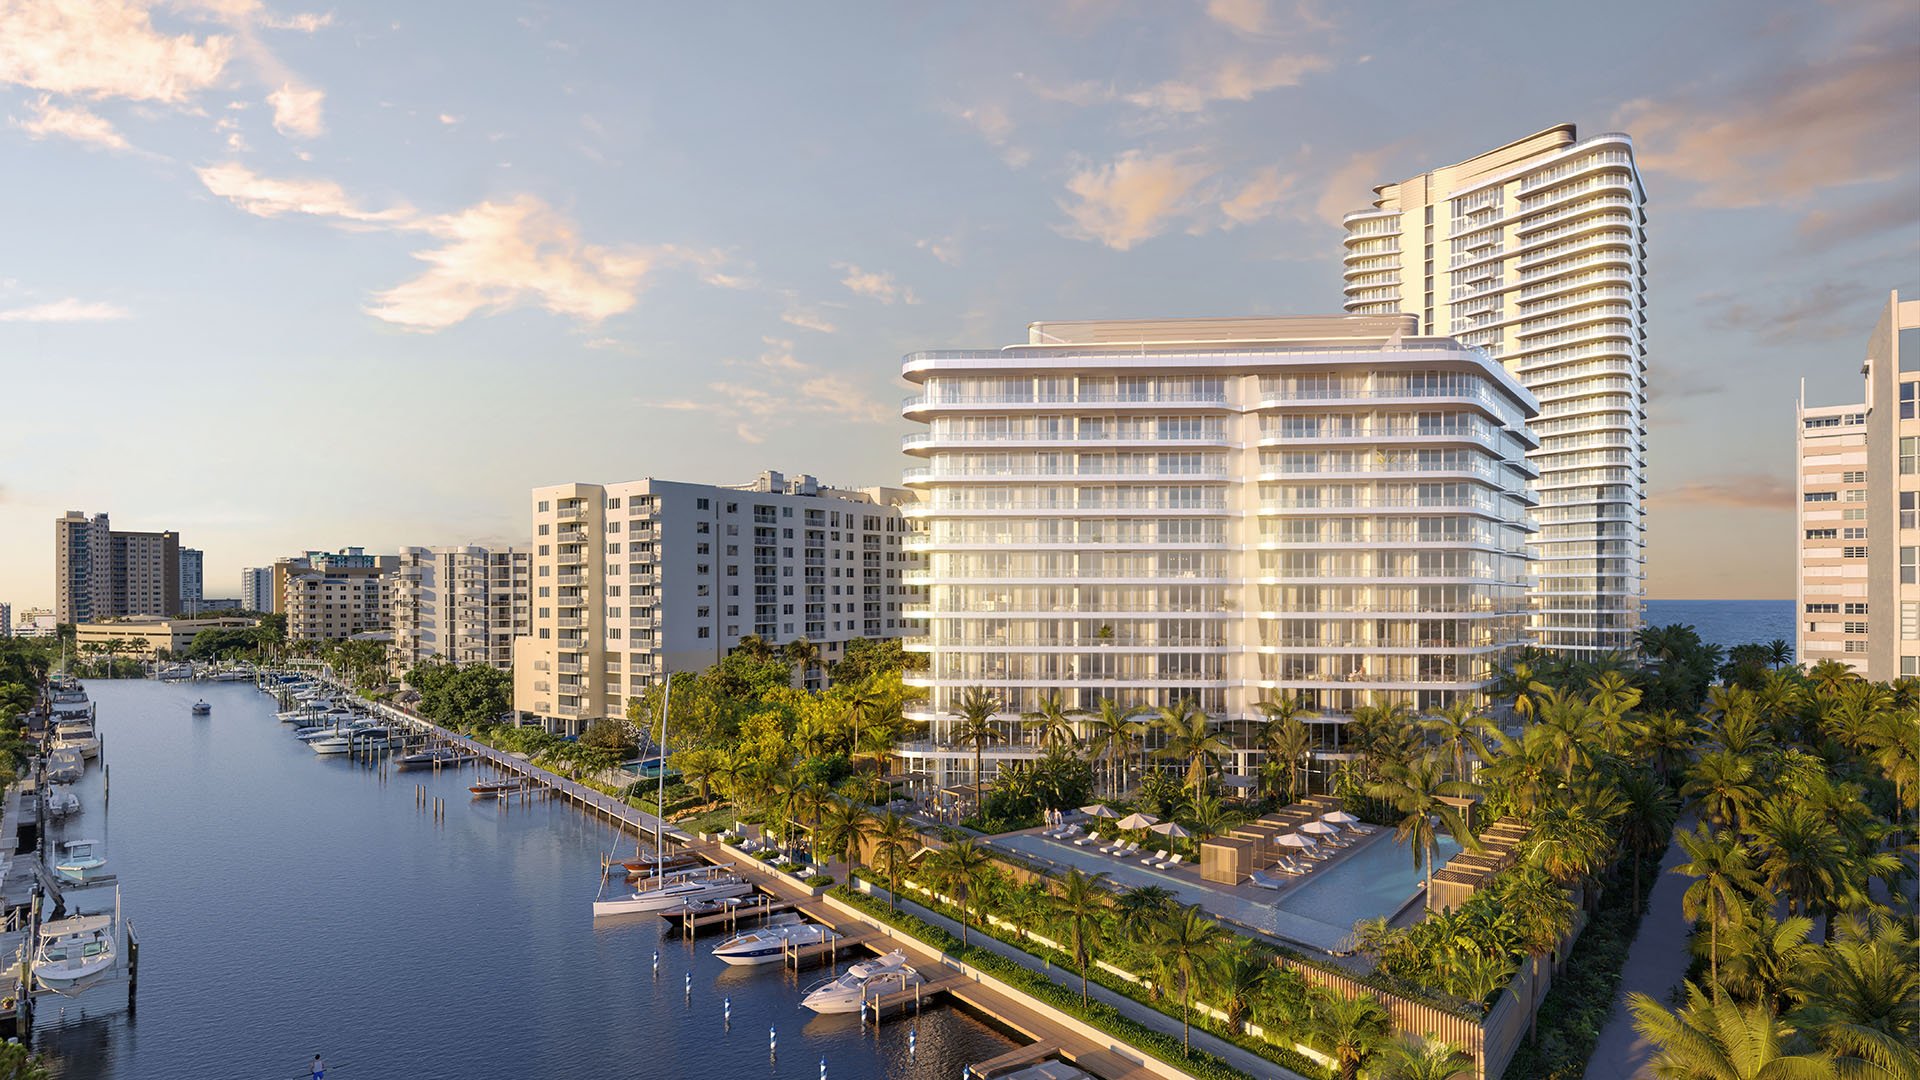
Rebasing from Paris to Pompano Beach should begin with a question more durable than a projected tax outcome: where will the household live well? Schooling, healthcare, privacy, social connections, and the practical demands of maintaining European business interests each deserve consideration. A residence purchase is not, by itself, a change in tax residence.
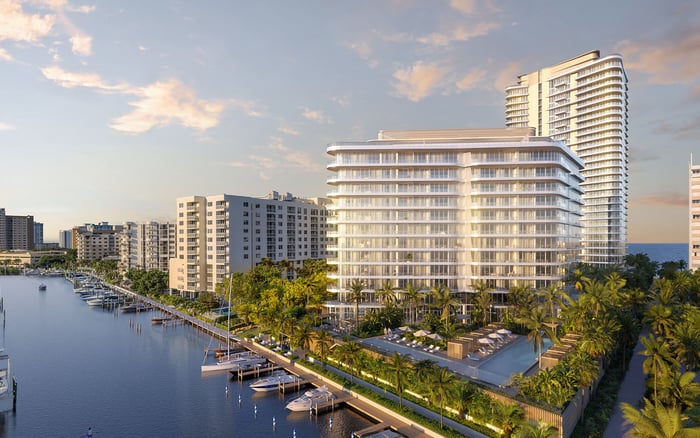
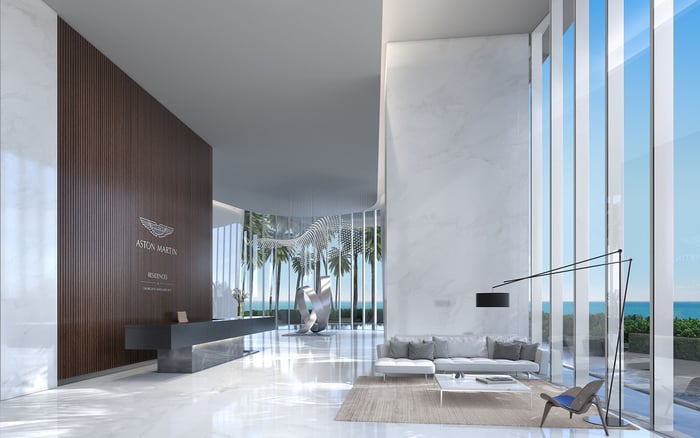
For a buyer considering Armani Casa Residences Pompano Beach, the starting point is a household brief, not a tax assumption. Define the intended annual rhythm, space requirements, travel tolerance, and total housing budget. Then ask advisers to assess the consequences of that life, rather than designing a life around one fiscal advantage.
Before fixing the relocation date, request coordinated written advice from French tax counsel, a U.S. international-tax adviser, Florida estate counsel, and immigration counsel. Appoint one coordinator to reconcile assumptions and maintain the decision calendar.
The brief should distinguish five determinations:
Immigration permission: whether the proposed living and working arrangements are legally feasible.
Income-tax residence: how each country’s domestic rules apply to each individual.
Treaty residence: how competing residence claims should be analyzed.
Estate-and-gift-tax domicile: a separate assessment from income-tax residence.
Homestead eligibility: whether the Florida property and applicant meet the applicable requirements.
Ask every adviser to work from the same travel history, family circumstances, and asset inventory. Where conclusions differ, resolve the disagreement before committing to dates or transactions. The closing date should inform this assessment, not determine its conclusion.
A non-U.S. citizen generally becomes a federal income-tax resident through either the green-card test or the substantial-presence test, subject to exceptions and treaty rules. Lawful permanent resident status can establish tax residence even without meeting the substantial-presence test.
The substantial-presence calculation generally requires at least 31 U.S. days in the current year and 183 weighted days across three years. Count all current-year days, one-third of the preceding year’s days, and one-sixth of the second preceding year’s days. Ask the adviser to identify applicable exceptions rather than relying on a simple annual day limit.
Maintain a shared travel-day record for the relevant years, supported by documentation. The transition year requires its own residency-starting-date analysis: an individual may be nonresident for one part and resident for another.
U.S. resident aliens are generally subject to federal income tax on worldwide income. If both countries consider an individual resident, treaty residence requires separate analysis, and a treaty-based return position may require disclosure. Neither a deed nor a moving itinerary resolves these questions alone.
French departure-year reporting generally distinguishes income received before departure from taxable French-source income received afterward. That year’s income is generally declared the following year, not through a final income-tax return filed on moving day. Continuing French-source income may remain taxable in France, subject to applicable treaty provisions.
Request a written departure checklist covering income allocation, filing responsibilities, and continuing obligations. Assess both partners individually: a household relocation does not guarantee identical French filing outcomes, particularly when one spouse or civil partner becomes nonresident while the other remains resident.
French exit-tax exposure also requires a tailored review. Reporting can include Form 2074-ETD for unrealized capital gains, certain earn-out claims, and gains already under tax deferral. Eligibility, payment-deferral provisions, and subsequent events all matter. Do not assume every departing investor faces the same treatment-or that departure settles all later obligations.
Prepare an asset register covering assurance-vie, PEA accounts, pensions, non-U.S. funds, trusts, private-company interests, and appreciated assets. Record ownership, acquisition information, available cost documentation, and relevant contractual restrictions for adviser review.
Do not assume French treatment carries over to the United States. Request product-specific analysis before selling, restructuring, transferring, or retaining an asset based on its familiar French classification. The objective is informed sequencing, not a blanket instruction to liquidate.
U.S. residence can also bring foreign-account and foreign-financial-asset reporting obligations, including FBAR and Form 8938 where their respective requirements are met. Assign each review and filing to a named professional. Do not presume that preparing an income-tax return automatically resolves every reporting question.
Pair a viewing at Ocean 580 Pompano Beach with a practical test of the proposed routine. Investigate schooling, healthcare access and insurance, European business connectivity, and the cumulative burden of transatlantic travel. Weigh privacy and social fit alongside layout and design.
Apply the same discipline when evaluating Waldorf Astoria Residences Pompano Beach. Obtain property-specific information on ownership costs, insurance, maintenance, and applicable building obligations. Separate verified costs from estimates, and test whether the budget remains comfortable without assuming a particular tax benefit.
The strongest shortlist is one the family would still favor if its anticipated fiscal outcome changed. Tax efficiency can refine a residence decision; it should not substitute for one.
Florida’s homestead property-tax exemption depends on qualifying ownership and permanent residence, not simply purchasing a home. In Broward County, the property generally must be the owner’s permanent home, or a qualifying dependent’s permanent home, as of January 1 of the claimed tax year.
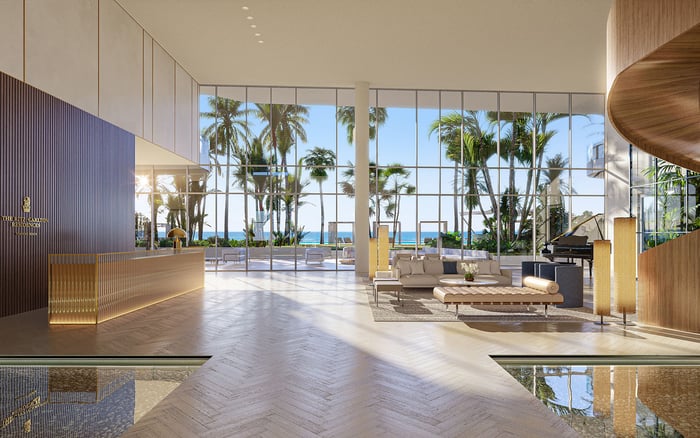
Whether the intended address is at The Ritz-Carlton Residences® Pompano Beach or another shortlisted property, coordinate the relevant identity, address, vehicle-registration, and immigration documentation. Confirm the applicable tax-year guidance and application requirements rather than assuming a closing guarantees eligibility.
Separately, ask Florida estate counsel to address ownership and succession before purchase. U.S. estate-and-gift-tax residence uses a domicile analysis distinct from the income-tax tests. For a noncitizen, nonresident decedent, U.S.-situated property worth more than $60,000 generally triggers Form 706-NA filing. That is a filing threshold, not a statement of final tax liability.
Before departure, assemble five working records: the travel-day log, asset register, acquisition-cost file, transition-evidence folder, and compliance calendar. Assign each filing a named owner, a confirmed deadline, and a list of required documents. Include both countries’ transition-year work and any continuing obligations.
Revisit the plan when travel patterns, family arrangements, assets, or immigration status change. The aim is consistency between the household’s actual life, its documented facts, and its advisers’ conclusions.
This checklist is an editorial framework, not individualized tax, legal, or immigration advice. The residence choice should remain personal; its cross-border consequences deserve coordinated professional attention.
Explore a Pompano Beach residence shortlist shaped around your household’s priorities with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationA purchase alone does not establish U.S. income-tax residence. For a non-U.S. citizen, the green-card and substantial-presence tests generally govern, subject to exceptions and treaty rules.
It generally requires at least 31 U.S. days in the current year and 183 weighted days. The calculation includes all current-year days, one-third of the preceding year’s days, and one-sixth of the second preceding year’s days.
Yes. Lawful permanent resident status can establish U.S. tax residence under the green-card test even when the substantial-presence test is not met.
U.S. resident aliens are generally subject to federal income tax on worldwide income. The transition year requires a separate analysis of when residence begins.
Treaty residence must be analyzed separately from domestic-law residence. A treaty-based return position may also require disclosure.
Departure-year income is generally declared the following year. Reporting generally distinguishes pre-departure income from taxable French-source income received afterward.
No. Exposure depends on eligibility conditions, payment-deferral provisions, and subsequent-event rules, with Form 2074-ETD potentially relevant.
Flag assurance-vie, PEA accounts, pensions, non-U.S. funds, trusts, private-company interests, and appreciated assets for product-specific advice. Their French treatment should not be assumed to carry over to the United States.
No. Qualifying ownership and permanent residence are required, with January 1 central to the claimed tax year and supporting documentation needed.
No. U.S. estate-and-gift-tax domicile is a separate determination, and the more-than-$60,000 U.S.-situated-property threshold for a noncitizen, nonresident decedent generally concerns Form 706-NA filing, not final tax liability.