At 619 Residences, the closing-cost conversation belongs alongside the architecture. A buyer-focused guide to distinguishing estoppel charges, potential capital contributions and transfer fees, with carefully qualified budget illustrations.
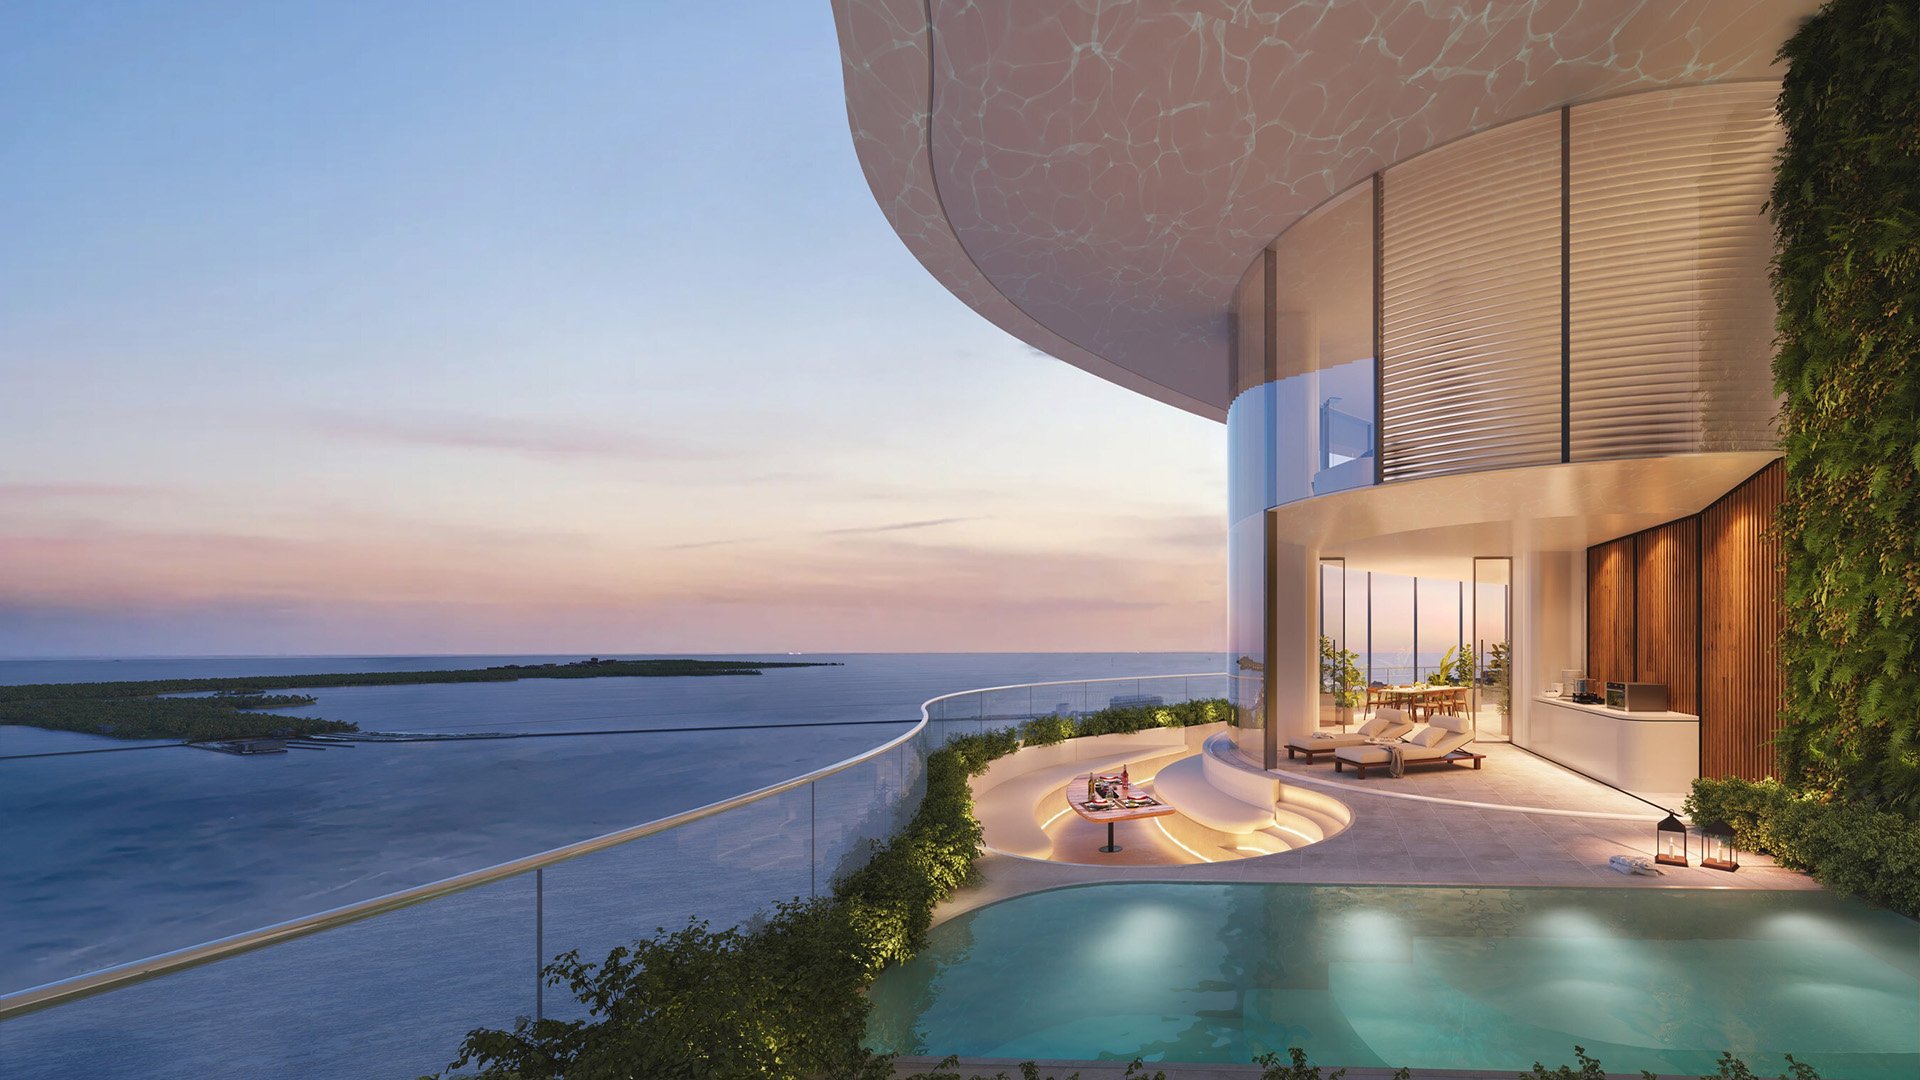
At 619 Residences by Foster + Partners + Nobu Hospitality, the appeal begins with a planned waterfront address at 619 Brickell Avenue overlooking Biscayne Bay. Foster + Partners designed the tower in collaboration with Sieger Suarez Architects, with 13th Floor Investments and Key International as developers. The planned 75-story building represents Nobu Hospitality’s first residential project in Miami.
For a buyer, however, architectural distinction and closing certainty are separate considerations. An estoppel charge, a capital contribution and a transfer-related fee should never be folded into one unexplained allowance labeled “association costs.” Each requires a clear basis, recipient and payment terms.
The essential distinction is between an illustration and an obligation. Confirm the project’s actual estoppel fee, working-capital requirement and transfer-fee schedule in the applicable documents. Neither its positioning nor its amenity scale establishes those obligations.
The planned offering includes approximately 90,000 square feet of private amenities, with a spa, fitness center and poolside café, alongside plans for Miami’s second Nobu restaurant. The planned $25 million wellness investment is a project feature, not a disclosed assessment payable by purchasers.
That distinction matters when reviewing branded residences. An extensive service offering does not establish that owners fund restaurant operations, brand fees or individual wellness services through association dues. Ask which services the budget includes, which carry separate charges and how shared expenses are allocated.
For a buyer also considering Cipriani Residences Brickell, the useful comparison lies in the documents: what does each purchase require at closing, and what does each recurring assessment cover? A hospitality identity alone cannot answer either question.
When reviewing closing costs, distinguish the estoppel certificate’s account information from the charge for obtaining it. The document fee is separate from any balance or obligation the certificate identifies.
Ask the closing team to reconcile the certificate, where applicable, with the proposed settlement statement and transaction documents. Which amounts relate to the seller’s account? Which are assigned to the purchaser? Does the statement distinguish an existing balance from a new buyer contribution?
At 619, do not insert an assumed estoppel charge into a final budget. Request the applicable amount and its written basis. Counsel should confirm which documentation applies to the transaction, particularly when distinguishing an initial developer sale from a later resale.
The objective is straightforward: every association-related entry should be understandable without relying on a verbal description such as “standard closing fee.”
The quoted average association figure of $1.75 per square foot carries the qualification “Final budget TBD.” Before using it to budget, confirm the billing period, assessment basis and included services. Do not assume that the square footage used in a sales presentation determines the assessment calculation.
Solely for illustration, treating the figure as monthly and applying it directly to residence area produces monthly association charges of $5,250 for a 3,000-square-foot home and $8,750 for a 5,000-square-foot home. These illustrations exclude separate property taxes and owner insurance. They are not final project assessments.
Now consider a second, explicitly hypothetical assumption: a working-capital contribution equal to three months of those illustrative dues. That produces $15,750 for the 3,000-square-foot residence and $26,250 for the 5,000-square-foot residence. Neither amount is a verified 619 closing charge, and the three-month formula is not established as a project requirement.
The exercise shows why the formula deserves scrutiny. If the governing documents require a contribution tied to assessments, the assessment basis becomes part of the closing calculation. Ask whether any contribution is refundable, credited against future dues or retained for a stated purpose. Those treatments are not interchangeable.
A closing worksheet should identify every proposed charge separately. Combining charges obscures both the economic cost and the cash required to complete the purchase.
Estoppel charge: identify the document-related amount separately from account balances.
Ownership or lease approval fee: request the applicable approval provision and recipient.
Transfer fee: identify the event that triggers payment and the calculation used.
Moving charge: distinguish any move-related service charge from other closing items.
Refundable deposit: establish the conditions and procedure for returning the money.
Capital contribution: confirm its purpose, formula and treatment after payment.
These are review categories, not a statement that 619 imposes every charge. A refundable deposit, if required, affects immediate liquidity differently from a nonrefundable payment. Likewise, a contribution should not be treated as prepaid monthly dues unless the documents expressly provide that credit.
For buyers, the most useful question is often not how large a fee appears, but precisely what the payment purchases, satisfies or secures.
Occupancy is targeted for 2031-a development target, not a guaranteed closing date. For a pre-construction purchase, ask which budget and fee schedules will govern at closing and how revisions will be communicated. An early illustration should remain clearly labeled as provisional in the buyer’s financial planning.
Resale requires a separate review. Counsel should examine the treatment of later sales, leases, gifts, transfers into trusts and LLC ownership changes. These are questions to resolve, not events to assume will automatically trigger a fee.
A purchaser weighing St. Regis® Residences Brickell alongside 619 can apply the same discipline without assuming the projects share provisions. Compare obligations for the intended ownership structure, not simply quoted dues. For estate planning, clarity about a future transfer can be as relevant as clarity about the initial acquisition.
Before approving the final cash requirement, have the closing team identify four things for each proposed association-related payment: what is payable, who receives it, whether it is refundable and which formula determines the amount. Add the governing provision and the party responsible under the transaction documents.
Keep confirmed obligations separate from planning assumptions. Retain the $1.75 figure and any three-month contribution scenario only as labeled illustrations until the applicable documents support their use. Reconcile the final statement to ensure that no contribution, deposit or account balance is counted twice under different descriptions.
The goal is not to reduce a distinguished residence to a spreadsheet. It is to give the financial terms the same attention as the architecture, with clear obligations at closing and a considered view of ownership afterward.
Explore South Florida residences with a more considered buyer perspective at MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationThe planned waterfront condominium is at 619 Brickell Avenue in Miami, overlooking Biscayne Bay.
Foster + Partners designed the tower in collaboration with Sieger Suarez Architects. The developers are 13th Floor Investments and Key International.
The project’s actual estoppel fee is not established here. Request the applicable amount and written basis from the closing team rather than budgeting an assumed charge.
No. The quotation is qualified by Final budget TBD, and its billing period, assessment basis and included services need confirmation.
Assuming monthly billing and direct application to 3,000 square feet, it produces $5,250 a month before separate property taxes and owner insurance. This is an illustration, not a final assessment.
Under the same monthly assumption, the figure produces $8,750 a month before separate property taxes and owner insurance. The actual assessment requires confirmation.
That requirement is not established. The $15,750 and $26,250 examples use a hypothetical three-month formula and are not verified project closing charges.
No buyer assessment is established by the described $25 million wellness investment. It is a project feature, not a disclosed purchaser contribution.
Yes. Counsel should examine their treatment alongside resales, leases and gifts without assuming that any of these events necessarily triggers a fee.
No. Occupancy in 2031 is a development target, not a guaranteed closing date.