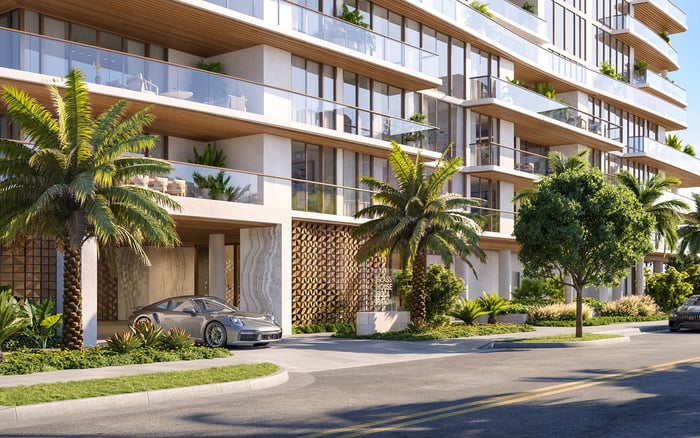
Before reserving a Pompano Beach residence, examine the agreements, staffing schedules and financial assumptions behind the service promise. A disciplined review separates introductory costs from sustainable operations and projected budgets from established performance.
A luxury residence is more than its architecture. The arrival experience, consistency of service and care of shared spaces depend on an operating budget. Before reserving in Pompano Beach, the question is not simply what the monthly assessment will be. It is what that assessment funds, which assumptions support it and how those assumptions may change after closing.
For buyers considering The Ritz-Carlton Residences® Pompano Beach or another residence, this is a diligence framework, not a finding about a particular development. The objective is to connect the service promise to written obligations and a credible funding plan. Across Broward, a polished presentation should invite equally precise financial questions.
Begin with the proposed budget and prior approved budgets, where available. Florida condominium budgets must detail estimated revenues and expenses by account and expense classification. That structure allows a buyer to examine management, maintenance, staffing and amenity expenses individually, rather than relying on a single monthly assessment figure.
Ask which fiscal year the budget covers and whether it has been adopted. Under the 2025 budgeting provisions, the annual budget must be adopted at least 14 days before the fiscal year begins. A preliminary projection and an adopted association budget are not interchangeable.
For an operating association, request the last three annual financial reports alongside the budgets. Budgets describe estimated activity; financial statements document results. The 2024 financial-reporting provision requires completion of the annual financial report, or contracting for its preparation, within 90 days after fiscal year-end, unless the bylaws specify another annual date. That is not necessarily a deadline for delivering a completed audit.
Request documents through the seller, developer or authorized association representative. Association contracts and financial records are official records, but owner access rights do not automatically extend to every prospective buyer or reservation holder.
Service contracts should be in writing. Ask for executed agreements, amendments and renewal schedules rather than relying on verbal descriptions of service or pricing. Where contracts have not yet been executed, identify which budget assumptions remain provisional.
For each significant agreement, ask which increases may occur during the first five years after closing. Is pricing fixed, indexed or subject to vendor discretion? Does the agreement permit separate increases for wages, insurance, fuel or materials? Can multiple adjustments apply in the same year?
A CPI clause deserves more than a passing glance. Identify the index, geography, measurement period, adjustment date, cap and floor. Then ask whether increases compound and whether the contract provides a corresponding adjustment when the index falls. Review renewal terms, notice deadlines and termination provisions with counsel.
The same questions belong in a comparison involving Armani Casa Residences Pompano Beach. A name or design identity cannot substitute for examining the agreements behind the proposed operating model.
Evaluate concierge, valet, security and amenity coverage as staffing schedules, not merely as lifestyle language. Ask how many posts are funded, how many hours each post operates and whether duties overlap. A service description alone does not establish simultaneous coverage.
Request the labor assumptions behind those schedules: base compensation, overtime, relief coverage, payroll taxes, benefits and anticipated wage increases. Ask who covers vacations, absences and peak demand, and whether that coverage is included in the contract price or billed separately.
Then reconcile the schedule with the budget. Do the signed agreements and allocations support the advertised service hours? If the answer depends on a future hiring plan or an unsigned vendor proposal, request that distinction in writing. The point is not to demand maximum staffing everywhere, but to understand the service level actually funded.
For pre-construction purchases, historical association results may not exist. A projection can still be useful if its assumptions are explicit. Ask which expenses depend on developer subsidies, introductory vendor pricing or contributions from another project component, and when each arrangement ends.
Request a comparison between the supported budget and the expected budget after that support expires. Identify who bears each expense, how allocations are determined and whether the anticipated full service schedule is included. A lower opening assessment deserves explanation, not automatic suspicion or reassurance.
When reviewing Waldorf Astoria Residences Pompano Beach, apply these questions to the documents made available for the contemplated purchase. Do not infer subsidies, staffing arrangements or cost-sharing terms from branding alone.
Where an operating history exists, request three years of actual-versus-budget results and explanations for the largest recurring unfavorable variances. Examine both dollars and percentages. A large percentage movement in a small account may matter less than a modest percentage increase in a major recurring expense.
A review threshold such as the greater of 5% or $10,000 can help prioritize questions, but it is an analytical choice, not a legal requirement. Ask whether each variance reflects timing, a one-time expense, changed scope or a recurring cost that the next budget must absorb.
In a comparison that includes Casamar, keep projected budgets separate from established operating results. Also request receivables aging, delinquency figures and unpaid vendor balances. Expense performance alone does not establish cash-flow strength.
Where a structural integrity reserve study applies, request the latest study and compare its funding requirements with the proposed budget. Review the applicable reserve funding provisions and exceptions. Because those provisions span 2024 and 2025, have counsel confirm the rules applicable when you purchase.
Applicable recreation and amenity amounts must be identified separately in condominium budgeting. Review those allocations alongside service contracts, and confirm the residence’s proportionate assessment share in the declaration. The effect of a building-wide expense depends on the share assigned to your unit.
The strongest reservation decision follows a clear explanation of current costs, future adjustments and unresolved assumptions. For a discreet perspective on your Pompano Beach residential search, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationRequest the proposed budget, prior approved budgets and the last three annual financial reports where available. For an operating association, also ask for actual-versus-budget comparisons.
Under the 2025 budgeting provisions, the annual budget must be adopted at least 14 days before the association’s fiscal year begins. Have counsel confirm the requirements applicable when you purchase.
No. The 2024 provision addresses completing the annual financial report or contracting for its preparation within 90 days after fiscal year-end, unless the bylaws specify another annual date.
Identify the index, geography, measurement period, adjustment date, cap and floor. Ask whether increases compound and whether other price adjustments can apply alongside CPI.
Compare advertised service hours with funded posts, shift schedules and signed agreements. Include overtime, relief coverage, payroll taxes, benefits and anticipated wage increases.
Temporary support can affect the opening budget. Ask which expenses receive support, when it ends and what the projected costs become afterward.
Evaluate the projected budget and its underlying assumptions rather than treating it as established performance. Identify unsigned contracts, provisional staffing plans and temporary pricing.
No. It is an optional analytical threshold for prioritizing review, not a legal requirement.
No. Owner record-access rights should not be assumed to apply to every prospective buyer or reservation holder; request documents through an authorized party.
Where applicable, compare the latest structural integrity reserve study with the proposed budget and confirm current funding requirements with counsel. Check the declaration for the proportionate assessment share assigned to your residence.