Before an estate retains or transfers a South Florida residence, its advisers should reconcile reconstruction value, interior improvements, ordinance coverage, ownership interests, and policy limits. A disciplined preclosing review can reveal underinsurance that a purchase price or premium comparison cannot.
For an estate retaining or transferring a South Florida residence, insurance deserves the same deliberate attention as title and disposition. The central question is not simply what the property is worth, but what the policy would pay to restore the insured residence after a covered loss-and whether the estate or recipient would face an unexpected shortfall.
Whether the property is in Coral Gables, Sunny Isles Beach, or Fisher Island, the review should align three elements: the residence as it exists today, the interests being insured, and the contract that will respond. A premium quotation alone cannot establish that alignment.
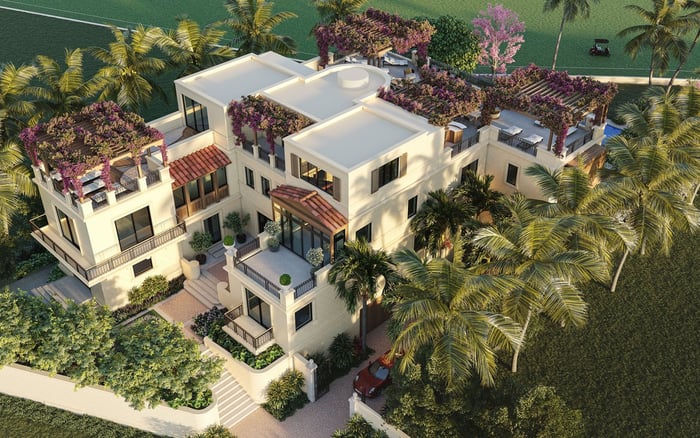
Consider an estate evaluating a residence at The Links Estates at Fisher Island. The useful preclosing question is not whether the address commands a substantial price, but whether a current reconstruction assessment supports the proposed insurance limit. This is a valuation question, not a claim about any project's coverage.
A market appraisal and a replacement-cost assessment answer different questions. Do not assume the purchase price or market value establishes the correct dwelling limit. Request a current estimate of the cost to reconstruct the insured property, with clear assumptions and an explicit account of the improvements included.
A preclosing reconstruction appraisal is a risk-management recommendation, not a universal Florida legal requirement. Ask the insurance broker whether a detailed appraisal or another current reconstruction estimate is appropriate, and how the insurer will use it to establish coverage.
Replacement-cost coverage uses current replacement prices; actual-cash-value coverage deducts depreciation. Replacement cost, however, does not mean unlimited reimbursement. Dwelling replacement-cost coverage remains subject to policy limits and terms. If extended or guaranteed replacement cost is discussed, request the supporting policy language rather than relying on the label.
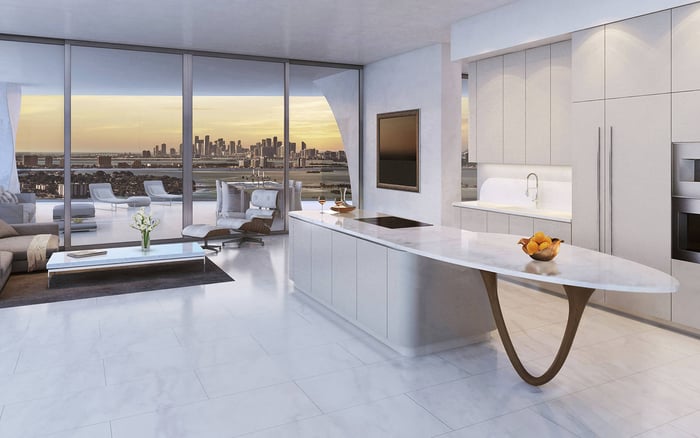
For a residence under review at Una Residences Brickell, reconcile the existing interior with the one described in the insurance valuation. Neither a project name nor a transaction figure substitutes for that examination.
Ask whether the estimate incorporates renovations and upgraded finishes. Retain permits, plans, invoices, photographs, and finish specifications for custom work. These records help describe what must be valued, but documentation alone does not guarantee coverage.
The review should also distinguish improvements from belongings. Dwelling, other-structures, and personal-property coverage serve different functions. Have the broker identify where each significant item belongs under the applicable policy rather than assuming everything inside the residence shares one limit.
Jewelry, fine art, and other valuables may have special limits. Discuss whether scheduled-property endorsements are appropriate, and retain photographs and purchase records to support the contents inventory.
An estate can be underinsured even when its dwelling limit appears substantial. Depending on the policy, an insurer can require coverage equal to 80%, 90%, or 100% of replacement cost. The relevant percentage must come from the actual contract.
Ask the broker to compare the proposed limit with both the current reconstruction estimate and the policy's insurance-to-value requirement. Then ask how failing to meet that requirement would affect a covered partial loss. Underinsurance is not only a total-loss problem: it can reduce the amount payable for a smaller claim.
This review is especially important after improvements. An older limit should not go unexamined simply because the policy has continued to renew. Request confirmation that the revised valuation captures completed work and that the resulting limit meets the applicable requirement. Meeting a percentage test alone is not assurance of full reconstruction funding.
Ordinary replacement-cost protection and law-and-ordinance protection are distinct. Florida law requires an offer of coverage addressing additional costs of complying with laws governing construction, repair, use, demolition, and debris removal. Do not assume ordinary replacement-cost wording absorbs those expenses without a separate review.
The ordinance provisions identify 25% and 50% limits. On a $2 million dwelling limit, those percentages represent $500,000 and $1 million, respectively. These are arithmetic illustrations-not recommendations or evidence that either amount would be adequate for a particular residence.
Confirm the selected percentage, its dollar equivalent, and the applicable conditions. The statutory ordinance provision generally confines coverage to repairs of the damaged portion unless total damage exceeds 50% of the structure's replacement cost. Do not confuse that threshold with separate building-code or floodplain substantial-damage rules.
Have the broker and counsel explain how these provisions apply to the residence and its policy before treating the ordinance allowance as sufficient.
If an estate is reviewing a residence at Faena House Miami Beach, begin the insurance discussion with the actual ownership and occupancy arrangements, not assumptions about the address. Florida property coverage requires an actual insurable interest, making the interests of the owner and insured parties essential questions in the transfer.
Have estate counsel and the broker confirm who owns the residence, whose interests require protection, which parties should be insured, and when the intended coverage takes effect. Do not assume the seller's policy automatically transfers with the property.
If the estate will retain an unused residence, disclose that status and ask how vacancy or unoccupancy conditions affect coverage. Address the intended use during estate administration now, rather than leaving it for clarification after a loss.
Standard homeowners insurance does not cover flood damage. A homeowners policy therefore cannot, by itself, resolve the residence's flood exposure. Request a separate flood-coverage review rather than treating a substantial dwelling limit as comprehensive protection.
For an estate considering a residence at Alina Residences Boca Raton, this remains a property-specific inquiry; a project name does not establish the insurance response.
Translate any percentage hurricane deductible into dollars using the applicable insured value. A seemingly modest percentage can produce a substantial out-of-pocket obligation. Confirm the calculation and discuss how the estate would fund that obligation.
Before closing or committing to retain the residence, assemble the reconstruction estimate, improvement records, contents inventory, declarations, policy forms, exclusions, and endorsements. Request written clarification of unresolved questions about limits, insured interests, occupancy, and effective dates.
The objective is not merely a bound policy. It is a coverage decision grounded in the residence's current condition, with the remaining uninsured obligations understood. Estate counsel and the insurance broker should resolve the property-specific legal and contractual questions together.
For a considered perspective on South Florida's residential opportunities, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationA preclosing reconstruction appraisal is a risk-management recommendation, not a universal Florida legal requirement. Ask the broker what current valuation is appropriate for the residence and insurer.
Do not assume the purchase price or market value establishes an adequate dwelling limit. A current reconstruction estimate addresses the rebuilding exposure the policy is intended to insure.
Replacement cost uses current replacement prices, while actual cash value deducts depreciation. Replacement-cost protection remains subject to the policy's limits and terms.
Yes. Failing to maintain the policy's required percentage of replacement value can reduce the amount payable for a covered partial loss.
Retain permits, plans, invoices, photographs, and finish specifications, and ask whether the work is reflected in the reconstruction estimate. Those records do not themselves guarantee coverage.
No. Ordinary replacement-cost protection and law-and-ordinance protection are distinct, so the selected ordinance coverage and its conditions need separate review.
They equal $500,000 and $1 million respectively. Neither calculation establishes that the amount is adequate for a particular residence.
Do not assume it transfers. Estate counsel and the broker should confirm ownership interests, insured parties, and the intended coverage's effective date.
Vacancy or unoccupancy conditions can affect coverage. Ask the broker how the policy treats the residence's actual occupancy during estate administration.
Standard homeowners insurance does not cover flood damage, so flood requires a separate review. Any percentage hurricane deductible should also be translated into dollars using the applicable insured value.