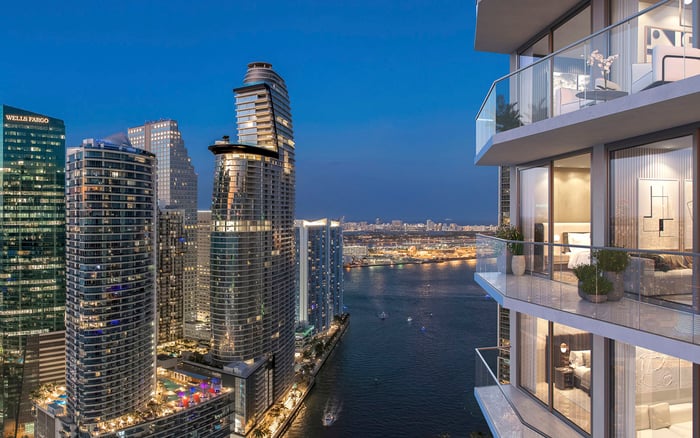
Making a Florida second home your primary residence calls for more than a change of address. Before closing, align the ownership and occupancy timeline, distinguish homestead tax benefits from creditor-protection questions, and review trust compatibility and portability with your advisers.
Turning a South Florida retreat into a primary residence changes how a home serves your life. Before it becomes a tax-planning decision, however, it must be an ownership-and-residency decision. A deed, an intention to move in and an exemption application are not interchangeable.
Florida’s homestead property-tax exemption generally requires legal title or beneficial title in equity and good-faith permanent residence as of January 1. For a buyer considering 2200 Brickell, the essential preclosing question is not simply whether the residence suits year-round living. It is whether ownership and permanent residency will align for the intended exemption year.
Keep three reviews separate: property-tax eligibility, creditor protection and estate-planning compatibility. A favorable answer in one does not settle the others. The objective is a coherent closing plan, not a reassuring label.
Ask your advisers to work backward from the relevant January 1. When will qualifying title be held? When will the property become the permanent residence? If the home is already owned as a second residence, what will substantiate the change in use?
Ownership alone does not satisfy the eligibility test, nor does an intention to relocate. The qualifying permanent residence may be the owner’s home or the home of someone legally or naturally dependent on the owner. Where that distinction matters, have counsel evaluate the specific arrangement rather than rely on shorthand descriptions of who will live there.
For a Miami Beach buyer considering 57 Ocean Miami Beach, the same discipline applies: selecting a residence and establishing qualifying permanent occupancy are separate steps. Ask which exemption year the proposed closing and occupancy dates can support. Do not build the first-year ownership budget around an exemption that has not been evaluated against that timeline.
The county property appraiser administers homestead applications, and the general filing deadline is March 1. Do not confuse that deadline with the January 1 eligibility date. Filing the application is a separate step from satisfying the underlying ownership and residency requirements.
Before closing, confirm the applicable county’s evidence requirements. Relevant records may include Florida identification, voter registration and vehicle registration, as applicable. Ask which documents your circumstances require and whether their timing supports the intended application.
Assign responsibility for filing. The buyer, counsel and other advisers should agree who will assemble the records, submit the application and follow up on its status. Keep the relevant documents together so the application presents a coherent record of ownership and residence, rather than a collection of disconnected address changes.
Moving between Florida homes does not transfer the old homestead exemption itself. The new residence must qualify for its own exemption. Eligible owners may transfer all or part of the previous Florida homestead’s Save Our Homes assessment difference through portability.
That distinction matters when comparing future carrying costs. The assessment difference is the gap between the former homestead’s just or market value and its assessed value-not a dollar-for-dollar reduction in the tax bill. Portability can transfer up to $500,000 of an eligible assessment difference to another qualifying Florida homestead, subject to the applicable eligibility analysis.
A buyer evaluating Alba West Palm Beach should therefore request a buyer-specific tax estimate rather than assume the seller’s assessment benefit will continue. In West Palm Beach or elsewhere, the relevant assumptions are the buyer’s own exemption and portability eligibility.
Review the three-assessment-year window for establishing a new homestead after abandoning the former one with the applicable property appraiser. Portability requires an application, generally due March 1. Assign responsibility for Form DR-501T and verify its acceptance. Also confirm the homestead exemption amount for the applicable tax year rather than treating a familiar historical figure as a permanent ceiling.
For a trust-based purchase, the question is not merely whether the trust can appear on the deed. Ask whether the proposed deed and trust, considered together, satisfy the legal-title or beneficial-title requirement for the intended homestead application.
Have counsel examine who holds the relevant ownership interest and how permanent occupancy fits the arrangement. Request a clear explanation of which provisions support the intended result and whether the county needs particular documentation to evaluate the application. Do not assume a trust’s estate-planning purpose establishes property-tax eligibility.
The same questions deserve attention when evaluating Andare Residences Fort Lauderdale. A Fort Lauderdale address does not replace review of the actual ownership documents. If a later transfer into or out of a trust is contemplated, ask whether it would change the tax, financing or creditor-protection analysis before treating the transfer as routine.
A property-tax exemption does not settle questions of protection from creditors. Before closing, ask counsel to identify which existing judgments, liens, tax claims, bankruptcy issues or pending disputes could affect the purchase. Then ask what protection the proposed ownership structure would provide in those circumstances.
A useful answer is specific to the buyer, property and documents. Do not rely on an assurance that “Florida homestead” resolves every exposure. Ask counsel to distinguish the tax analysis from the creditor analysis and explain any unresolved issues before funds are committed.
Marriage and estate planning require their own questions. Must a spouse sign any closing documents? Does the proposed estate plan comply with applicable homestead restrictions? Would a future ownership change alter those conclusions? These matters call for individualized legal review, not assumptions carried forward from an exemption application.
Before signing, request a concise written plan identifying the intended exemption year, qualifying ownership structure, permanent-residency timeline and supporting records. It should also assign responsibility for the homestead application and, where relevant, the portability application.
Ask for a tax estimate that separates confirmed facts from assumptions. Keep the seller’s assessment history distinct from the buyer’s expected treatment, and resolve trust, creditor and spouse-signature questions through counsel rather than allowing the closing calendar to dictate them.
The best transition from seasonal retreat to primary home is deliberate: the residence fits daily life, the documents reflect the intended ownership, and the filings follow a verified timeline. General guidance can frame that conversation, but it does not replace legal or tax advice tailored to the transaction.
Explore South Florida residences for your next chapter with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationQualifying legal or beneficial ownership and good-faith permanent residence generally must exist as of January 1 for the intended exemption year.
No. Ownership or an intention to relocate does not complete the test; the qualifying permanent-residence requirement must also be satisfied.
The qualifying residence may be the owner’s home or the home of someone legally or naturally dependent on the owner. Have counsel review the particular arrangement.
The general filing deadline is March 1, and the county property appraiser administers the application. That deadline is separate from the January 1 eligibility date.
Confirm the county’s requirements for applicable Florida identification, voter-registration and vehicle-registration records. Ask which evidence is needed for your circumstances.
No. The new property needs its own qualifying exemption, although eligible owners may transfer an assessment difference through portability.
Portability can transfer up to $500,000 of an eligible Save Our Homes assessment difference. It is not a dollar-for-dollar tax-bill reduction.
Assign responsibility for Form DR-501T, verify its acceptance and coordinate it with the homestead application. The general portability filing deadline is March 1.
No automatic qualification should be assumed. Counsel should review whether the deed and trust preserve qualifying ownership and support the intended permanent-residence arrangement.
Do not treat tax eligibility as a creditor-protection conclusion. Ask counsel to assess relevant claims, the ownership structure and any spouse-signature or estate-planning questions separately.