A South Florida purchase funded by deferred compensation begins with plan-specific payout rights, a California residency analysis, and a realistic calculation of after-tax capital. Preserve liquidity for insurance, property taxes, and ownership costs before setting the offer ceiling.
For a California household considering South Florida, deferred compensation can make a substantial residential purchase possible. But the balance on a benefits statement is not the amount available at closing. The more useful figure is what remains after projected taxes, transaction costs, and ownership reserves.
Lifestyle priorities belong in the search, but they should follow a clear capital plan. A residence that appears affordable against a gross distribution may look quite different once tax payments, insurance deductibles, and ongoing expenses are funded. The objective is not simply to complete the acquisition. It is to retain enough liquidity to enjoy the home without depending on another distribution that may not be available when needed.
Governmental 457(b), nongovernmental 457(b), and other deferred-compensation arrangements are not interchangeable. Before discussing withdrawal timing, rollover options, or purchase capacity, obtain the plan documents and confirm exactly which arrangement holds the money.
Eligible 457(b) plans generally permit distributions after separation from employment, subject to their distribution provisions. That does not mean every participant can select any payment date or structure. Ask the administrator to confirm permitted payout forms, election requirements, processing timelines, and any restrictions relevant to the proposed closing.
Do not assume installments are available. If the plan permits them, compare that schedule with other permitted options using a tax projection and a dated purchase budget. An unforeseeable-emergency provision is not a substitute for ordinary purchase planning: eligibility depends on applicable rules and plan terms.
Governmental 457(b) distributions generally avoid the federal 10% early-distribution tax, including before age 59½. That exception, however, generally does not cover amounts attributable to rollovers from another retirement plan or IRA. Avoiding the additional tax does not, by itself, establish the distribution's total tax cost.
Coordinate relocation and distribution timing, but do not treat one as proof of the other. Buying a Florida residence does not, by itself, determine how California will treat a later deferred-compensation payment.
Do not assume a blanket California exemption for payments received after a move. Before choosing a distribution date, obtain a residency- and plan-specific analysis of the actual arrangement and proposed payment schedule.
Keep move documentation organized and have advisers identify what supports the intended residency position. Let the purchase calendar follow that analysis, rather than forcing a tax conclusion to accommodate a preferred closing date. If the answer remains unresolved, maintain a conservative tax reserve instead of counting anticipated savings as available purchase capital.
The calculation is straightforward: gross distribution minus projected total taxes, transaction costs, and retained reserves equals net purchase capital from that distribution. Evaluate any other funds or financing separately rather than assuming their availability.
Withholding requires particular care. It is a prepayment toward tax, not an additional tax layered onto the projected liability. If the model already subtracts total projected taxes, subtracting withholding again understates available capital. Conversely, treating the deposited payment as entirely spendable can leave too little for any remaining tax obligation.
Prepare both a total-capital calculation and a cash-timing schedule. The first establishes affordability; the second checks whether funds will be available for deposits, closing, and tax payments. A permitted installment schedule may not align with contractual purchase obligations.
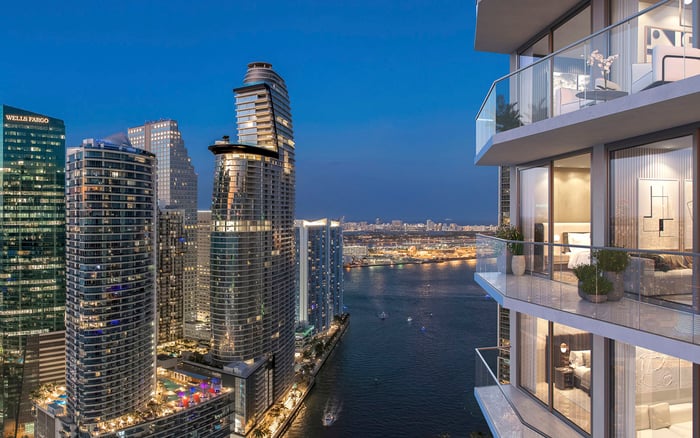
For a Brickell search that includes The Residences at 1428 Brickell, use the same after-tax ceiling applied to every alternative. The project belongs in the lifestyle comparison, not as a reason to relax the reserve policy.
Investment discipline means evaluating ownership costs alongside the purchase price. Before committing the full net distribution, obtain address-specific insurance quotes and review coverage limits, exclusions, and deductibles with a qualified insurance adviser.
Federal flood insurance generally limits residential building coverage to $250,000 and contents coverage to $100,000. Those limits can leave a substantial gap for a luxury home. Establish the protection appropriate for the property rather than assuming a standard policy covers the entire exposure.
Roof condition and wind-mitigation inspections also deserve attention. Qualifying mitigation features may produce premium credits, but the property's actual insurability and quoted cost should guide the budget. Reserve liquidity for deductibles and storm repairs separately from annual premiums.
A Miami Beach comparison involving The Perigon Miami Beach should therefore address insurance early. A generic coastal insurance allowance does not resolve the ownership budget for a particular residence.
Florida's homestead exemption can reduce a qualifying residence's taxable value. It is not a dollar-for-dollar reduction in the property-tax bill. The Save Our Homes assessment limitation can also restrict annual assessed-value increases after a property qualifies for homestead treatment.
Neither benefit should enter the purchase model as an automatic, immediate saving. Confirm eligibility, documentation, application requirements, and filing deadlines with the county property appraiser. Have the property-tax budget reviewed for the intended purchase rather than assuming a displayed historical bill represents the buyer's future obligation.
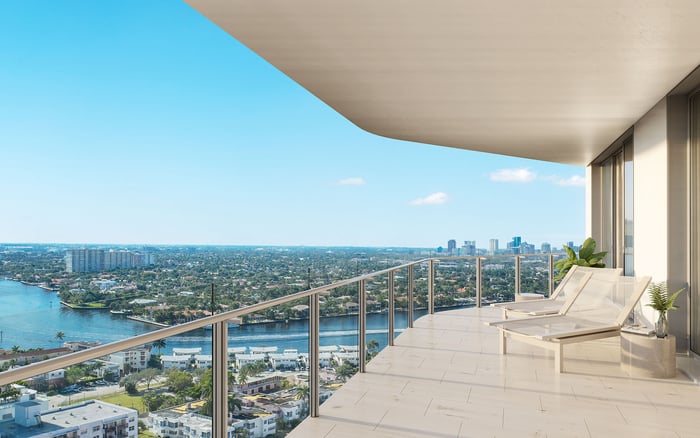
When considering Alba West Palm Beach, keep the residence decision distinct from the homestead eligibility review. The same discipline applies whether the home is intended as a primary residence or its role remains under consideration.
Retained reserves should cover property taxes, insurance, maintenance, storm repairs, and any applicable assessments. Where association obligations apply, request the relevant financial and ownership documents before finalizing the budget. Funds reserved for a future tax payment should not also be counted as an emergency cushion.
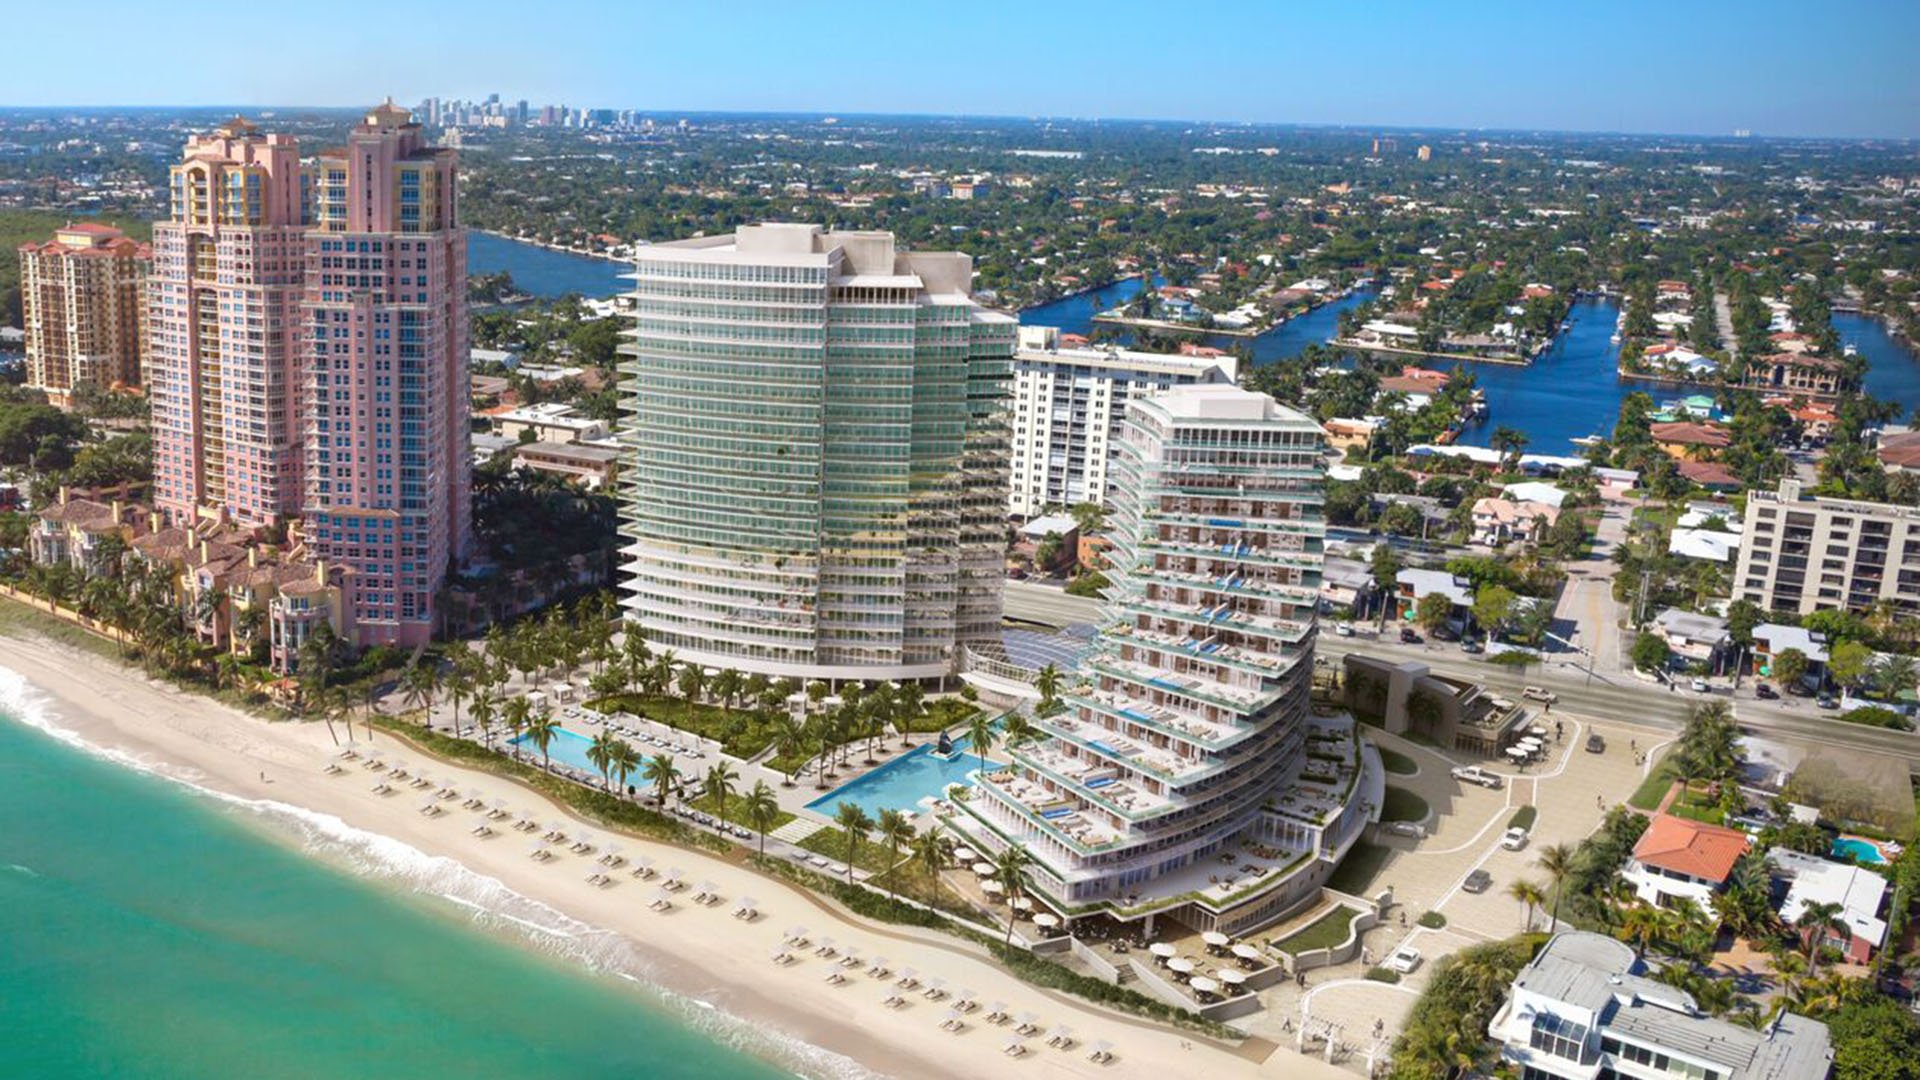
A Fort Lauderdale search that includes Andare Residences Fort Lauderdale can proceed alongside this work. Shortlisting residences and determining a defensible offer ceiling are complementary tasks, but they are not the same decision.
The sequence matters: confirm the plan, compare permitted payouts, document the move, obtain tax projections and property-specific insurance quotes, then set the maximum offer. Revisit the calculation if the payout schedule or purchase terms change. The strongest purchase plan leaves the buyer with a home that fits and capital that remains available afterward.
For a discreet South Florida search shaped around your after-tax purchase capacity, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationEligible 457(b) plans generally permit distributions after separation from employment, subject to plan provisions. Confirm your access, payout terms, and projected tax obligations before committing funds.
No. Governmental 457(b), nongovernmental 457(b), and other deferred-compensation arrangements require separate analysis of payout rights and tax treatment.
No. Confirm the permitted payout forms and election requirements with the plan administrator before designing a staged-distribution purchase strategy.
No blanket exemption should be assumed. Obtain a residency- and plan-specific analysis before selecting the distribution date or counting potential savings toward the purchase.
They generally avoid that additional tax, including before age 59½. The exception generally does not cover amounts attributable to rollovers from another retirement plan or IRA.
Subtract projected total taxes, transaction costs, and retained reserves from the gross distribution. Evaluate other funds or financing separately.
No. Withholding is a tax prepayment, so subtracting both total projected taxes and withholding would count the same obligation twice.
No. The exemption reduces qualifying taxable value, while Save Our Homes can limit annual assessed-value increases after qualification; confirm application requirements locally.
Yes. Residential building coverage generally tops out at $250,000 and contents coverage at $100,000, potentially leaving a substantial gap.
Budget separately for property taxes, insurance, deductibles, maintenance, storm repairs, and applicable assessments. Keep funds for outstanding tax obligations distinct from emergency liquidity.