At Origin Bay Harbor Islands, portfolio mortgages and securities-backed credit lines create different paths to settlement. The essential distinction is between clearing mortgage underwriting and maintaining investment-backed borrowing capacity, with contract timing, proof of funds and backup liquidity shaping both strategies.
For a buyer considering Origin Bay Harbor Islands, the financing decision is not simply whether to borrow. It is which conditions must be met before funds reach the closing table-and which risks remain afterward. A portfolio mortgage and a securities-backed credit line can both support a purchase, but each requires different preparation.
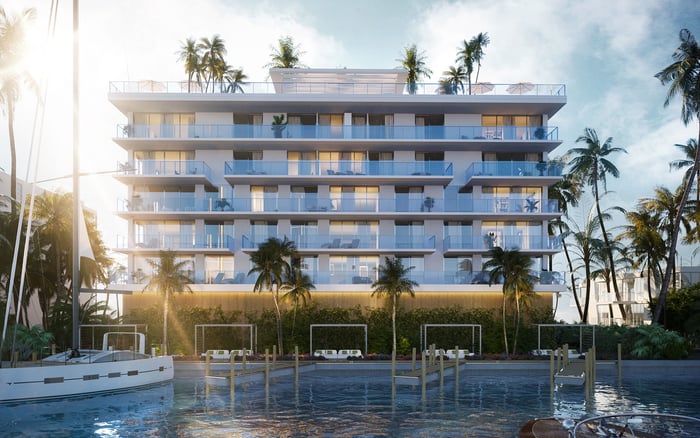
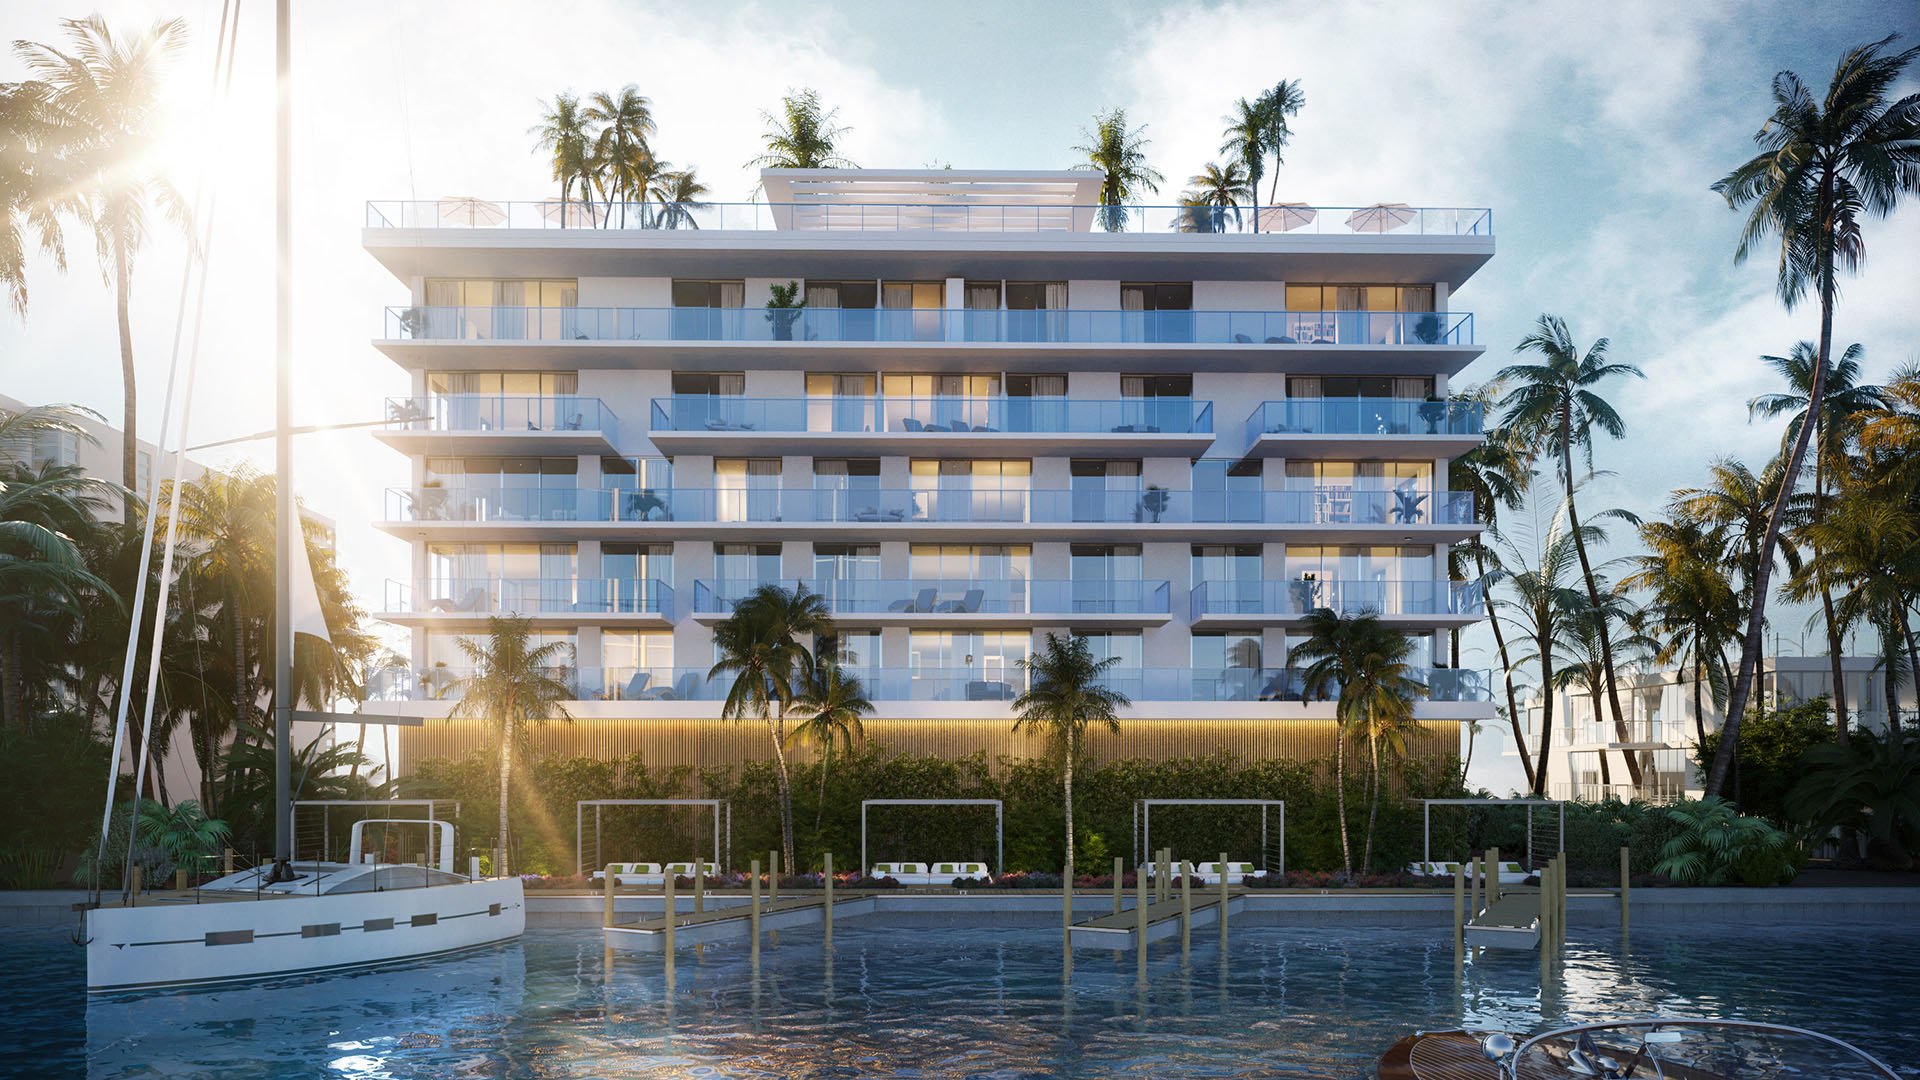
Origin is a 27-unit waterfront condominium at 9740-9760 West Bay Harbor Drive in Bay Harbor Islands. Its anticipated completion target is late 2026, not a guaranteed individual closing date. Buyers should distinguish the development timeline from their contractual payment obligations and their lender’s readiness to fund.
The central distinction is straightforward: mortgage financing depends on clearing lender underwriting; securities-backed borrowing depends on eligible collateral and available credit capacity. Neither should be treated as committed closing liquidity simply because the buyer has substantial assets.
Preconstruction purchases generally involve staged deposits, with the remaining balance due at completion. That pattern does not establish Origin’s deposit percentages, due dates or acceptable funding sources. Build the purchase plan around the executed agreement, with counsel confirming obligations before selecting a financing strategy.
Ask specifically about financing contingencies, the treatment of borrowed deposit funds and the steps that establish the closing deadline. Do not assume these protections or permissions apply at Origin. Test a proposed borrowing arrangement against the contract rather than using it to infer what the contract allows.
Origin’s $30.5 million construction loan is development financing, not a mortgage offer to individual buyers. It establishes neither buyer loan eligibility nor lender approval of a particular purchase.
For buyers also considering Bay Harbor Towers, a useful comparison begins with a separate contract-and-funding review for each residence-not an assumption that both share a deposit structure.
For a buyer pursuing portfolio or jumbo mortgage financing, the practical closing question is whether the lender has completed the work required to release funds. Credit, down payment, debt-to-income and reserve requirements vary by lender and loan size. No single portfolio-loan threshold can safely be applied to every Origin purchaser.
Expect appraisal, income documentation and reserve verification to be addressed before funding. Ask the lender to identify outstanding conditions, who is responsible for each item and what still stands between the application and the release of funds. The conversation should address the specific purchase, not merely a broad indication of borrowing capacity.
Costs deserve a separate budget. Portfolio or jumbo financing can add lender, appraisal and underwriting charges to the property transaction’s closing expenses. Request a transaction-specific estimate rather than treating the loan amount as the entire funding requirement.
For this route, the priority is underwriting readiness: the buyer needs a lender able to fund the actual transaction when the contract requires payment.
A securities-backed credit line, or SBLOC, is revolving borrowing secured by eligible investment assets. It can provide purchase liquidity without an immediate sale of the pledged holdings. These lines are typically non-purpose credit: real estate purchases may be permitted, while securities purchases are not.
Before relying on a line, confirm collateral eligibility, custody arrangements, advance rates, permitted uses, interest rates, fees and minimum draws. The investment account’s headline value is not its available borrowing capacity. What matters is how the provider treats the assets and how much is available to draw when needed.
An SBLOC can fund an entire settlement or serve as a narrower bridge, including a down payment and other purchase costs while an existing home awaits sale or closing. For an Origin buyer, any proposed deposit use still requires contractual confirmation. If a mortgage will fund the balance, ask that lender how the borrowed funds fit its underwriting requirements.
This is a liquidity tool, not a substitute for transaction-specific approval.
From the seller’s perspective, an SBLOC can support an all-cash purchase. For the buyer, the obligation remains debt secured by investments. Keep that distinction in view when evaluating cost, exposure and repayment.
Arrange proof of funds acceptable to both the seller and title company before treating the line as settlement money. A custodian letter or credit-capacity statement may be appropriate, but confirm acceptability rather than presume it.
Then establish the transfer route. Will proceeds move directly from the lender or custodian to escrow, or first through the buyer’s account? Confirm the required documentation and wire cutoffs with the parties handling the transfer. Approved capacity and delivered funds are different milestones.
The same discipline applies if the search extends to Rivage Bal Harbour. Comparing residences does not make funding arrangements interchangeable. Each proposed purchase warrants its own confirmation of documentation, contract requirements and settlement logistics.
The defining SBLOC risk is collateral capacity. Falling securities values can reduce available borrowing and trigger demands for additional collateral or repayment. Those demands can lead to securities liquidation, undermining the original intention to avoid selling investments.
A short holding period does not remove that exposure. Even a line drawn only to bridge settlement remains subject to collateral-value risk until repaid. Identify backup liquidity and discuss how a market decline would affect both the anticipated draw and the outstanding balance.
If repayment is expected from a home sale, consider the consequences of a delayed closing. If the intended exit is a later mortgage, do not treat refinancing as guaranteed. A bridge strategy should remain workable without assuming the next financing event will occur exactly as planned.
Fee comparisons also require precision. A credit line advertised without product-level closing costs does not eliminate the property purchase’s closing expenses. Nor should one provider’s terms be generalized to another.
Before settlement, reconcile the remaining contractual balance, purchase costs, expected borrowing proceeds and cash contribution. For mortgage financing, focus on unresolved underwriting conditions. For an SBLOC, focus on current drawable capacity, acceptable proof of funds, transfer arrangements and backup liquidity.
The more suitable structure is the one whose conditions, costs and repayment risks fit the buyer’s circumstances. At Origin, a considered capital plan should serve the purchase without confusing wealth with immediately accessible funds-or a completion target with a binding closing appointment.
For a discreet conversation about Origin and your South Florida residential search, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationOrigin is a 27-unit waterfront condominium at 9740–9760 West Bay Harbor Drive in Bay Harbor Islands.
No. Late 2026 is the anticipated completion target, not a guaranteed individual closing date; buyers should confirm their contractual timing.
No. The $30.5 million construction loan is development financing and does not establish an individual buyer’s mortgage eligibility.
The deposit schedule must be confirmed in the purchase agreement. General preconstruction practices do not establish Origin’s percentages or payment dates.
Buyers should expect appraisal, income documentation and reserve verification to be addressed before funds release. Specific requirements vary by lender and loan size.
SBLOCs typically permit real estate purchases but prohibit using proceeds to buy securities. Confirm the provider’s permitted uses and the purchase contract’s requirements.
Yes, from the seller’s perspective. The buyer still owes debt secured by pledged investments.
Confirm documentation acceptable to the seller and title company, potentially a custodian letter or credit-capacity statement. Also establish the transfer route and wire cutoffs.
Borrowing capacity can fall, and the provider may demand additional collateral or repayment. Securities liquidation may follow, even during a short bridge period.
No. Later refinancing should not be assumed, so the repayment plan should include backup liquidity and account for potential delays.