For London buyers considering Coral Gables, the property-tax decision begins with intended use. Understand assessment resets, homestead and nonhomestead protections, and the timing of a future Florida move before treating a seller’s tax bill as your own.
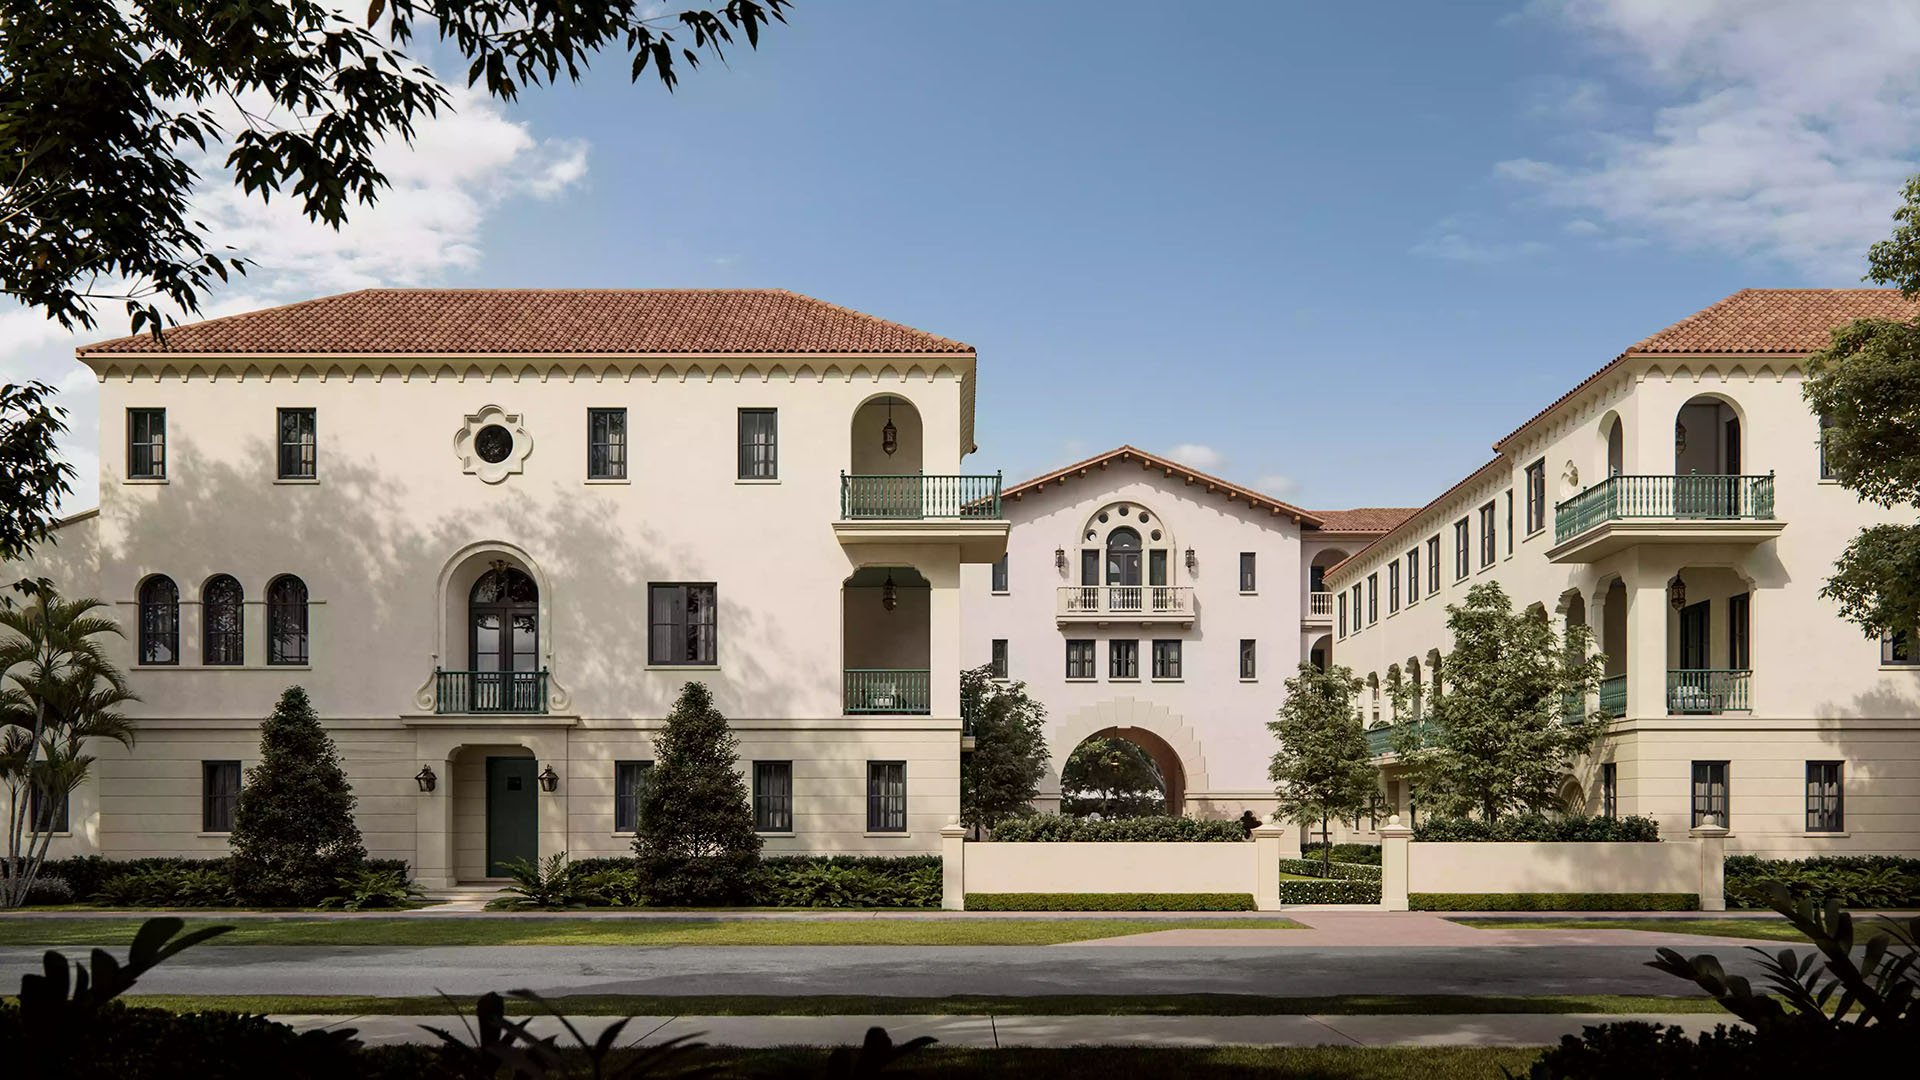
A move from London to Coral Gables invites decisions about architecture, privacy and the rhythm of daily life. Yet one of the most consequential choices is less visible: whether the residence will be a qualifying permanent Florida home or a second home. That distinction shapes property-tax carry throughout ownership and the assessment benefits that may matter when you move again.
Ownership alone does not establish homestead eligibility. A Coral Gables address, however central to your plans, is not enough: you must meet the qualifying permanent-residence requirements. Before comparing acquisition budgets, establish which tax position you can reasonably expect to hold.
For a buyer considering The Village at Coral Gables, the first question is not simply what the residence costs, but what it will cost to hold under the household’s actual pattern of use. Confirm eligibility individually rather than treating relocation from London as an automatic qualification.
The tax bill for a long-held property can be an unreliable guide to a purchaser’s carrying cost. Save Our Homes, often shortened to SOH, can create a substantial difference between market value and capped assessed value. That accumulated protection generally does not pass to the purchaser in an ordinary sale.
An ordinary ownership change generally resets a homestead assessment to just value on January 1 of the following year. A qualifying ownership change can also remove an accumulated nonhomestead assessment limitation. In either case, the seller’s protected assessment is not a dependable basis for your acquisition budget.
Keep three terms distinct. Just value represents the property’s market valuation for assessment purposes. Assessed value reflects applicable assessment limitations. Taxable value reflects applicable exemptions, with treatment potentially differing among taxing authorities. The purchase price should not simply be relabelled as taxable value.
Request a property-specific projection that separates those values and applies the relevant millage rates. The seller’s current bill remains useful context, but it belongs beside your forecast, not in place of it.
For a qualifying homestead, SOH limits annual assessed-value growth to the lower of 3% or the applicable Consumer Price Index change. Protection begins in the second year the property receives a homestead exemption. It does not preserve the seller’s assessment when you buy.
The distinction matters when evaluating Ponce Park Coral Gables or any other residence on a long-term shortlist. Eligibility and the timing of protection belong in the financial comparison; neither should be assumed from the property’s identity.
The 2.9% SOH cap for 2025 is a historical reference, not a fixed rate to carry through a future ownership model. Nor does SOH cap the total tax bill. Applicable exemptions and taxing authorities’ millage rates also affect the amount payable.
If market value rises faster than capped assessed value, an assessment difference can accumulate. Longer ownership alone does not guarantee that outcome, and no particular holding period assures a specified saving.
For qualifying nonhomestead property, including eligible second homes and investment properties, the annual assessment-growth cap is 10%. It limits qualifying assessed-value growth; it does not predict a 10% increase every year.
The limitation does not apply to school-board assessments. School taxes therefore do not receive the same assessment-growth protection, and the nonhomestead cap should never be applied to the entire tax calculation.
Qualifying property receives this limitation automatically, without a separate application for the cap. That administrative simplicity does not make accumulated savings transferable: nonhomestead assessment savings are not portable to another property.
If Cora Merrick Park enters a shortlist for a home intended initially for occasional use, model that use rather than assuming immediate homestead treatment. A later change in the household’s plans warrants a fresh eligibility review. Neither the 10% limitation nor possible future homestead qualification should substitute for a post-transfer assessment estimate.
A disciplined comparison separates three views of the same residence: the seller’s current bill, your projected post-reset carry and a future buyer’s projected post-reset carry. Each answers a different question.
The seller’s bill explains the existing ownership position. Your projection tests affordability after transfer, using the expected assessment treatment, any confirmed exemptions and applicable millage assumptions. The future-buyer projection tests how the next purchaser might assess carrying cost without inheriting your accumulated protection.
For the ownership period, ask advisers to test more than one market-value and millage scenario. Keep school and non-school treatment distinct where the nonhomestead limitation applies. These are planning scenarios, not forecasts of valuation or tax policy.
Review the intended ownership structure before acquisition, too. Transfers of legal or beneficial ownership can trigger reassessment outside a conventional sale. A later trust or entity change therefore deserves transaction-specific advice, not an assumption that the tax position will remain untouched.
A London property supplies no Florida portability benefit. Portability concerns an eligible SOH assessment difference from a previous Florida homestead, not equity or tax history accumulated overseas.
For an eligible later move between Florida homesteads, portability can transfer up to $500,000 of that assessment difference. This is an assessment reduction-not a cash payment, an automatic allowance or a dollar-for-dollar tax saving. The available amount and transfer calculation require individual confirmation.
The eligibility window spans three tax years, making January 1 homestead dates relevant when coordinating a sale and replacement purchase. Map those dates before fixing the sequence of a future move. Do not treat the rule as a generic period measured only from closing day.
Your future purchaser generally will not inherit your accumulated assessment protection. Resale planning should therefore distinguish the tax bill you have enjoyed from the buyer’s likely post-transfer assessment. A lower owner-specific bill does not establish a resale premium or a shorter marketing period.
The strongest property decision remains financially comfortable once the seller’s tax history is set aside. Confirm intended use, obtain a post-reset carry estimate and review ownership structure before committing. Revisit portability and the next buyer’s assessment position when a future move becomes concrete.
For a London household, this approach keeps the lifestyle decision and financial commitment aligned: choose the residence for the life it supports, while budgeting for the tax position you can substantiate.
Explore your Coral Gables property options with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. Homestead benefits require a qualifying permanent Florida residence, and eligibility must be confirmed individually.
Generally not. An ordinary homestead ownership change generally resets the assessment to just value on January 1 of the following year, while qualifying nonhomestead ownership changes can also remove accumulated protection.
No. Just value, assessed value and taxable value are distinct, and applicable assessment limitations and exemptions affect the calculation.
SOH protection begins in the second year the property receives a homestead exemption. It limits annual assessed-value growth to the lower of 3% or the applicable Consumer Price Index change.
No. The 2.9% cap applied to 2025 and should not be treated as a fixed rate for future years.
Qualifying nonhomestead property has a 10% annual assessment-growth cap, but that limitation does not apply to school-board assessments. It does not cap the total tax bill.
Qualifying nonhomestead property receives the limitation automatically, without a separate application for that cap. Accumulated nonhomestead assessment savings are not portable.
No. Portability transfers an eligible SOH assessment difference from a previous Florida homestead, not from a London property.
An eligible owner may transfer up to $500,000 of an SOH assessment difference to another Florida homestead, subject to individual calculations and eligibility. It is an assessment reduction, not cash or a dollar-for-dollar tax saving.
The three-tax-year eligibility window makes January 1 homestead dates important when coordinating a replacement Florida home. Separately model the future purchaser’s post-transfer assessment because that buyer generally will not inherit your accumulated protection.