For a Dubai-based buyer, a Downtown Miami residence is both a lifestyle choice and a sequence of capital commitments. Aligning staged deposits, property-sale proceeds and separately confirmed financing helps preserve flexibility from contract through closing.
A move from Dubai to Downtown Miami invites an appealing comparison of residences, views and daily routines. The more consequential comparison, however, may be between payment calendars. The purchase price defines the size of the commitment; the contract determines when that commitment must become cash.
For a buyer whose wealth spans property, investments and banking relationships, the central question is not simply whether the residence is affordable. It is whether every contractual milestone can be funded without relying on an uncompleted sale or unconfirmed borrowing. Staged payments spread capital deployment, but buyers should not treat committed funds as freely available liquidity.
A shortlist that includes Waldorf Astoria Residences Downtown Miami should therefore begin with two parallel assessments: residential suitability and the proposed transaction’s funding requirements. Neither should be an afterthought.
Build the deposit plan from the applicable purchase documents. Confirm the actual percentages, deadlines and triggers rather than assigning a general market assumption to a particular tower.
One hypothetical structure is 10/10/10/10/60: four installments of 10%, followed by 60% at closing. This is a cash-flow illustration, not a statement of any project’s terms. Ask whether the proposed contract ties payments to calendar dates, contract execution or construction milestones such as groundbreaking or top-off.
Calendar deadlines matter just as much as construction triggers. Establish how soon the next installment would follow signing. An early concentration of payments can matter more to a relocating buyer than the anticipated delivery date.
When evaluating Casa Bella by B&B Italia Downtown Miami, request the transaction’s current payment schedule rather than carrying over assumptions from another property. Compare the amount due immediately, the next contractual payment and the cumulative commitment before title transfers.
Consider an illustrative $4 million purchase using the 10/10/10/10/60 structure. Each 10% installment equals $400,000. Four installments total $1.6 million before closing, leaving a $2.4 million purchase-price balance.
This example covers only the purchase price. It is not an all-in acquisition budget, and the closing balance is not the total cash needed to complete the transaction and relocation. Ask advisers to prepare those additional budgets separately rather than embedding unsupported allowances in the purchase model.
For each deposit, record four items: the dollar amount, the contractual trigger, the intended funding source and the backup source. Distinguish available cash from expected sale proceeds and borrowing still under discussion.
The test is practical: if the next payment became due under the contract, could it be met without another transaction completing first? If not, resolve that dependency before signing rather than leaving it for later.
Evaluate a mortgage intended for closing separately from the funds required for earlier deposits. A plan to finance the remaining purchase-price balance at closing does not establish funding for construction-period installments.
If considering portfolio-backed borrowing, verify its availability with the lender rather than assuming access. Ask the bank to confirm whether the proposed facility can fund the intended payments, what collateral it would require and what conditions would govern access to funds. Do not insert an assumed advance rate or borrowing limit into the acquisition model.
Likewise, ask a prospective mortgage lender to assess the specific buyer and transaction. Neither a substantial investment portfolio nor an existing banking relationship substitutes for confirmation of the proposed financing. Keep the closing plan distinct from the deposit plan, even when both involve the same institution.
For planning purposes, separate committed deposits, accessible funds for upcoming installments, the closing balance and a relocation reserve. Assign each dollar only once. This reveals competing demands on the same capital before the purchase becomes binding.
For a buyer redeploying proceeds from a Dubai property sale, the relevant destination is not merely the Miami closing account. Those proceeds may need to fund several earlier payments. Map the expected sale completion and transfer timing against every deposit obligation.
Use both dates and events in that exercise. A payment tied to contract execution differs from one tied to groundbreaking or top-off. Ask counsel to clarify the trigger, required notice and payment deadline rather than converting every milestone into an assumed calendar date.
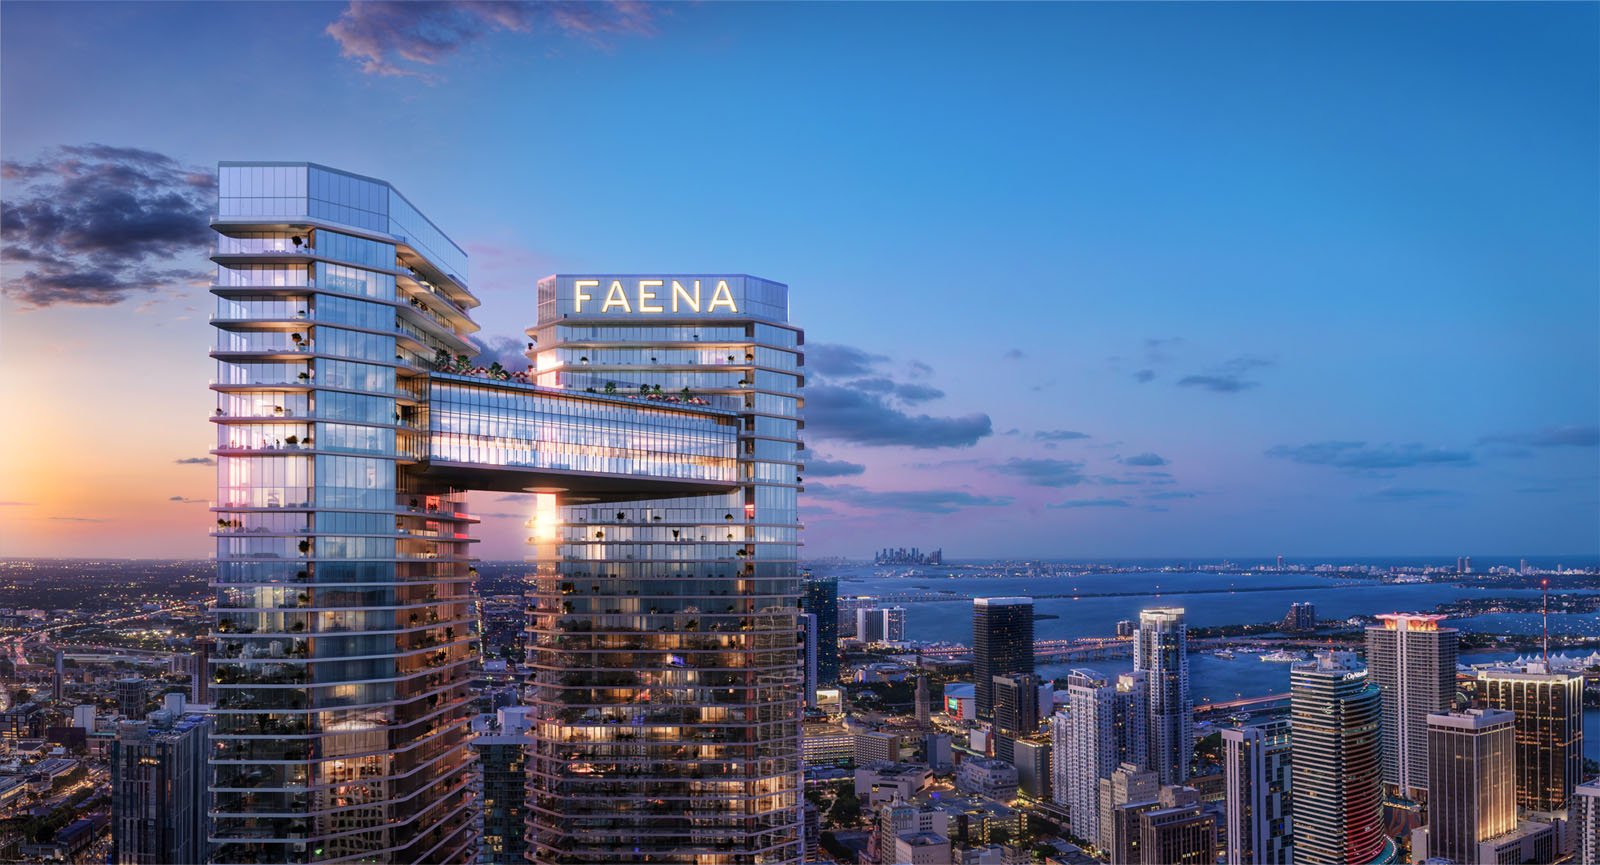
Apply the same discipline when reviewing Faena Residences Miami Downtown Miami: evaluate the proposed purchase price, documented payment sequence and delivery expectations together. No illustrative schedule here should be read as that project’s terms.
Then test a less convenient sequence: the Miami installment falls due before the Dubai proceeds are accessible. Identify how that payment would be met, or whether the transaction should be reconsidered. A relocation plan is more resilient when it does not require two separate property transactions to align perfectly.
Ask counsel whether and when deposits become non-refundable, including any applicable cancellation periods and legal rights. Do not assume that money paid in stages remains freely accessible until completion.
Have counsel establish the exact deposit percentages, payment deadlines and escrow-release conditions. Do not treat an escrow arrangement as a blanket assurance of protection or immediate recoverability. Request an individual review of the operative documents and applicable rights.
If an exit before completion matters, ask specifically about assignment restrictions and the consequences of missing a required deposit. Do not build the funding plan around an assumed ability to transfer the contract or recover committed money on demand.
If the search extends into Brickell, apply the same comparison to Baccarat Residences Brickell. The meaningful comparison is not simply tower against tower. It is purchase price, payment timing, delivery expectations and contractual flexibility considered together, without assuming identical terms.
The preferred residence should fit both the life being planned and the capital available to support it. Establish how each deposit will be funded, confirm any intended borrowing and preserve a separately considered relocation budget before making the final selection. Financial clarity keeps the residential decision deliberate rather than deadline-driven.
Explore your Downtown Miami property priorities with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationUse the percentages and deadlines in the applicable purchase documents. Do not assign an assumed market-wide deposit requirement to a particular tower.
It means four installments of 10% before closing, followed by 60% at closing. Here it is a hypothetical illustration, not a project-specific requirement.
It would require four $400,000 deposits, totaling $1.6 million before closing, and a $2.4 million closing balance. Those figures cover the purchase price only.
Confirm the first installment and the deadline for the next payment in the purchase documents. Test whether both can be funded without relying on an unfinished sale or unconfirmed borrowing.
A closing mortgage should not be assumed to fund construction-period deposits. Earlier installments need a separately established funding plan.
No borrowing availability, limit or facility terms should be assumed. Ask the lender to confirm the proposed funding arrangement for the buyer and intended payments.
Match expected sale completion and transfer timing to each Miami deposit milestone, not just final delivery. Identify a backup if proceeds are not accessible when an installment is due.
Do not assume refundability. Ask counsel to establish the applicable cancellation periods, refund conditions and legal rights for the specific transaction.
Counsel should confirm exact percentages, payment triggers, deadlines and escrow-release conditions. Assignment restrictions and consequences of missing a deposit also warrant review.
No. Counsel should examine assignment restrictions before a buyer relies on a pre-completion exit as part of the liquidity plan.