A buyer-focused framework for reviewing waterfront obligations, marine structures, shoreline rights, and insurance when acquiring a Palm Beach Gardens home through a trust or entity.
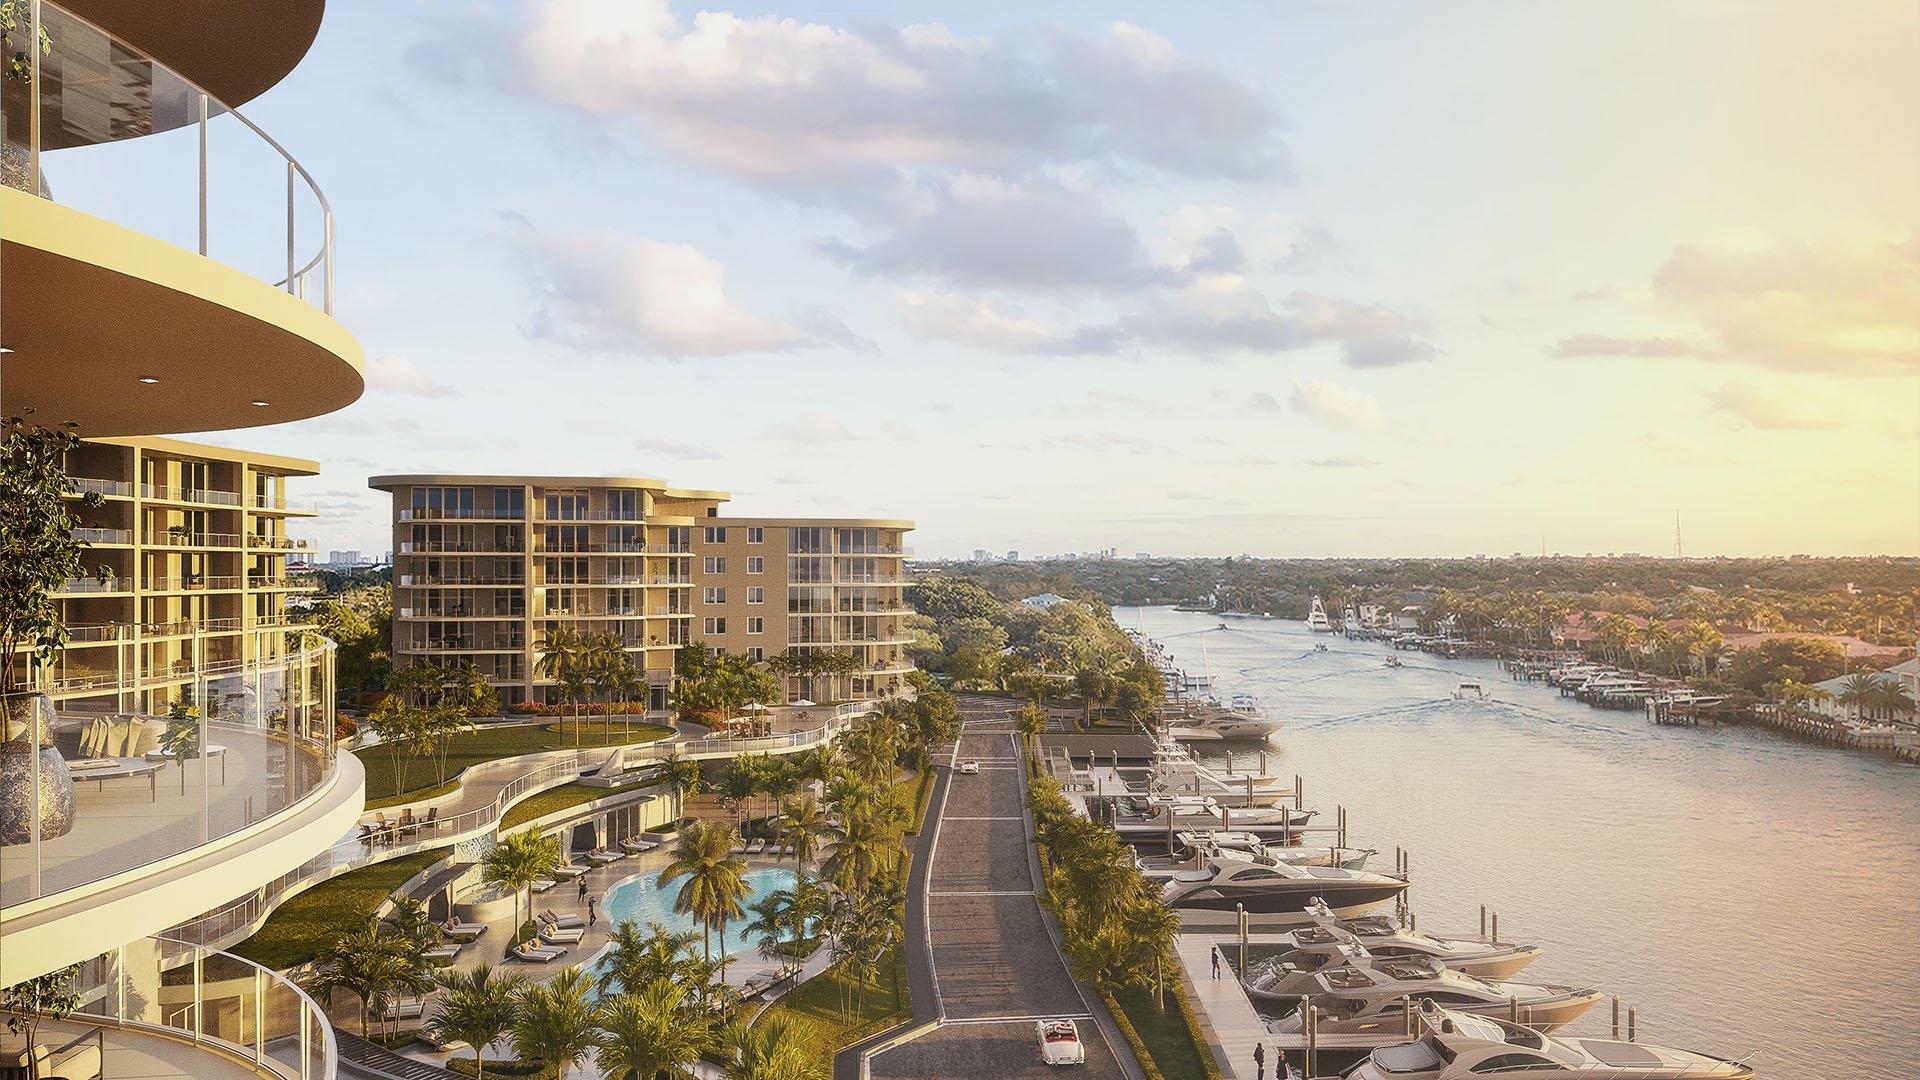
In Palm Beach Gardens, a waterfront purchase warrants scrutiny beyond the residence itself. The seawall, submerged dock components, usable water depth, and maintenance documents deserve the same attention as architecture and outlook. For buyers acquiring through a trust or entity, the objective is clear: establish what the property includes, who must maintain it, and whether the proposed ownership and use can be insured on acceptable terms.
Keep three questions separate: what is physically sound, what is legally authorized, and who pays when work becomes necessary. A satisfactory answer to one does not resolve the others. Treat this as a property-specific review, not a uniform Palm Beach Gardens rulebook. Maintenance duties and shoreline constraints must be established for the actual parcel and community.
Ask your attorney and insurance adviser to review the intended purchaser before the due-diligence period closes. Provide the proposed trust or entity name and explain how the residence will be occupied. Request written confirmation of the appropriate insurance arrangement; do not assume personal and entity ownership will receive identical treatment.
Nor should you assume that a trust or LLC automatically turns an owner-occupied residence into a commercial or investment insurance risk. Obtain a current determination for the specific ownership, occupancy, property, and policy under consideration.
For buyers also considering The Ritz-Carlton Residences® Palm Beach Gardens, apply the same discipline: ask which obligations attach to the residence, which are shared, and where those allocations are documented. A project name alone does not answer those questions.
At single-family waterfront properties, individual owners generally bear responsibility for the seawall, although some communities assign shared maintenance to an association. Do not rely on a seller's description of what the community usually handles. Review the governing documents and ask counsel to identify the provisions that apply to the property.
Prepare a responsibility schedule covering the seawall, dock, adjoining shoreline structures, and waterway maintenance. For each item, identify the responsible party, supporting document, known condition, and unresolved expense. Ask about past and pending special assessments for seawall repairs and canal dredging.
For a broader search across Palm Beach and West Palm Beach, including Alba West Palm Beach, carry these questions into each comparison. Review shared obligations in the relevant documents rather than carrying over assumptions from a previously viewed property.
A standard home inspection does not adequately assess a seawall. Retain a marine contractor or licensed structural engineer specializing in marine structures, and agree on the inspection scope in advance. The review should address the cap and face, panel alignment, joints, tie-back anchors, soil behind the wall, and estimated remaining service life.
Cracking, spalling, misaligned panels, deteriorated anchors, and soil voids behind the wall warrant specialist evaluation. A tidy lawn or freshly finished cap is no substitute for a structural assessment. Ask the specialist to distinguish observed conditions from areas that remain inaccessible or require further investigation.
The dock review should extend below the waterline to submerged pilings, rather than stop at attractive decking and visible hardware. Schedule this work early enough to obtain repair estimates before the contractual due-diligence period ends. Findings are more useful when paired with a defined scope and property-specific pricing.
Request prior inspection records, repair documentation, storm-damage history, and related insurance claims. Retain the new findings as a baseline for maintenance planning and potential future claims.
A dock and a navigable berth are not the same thing. Establish low-tide depth at the dock or seawall and compare it with the intended vessel's requirements. Water conditions observed during a single viewing are not sufficient evidence of suitability.
Then determine who is responsible for waterway maintenance. Review deeds, easements, association documents, and any applicable special-district materials for dredging duties and cost allocation. Do not presume that a public body or community maintains the waterway simply because several properties use it.
Ask whether dredging assessments have occurred, whether any are pending, and what documentation supports the answers. If future dredging is essential to the purchase decision, obtain property-specific advice on feasibility and authorization before treating deeper water as an achievable improvement. An obligation to contribute to maintenance does not establish that a particular dredging project is approved.
Inventory every seawall, dock, deck, and pier built in, on, or over adjoining waters or wetlands. Request permit records and compare the structures as built with the approved documentation. Investigate discrepancies rather than dismissing them as incidental details.
Review the survey, shoreline boundaries, permits, and any disputes or enforcement matters that could affect waterfront use. Keep existing authorization separate from future ambitions. A current dock does not, by itself, establish permission for an extension, replacement configuration, or different shoreline treatment.
If the purchase depends on reconstruction or a revised shoreline layout, ask the appropriate specialists to identify the approvals applicable to that proposal. Do not assign value to an unconfirmed plan as though it were already authorized.
When comparing a private waterfront property with Forté on Flagler West Palm Beach, distinguish the desired view from any expected rights to use or alter the shoreline. Verify those rights separately for each property.
The insurance review should run alongside the physical and document reviews, not follow them. Give the insurance adviser the intended ownership and occupancy details, marine inspection findings, and available repair and claims history. Ask specifically how the proposed coverage treats the seawall, dock, storm damage, and relevant exclusions or deductibles.
Do not assume Citizens will be available as a fallback. Eligibility is conditional, and replacement cost is distinct from purchase price. Historical thresholds and coastal restrictions are no substitute for a current underwriting determination. Ask whether replacement cost, coastal designations, or permit history affect the property's present eligibility.
Obtain written clarity on the proposed coverage, outstanding conditions, and treatment of waterfront structures. A general indication that a home is insurable is not the same as confirmation that every improvement is protected.
Before the due-diligence deadline, assemble the responsibility schedule, marine findings, repair estimates, permit comparisons, depth information, assessment history, and insurance terms. Have advisers identify unresolved issues and explain their significance before you decide whether to proceed, negotiate, or investigate further.
Preserve that file for the trustee, entity representative, or person overseeing the residence. The strongest waterfront acquisition is not one without maintenance obligations, but one whose obligations are understood, documented, and incorporated into ownership planning.
For a considered approach to your South Florida waterfront search, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationIndividual owners generally bear responsibility, but some communities assign shared maintenance to an association. Confirm the allocation in the property's governing documents.
No. Arrange a dedicated inspection by a marine contractor or licensed structural engineer specializing in marine structures.
The scope should include the cap, face, panels, joints, tie-back anchors, soil behind the wall, and estimated remaining service life. Structural warning signs warrant specialist evaluation.
Yes. Submerged piling conditions should be examined rather than relying only on visible decking and above-water components.
Review deeds, easements, association documents, and applicable special-district materials for maintenance duties and cost allocation. Ask about past and pending dredging assessments.
Low-tide depth at the dock or seawall should be compared with the intended vessel's requirements. Conditions during a single viewing do not establish suitability.
Review surveys, permits, boundaries, and relevant disputes or enforcement matters. Compare existing shoreline structures with their approved documentation.
Existing authorization does not establish approval for a future expansion or different configuration. Obtain property-specific advice before relying on a proposed improvement.
Do not assume automatic commercial or investment classification. Ask the insurance adviser for a current determination based on the proposed ownership, occupancy, property, and policy.
Citizens eligibility is conditional and requires current confirmation. Replacement cost, which differs from purchase price, and applicable coastal considerations should be reviewed with the insurance adviser.