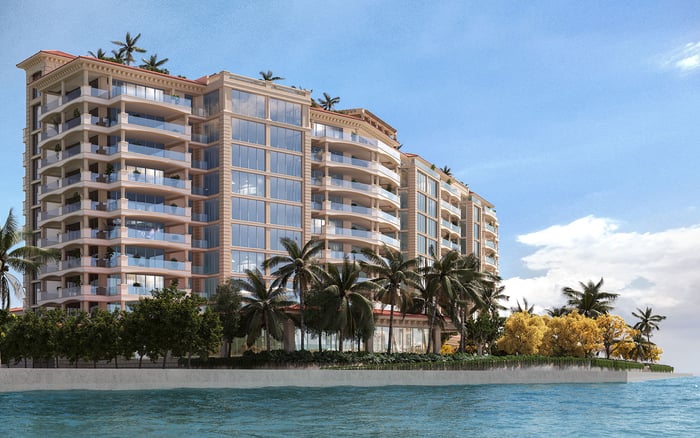
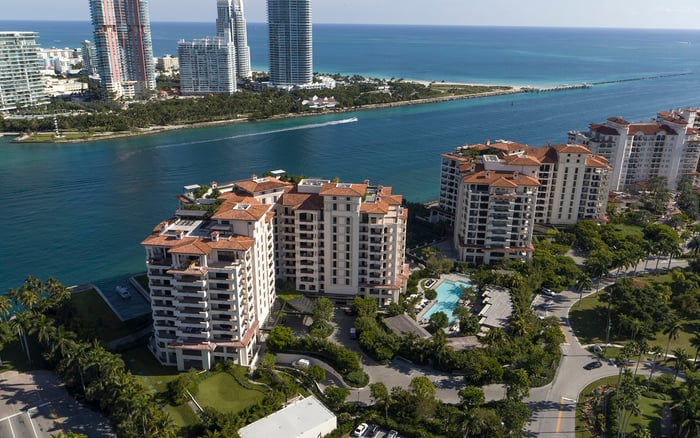
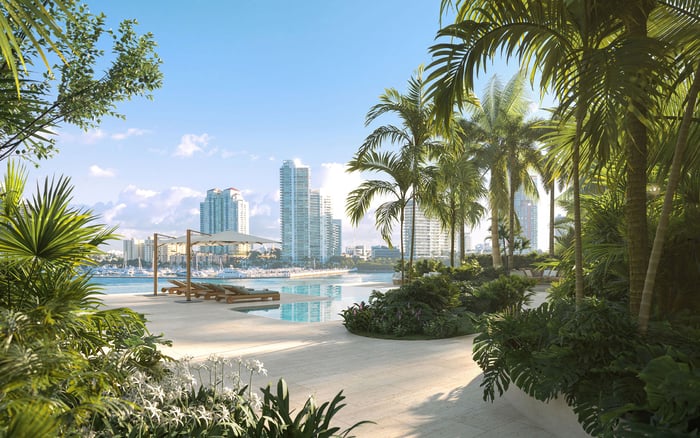
A separately purchased poolside cabana can enhance a Palazzo del Sol resale, but buyers should verify the legal interest, transfer rights, association charges, permitted improvements and insurance before assigning it a premium.
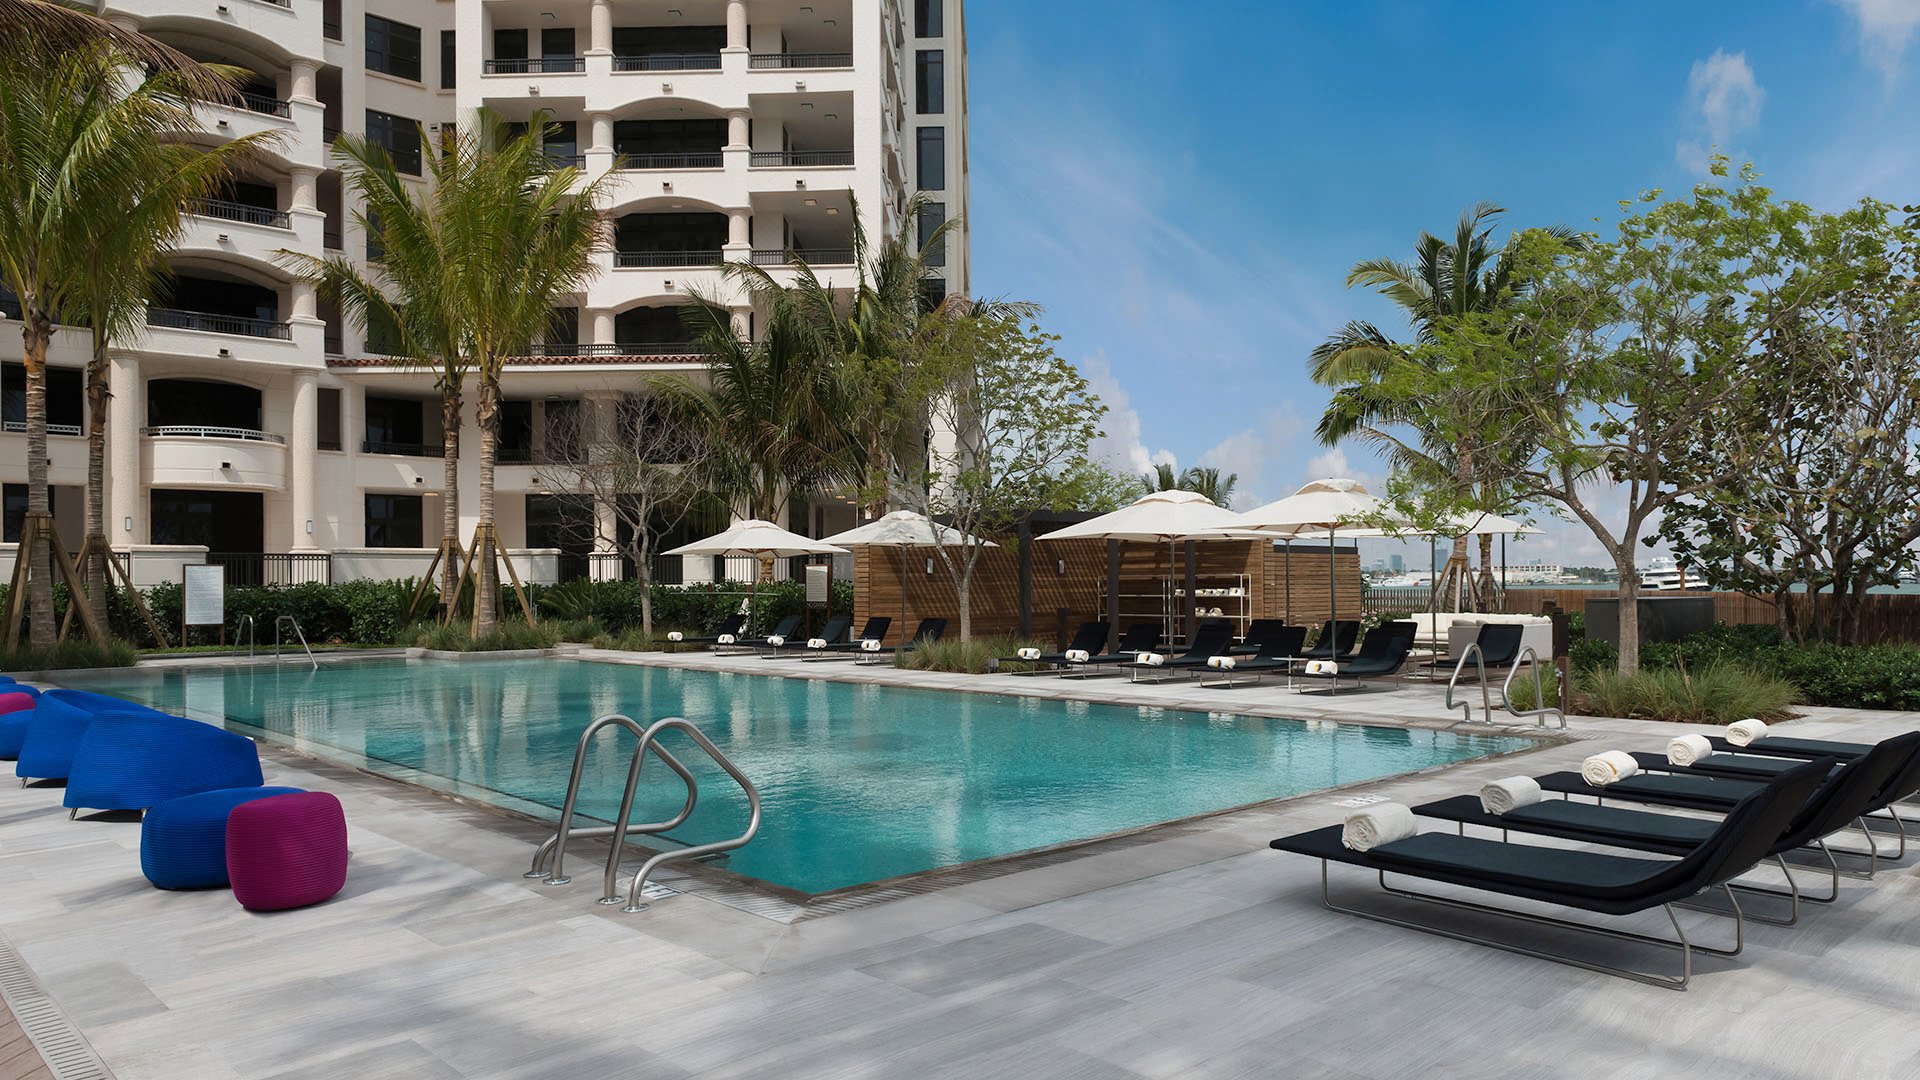
A poolside cabana can make a residence feel more complete: a place to settle between swims, keep essentials close and give the day a quieter rhythm. In a resale at Palazzo del Sol, however, its appeal should be weighed separately from the legal rights being conveyed.
Poolside cabanas were offered as an additional purchase, not an automatically included residence feature. That distinction does not establish the ownership structure of any particular cabana. Separately purchased does not necessarily mean separately deeded. Before assigning a premium, determine precisely what the seller holds and what the buyer will receive.
The governing documents, ownership records and association confirmations should align. A listing description, even one stating that a cabana is included, is no substitute for that review.
Ask your real-estate attorney to review the condominium declaration and applicable ownership documents. The first question is whether the cabana represents a separate interest, an appurtenance to the residence, a limited common element or a right held through a use agreement. These possibilities require investigation; they should not be treated as established characteristics of Palazzo del Sol.
Request the documents that identify the cabana and connect the seller to the interest being offered. Have counsel determine how to describe that interest in the purchase agreement and which documents are needed to transfer it. The contract should not leave the meaning of “cabana included” open to interpretation at closing.
Confirm whether the interest must remain attached to a residence or can transfer independently. A separate original purchase does not, by itself, establish the right to sell it separately later. Any restriction matters both to this acquisition and to a future exit.
Request the declaration, relevant amendments, applicable rules and cabana-specific ownership or use documents through the seller or an authorized representative. Ask for written confirmation of any association approval required for the cabana transfer, distinct from approval of the residence transfer.
Keep the questions specific: What interest is being transferred? Which documents govern it? What approvals remain outstanding? Who will provide the required confirmation before closing?
For a Fisher Island buyer also considering Palazzo della Luna, the discipline is the same: evaluate each property's documents on their own terms. Neither a shared destination nor a similar amenity description establishes identical ownership rights. The cabana under consideration needs its own supporting documentation.
The condominium estoppel certificate is central to confirming association obligations. It identifies the unit and owner and discloses assessments and other amounts owed. The essential follow-up is whether the residence's certificate covers every cabana-related obligation.
If the cabana is administered separately, request a separate written account statement. Ask the association to clarify which accounts and charges are included; do not interpret silence as confirmation that nothing is due. Reconcile the response with the purchase agreement and the amounts being addressed at closing.
Florida condominium law requires issuance of an estoppel certificate within 10 business days after receipt of a written or electronic request from a unit owner or authorized designee. A certificate delivered by hand or electronically generally has a 30-day effective period; one sent by regular mail generally has a 35-day effective period.
Coordinate the request with the anticipated closing date. The certificate also addresses whether association approval of the unit transfer is required and whether it has been obtained. That disclosure does not replace a separate inquiry into cabana-specific approval requirements.
An attractive existing setup is not proof that every component is authorized. Review the rules governing furnishings, appliances, electrical connections, locks, renovations and permanent improvements. Ask which approvals apply to the current arrangement and request the corresponding documentation where applicable.
The estoppel includes specified information about violations identified in association records. Confirm whether any disclosed issue concerns the cabana or its improvements. If it does, establish what remains unresolved and have counsel address responsibility in the transaction documents before closing.
Pair a practical inspection with this records review. Physical condition and permission are different questions: a feature may look well maintained while its authorization remains unconfirmed. Likewise, approval of an existing installation should not be assumed to authorize a buyer's intended changes.
Consider how you expect to use the cabana, then compare that expectation with the governing rules. If particular furnishings or appliances are important to your routine, verify that they are permitted before including them in your valuation. Clarify which existing contents are part of the sale rather than assuming everything shown will remain.
Buyers comparing the experience with The Residences at Six Fisher Island should maintain the distinction between an appealing amenity and a transferable legal interest. This does not mean the projects offer equivalent cabana arrangements. The point is to compare documented rights, not simply the impression created by a poolside setting.
The most useful question is not merely whether a cabana is included, but whether its permitted use matches the lifestyle you intend to purchase.
Review the declaration and association records to establish responsibility for cabana upkeep and any applicable pool-deck or common-area costs. Distinguish the tasks the owner must perform from those handled by the association, and identify the charges associated with each responsibility.
Insurance warrants an equally explicit review. Establish which cabana components and contents fall under association coverage and which require owner coverage. Do not assume that the residence's insurance arrangements extend to everything associated with the cabana. Ask your insurance adviser to reconcile the documented responsibilities with the coverage being arranged.
For a residence used intermittently, clear maintenance responsibilities are particularly useful. Understand the obligations before ownership begins, rather than discovering them when attention or repairs are needed.
Before agreeing to a cabana premium, assemble a closing file that answers five questions: what is owned, whether it can transfer, what is owed, how it may be used and who bears ongoing responsibility. Any unresolved point should remain an open diligence item, not an assumption embedded in the price.
A separately purchased cabana may be a meaningful addition to the residence. Its value to a particular buyer should reflect the rights and obligations actually confirmed, rather than the original purchase history alone. Have your attorney resolve the legal questions and your insurance adviser confirm coverage before treating the package as complete.
For a discreet perspective on South Florida residences and the details that shape ownership, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationCabanas were marketed as available for an additional purchase, rather than as automatically included residence features. A resale buyer should verify what the particular transaction includes.
No. A separate purchase does not establish separate deeded ownership; the declaration and applicable ownership documents must establish the legal interest.
Request the condominium declaration, relevant amendments, applicable rules and documents establishing the seller's cabana interest. Obtain association records through the seller or an authorized representative.
That must be determined from the governing documents and applicable ownership terms. Do not infer independent transfer rights from the fact that it was purchased separately.
Do not assume it does. Confirm coverage explicitly and request a separate written account statement if the cabana is administered separately.
Florida condominium law requires issuance within 10 business days after receipt of a written or electronic request from the unit owner or an authorized designee.
A certificate delivered by hand or electronically generally has a 30-day effective period. One sent by regular mail generally has a 35-day effective period.
Not necessarily. Separately confirm whether the cabana-related interest requires approval and whether that approval has been obtained.
No. Review applicable rules and approval records for furnishings, appliances, electrical connections, locks and alterations, and investigate any disclosed violations involving the cabana.
The declaration, association records and applicable insurance coverage must establish those responsibilities. Verify owner obligations separately from association coverage and upkeep.