For a nonresident purchasing South Florida real estate through a U.S. entity, ownership planning and cross-border funding deserve equal attention. Review reporting requirements, intermediary-bank checks, sanctions exposure, and transaction-specific funding questions before closing.
For a nonresident buying a South Florida residence through a U.S. entity, ownership structure and the path of purchase funds belong in the same plan. Choosing the name that will hold title does not resolve how money will reach the closing account, whose information a bank may examine, or whether a payment can lawfully proceed.
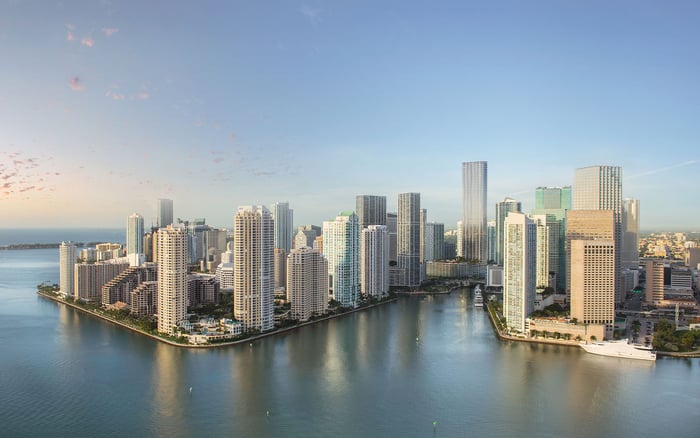
The distinction matters whether the search centers on Brickell and The Residences at 1428 Brickell or elsewhere along the coast. Separate three decisions: the ownership structure, the banking route, and the funding obligations in the transaction documents. None substitutes for the others.
A U.S. entity does not make a cross-border payment purely domestic. Nor does entity ownership guarantee anonymity. A considered acquisition plan makes the ownership clear to the professionals responsible for reviewing it.
Before selecting an LLC or another structure, ask qualified legal and tax advisers to evaluate the arrangement for the particular buyer. There is no universal ownership recommendation, and no assumption that a domestic entity produces a particular tax result or satisfies every applicable qualification requirement.
For the funding discussion, prepare a clear account of the proposed titleholder, its ownership, and the party expected to send the purchase money. Ask the receiving institution and settlement professional what documentation they require and how payment instructions should identify those parties. The goal is accurate information, not a structure designed to obscure the underlying owner.
Residential reporting and payment sanctions are separate issues. A change in a real estate filing requirement does not establish that a bank may process a payment involving blocked interests. Keep both questions on the closing agenda, even when the entity was formed in the United States.
The Residential Real Estate Rule was designed to cover certain non-financed transfers of U.S. residential property to legal entities or trusts, including LLCs-not every residential purchase. Its geographic focus is the property, rather than where the purchasing entity was organized.
A foreign entity acquiring a South Florida residence can therefore fall within the rule's designed scope. Its reporting framework includes information about the acquiring entity and its beneficial owners, another reason not to equate entity ownership with anonymity.
Ask counsel to verify the rule's legal status and any applicable filing obligations for the actual closing date. Do not rely on a reporting conclusion from an earlier transaction or assume that the rule's designed scope establishes a current filing obligation.
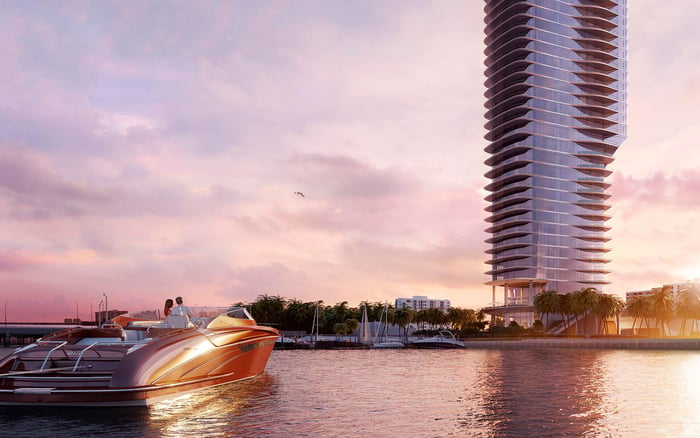
If operative and applicable, the framework generally places filing responsibility on a designated closing or settlement professional, rather than the buyer. For a Miami Beach purchase involving The Perigon Miami Beach, ask counsel to confirm the rule's status and applicability. This is not a project-specific reporting determination.
An international transfer can involve banks beyond the sending and receiving institutions. Intermediary banks can introduce additional compliance reviews. An instruction accepted at the starting point is not assurance that every institution along the route has completed its review.
Compliance reviews address transactor information on automated funds transfers and the completeness of payment-party information in cross-border cover payments. When the law requires it, transactions must be blocked or rejected and the required regulatory reports filed. Accurate originator and beneficiary details therefore matter beyond the two banks most visible to the buyer.
Ask the sending bank to explain the anticipated route and the information it needs. Coordinate that information with the receiving side before initiating payment. If questions arise during processing, seek an explanation through the banking and legal team rather than assuming the issue is merely administrative.
A U.S. LLC does not neutralize sanctions exposure arising from blocked ownership. A wire in which an entity has an interest can constitute blocked property when that entity is 50% or more owned by a person whose property and interests in property are blocked.
That requirement can apply even when a U.S. bank acts only as an intermediary. A transfer between offshore banks is not necessarily outside U.S. sanctions controls if it passes through a U.S. institution and involves a designated party.
For a buyer considering Four Seasons Residences Coconut Grove in Coconut Grove, the practical lesson is the same as for any other acquisition: resolve ownership-related sanctions questions with qualified advisers before relying on the proposed payment route. The domestic entity's name alone does not answer them.
When purchase funds begin in another currency, confirm conversion and delivery arrangements rather than assuming them. Ask the settlement professional which currency the designated account accepts. Ask the bank or conversion provider for the proposed conversion terms, charges, and expected amount delivered. Have the team reconcile that amount with the transaction's funding requirements.
Also ask which party will perform the conversion, when the proposed rate becomes binding, and how any difference between the expected and delivered amount would be addressed. These are transaction-specific questions, not universal rules about escrow accounts or foreign-exchange pricing.
Keep the discussion practical: who sends, who converts, who receives, and who confirms receipt. A quoted exchange rate and an accepted transfer instruction do not replace confirmation from the relevant professionals that the required funding has been received as instructed.
For a West Palm Beach acquisition involving Alba West Palm Beach, begin the funding conversation with the agreement and settlement instructions, not a generic estimate of international wire speed. Ask counsel to identify the applicable deadlines and explain what constitutes timely funding under those documents.
Then ask the banking team what timing assumptions are reasonable for the specific currency and route, allowing for potential compliance questions. No fixed number of business days is a guaranteed transfer time or a universal closing deadline. Ask counsel what options exist if payment is delayed; do not presume that a banking review changes the agreement.
Before authorizing the transfer, bring the ownership information, payment details, conversion arrangements, and funding calendar into one coordinated review. This is general planning guidance, not transaction-specific legal, tax, or banking advice. The objective is a purchase whose financial execution receives the same attention as the residence itself.
Explore South Florida residences with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. Entity ownership does not guarantee anonymity, and the residential reporting framework was designed to include beneficial-owner information.
No. It was designed to cover certain non-financed transfers of U.S. residential property to legal entities or trusts, including LLCs.
Ask counsel to verify the rule's legal status and applicability for the actual closing date. Do not assume that a conclusion from an earlier transaction still applies.
Not necessarily. The rule focuses on the location of the residential property rather than where the acquiring entity was organized.
Filing responsibility generally falls to a designated real estate closing or settlement professional rather than the buyer. Confirm applicability and responsibility with the transaction team.
They can conduct compliance reviews beyond those of the sending and receiving banks. Complete originator and beneficiary information is important to that review.
No. A wire involving an entity can be blocked property when that entity is 50% or more owned by a person whose property and interests in property are blocked.
Yes. Blocking requirements can apply when the payment passes through a U.S. intermediary bank and involves a designated party or blocked interest.
Confirm the receiving account's accepted currency, the proposed conversion terms and charges, and the expected delivered amount. Coordinate these details with the settlement professional and banking team.
There is no universal guaranteed transfer time. Ask the banking team about the specific route and have counsel confirm the agreement's funding deadlines and treatment of delays.