A Zurich-to-North Bay Village move calls for more than a residential purchase. Coordinate Swiss reporting, U.S. banking, ownership decisions, financing documentation, and FIRPTA responsibilities before committing capital.
For a Zurich family office considering North Bay Village, the residential acquisition is the visible part of a broader transition. The more consequential work lies behind it: reconciling residence and tax status, arranging banking, choosing an ownership structure, and assembling a consistent purchase file.
The guiding principle is straightforward: a property closing should not become the deadline for resolving every cross-border question. Treat the family’s residence, the office’s operations, the purchasing entity, and the movement of capital as related but distinct decisions. A home purchase is not evidence that immigration permissions or tax-residency questions have been resolved.
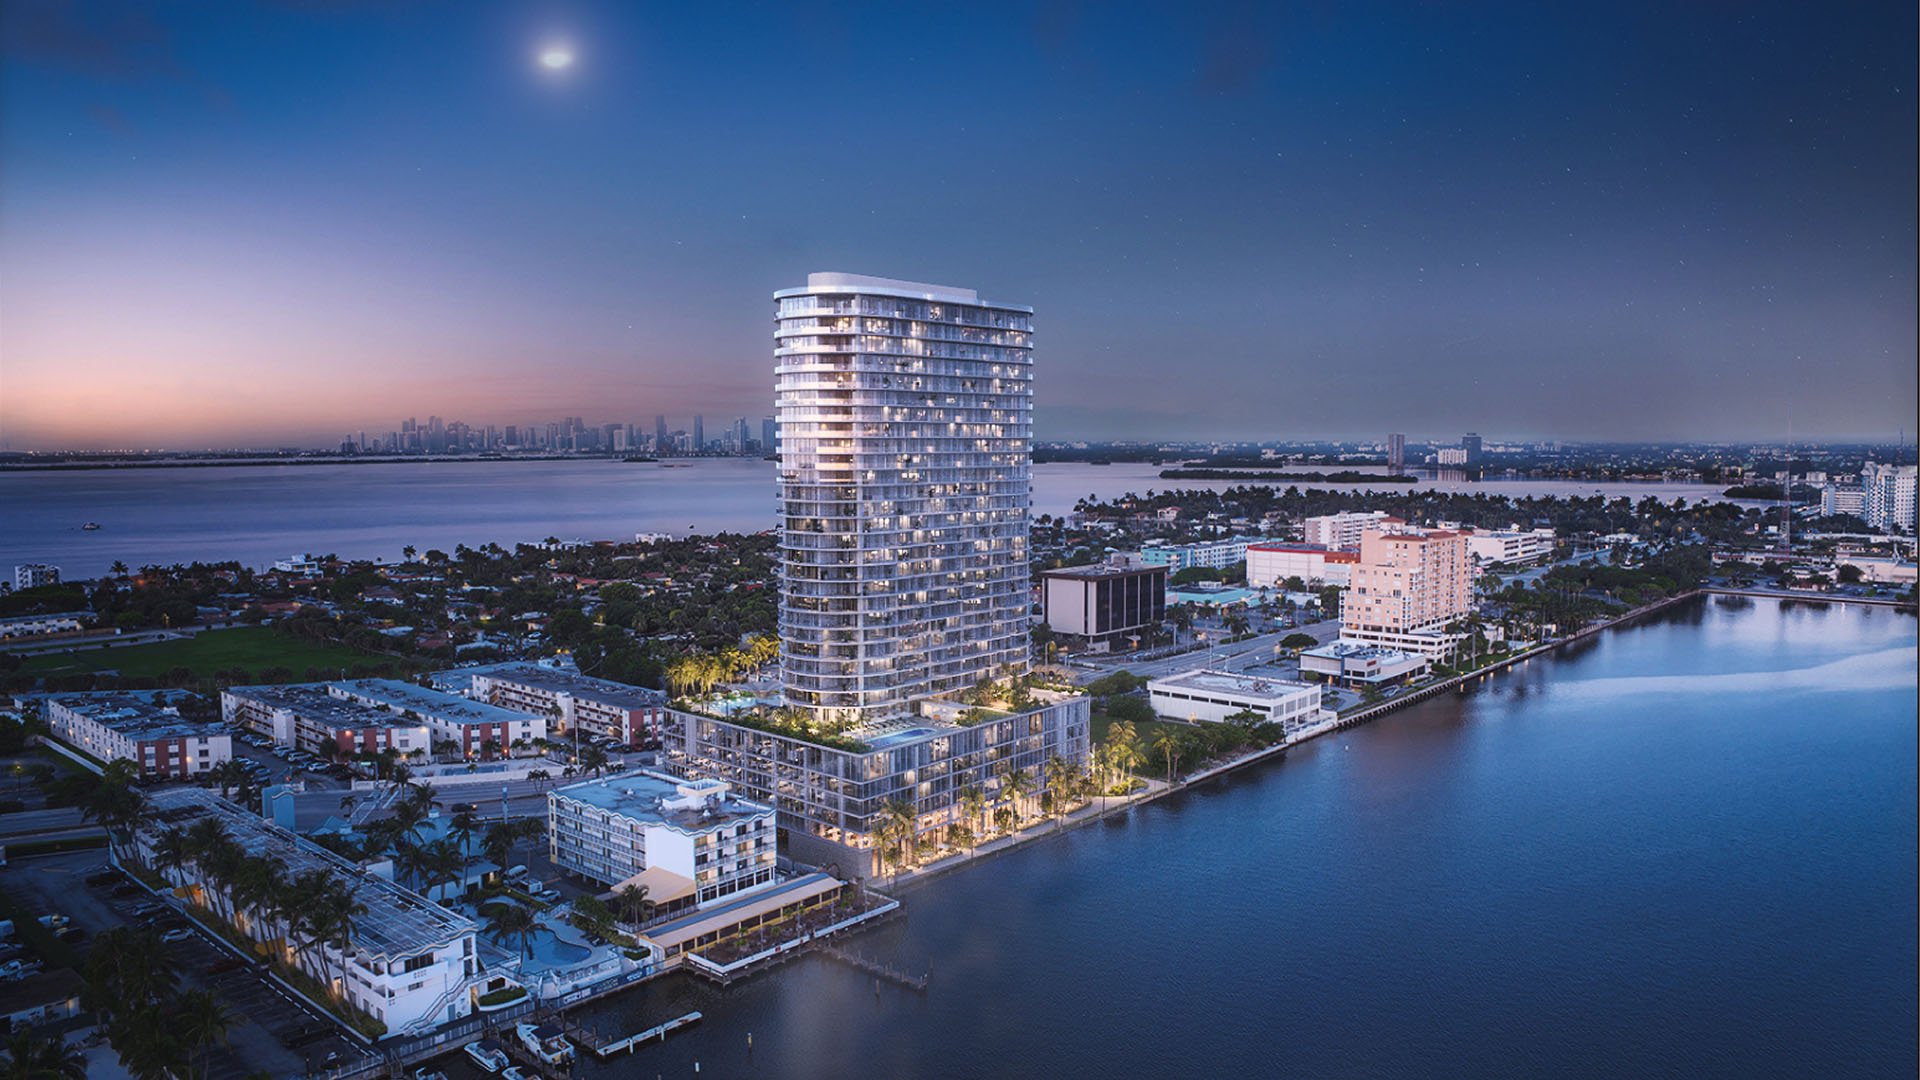
When evaluating Continuum Club & Residences North Bay Village, maintain a residential brief alongside a separate advisory brief. The first concerns how the family wants to live; the second identifies who will own, fund, and document the acquisition.
Switzerland has implemented FATCA and CRS, with registration, reporting, and due-diligence obligations relevant to Swiss financial institutions and family-office structures. Relocation therefore calls for more than a change-of-address instruction.
Review Swiss bank self-certifications against each account holder’s actual residence and tax status. Distinguish a correspondence address from effective residence: a mailing address is not necessarily where someone resides with the intention of permanent stay. Ask each institution how its self-certification guidance applies to the account holder’s circumstances.
Prepare a shared factual record for Swiss and U.S. advisers, covering the intended move, anticipated property use, relevant account holders, and proposed purchaser. This is a coordination recommendation, not a substitute for either jurisdiction’s legal tests.
Swiss departure treatment, U.S. residency calculations, treaty outcomes, immigration permissions, and family-office entity classification warrant separate professional advice. Do not let a preliminary conclusion in one area become an assumed answer in another. Florida’s lack of individual state income tax, for example, does not eliminate federal FIRPTA obligations on U.S. real-property sales.
Treat U.S. banking as a separate workstream, not an extension of the property search. Before scheduling funds around an assumed approval date, ask the prospective institution to confirm its account-opening requirements for the actual applicant, whether an individual or entity.
Request written clarification of identity evidence, address evidence, tax-status documentation, entity information where relevant, and the institution’s expectations for explaining incoming funds. These are questions for the bank, not a universal checklist. An EIN, ownership chart, certified document, or CRS form should not be presented as mandatory at every U.S. institution.
Have the family office designate who will answer follow-up questions and maintain the current document set. Discuss the proposed transfer route and timing with the relevant banks and closing professionals. Do not assume that account opening and transaction readiness are the same milestone.
For a purchase under consideration at Shoma Bay North Bay Village, align the banking plan with the proposed purchaser and contractual payment schedule. The objective is consistency across the funding explanation, ownership decision, and closing file.
U.S. LLCs, sometimes combined with trusts, are among the ownership arrangements considered by foreign buyers. They require coordinated analysis of liability, estate planning, and eventual FIRPTA treatment. An LLC does not guarantee anonymity and should not be assumed to eliminate withholding obligations on a later disposition.
Before committing to an ownership arrangement, ask advisers to examine the residence’s intended use, the family’s succession objectives, and the proposed financing together. Keep the acquisition vehicle distinct from the question of how the family office itself will be classified or operated.
Some Miami foreign-national mortgage programs do not require U.S. credit history, instead considering foreign income and asset documentation. Indicative down payments of approximately 30-40% appear in this market, alongside source-of-funds verification. These are not universal lender terms or a commitment to lend.
Obtain the lender’s requirements for the proposed borrower and property. Ask what evidence of foreign income and assets it will accept, then reconcile those requirements with the bank and purchase files. Even substantial liquidity does not resolve every documentation question.
A typical foreign-buyer purchase file includes a signed contract, passport, proof of address, and formation documents when an entity is purchasing. Treat this as a starting point, not an exhaustive statement of bank, lender, condominium, or closing requirements.
Assemble the file progressively: identity and address evidence during preparation, the signed contract once executed, and applicable entity documents for the selected purchaser. Ask the closing team to identify transaction-specific additions and resolve inconsistent names or addresses before they become last-minute questions.
If the family’s search also extends to Miami Beach, a comparison with The Perigon Miami Beach calls for the same documentary discipline. A different residential preference is no reason to assume identical condominium approvals, local requirements, recording charges, or documentary stamp calculations. Have those matters confirmed for the actual acquisition.
FIRPTA concerns dispositions by foreign sellers. It does not impose a tax merely because a foreign buyer acquires U.S. real estate. Nevertheless, the buyer is the withholding agent and can face liability when required withholding is not collected and remitted.
Confirm the seller’s foreign-person status and any applicable exception before closing. Default withholding is 15% of the gross sale price-not the seller’s gain-unless an exception or adjustment applies.
The residence-related thresholds require care:
A qualifying buyer-residence purchase of $300,000 or less can be exempt from withholding.
A qualifying buyer-residence purchase above $300,000 and up to $1 million generally carries 10% withholding.
Above $1 million, or where the applicable residence-use conditions are not met, the default is generally 15%, unless another exception or withholding certificate applies.
Price alone does not establish eligibility for residence-based relief. Have the closing and tax advisers assess the conditions rather than rely on the family’s informal description of the property as a home.
Withholding is generally reported on IRS Form 8288 and remitted within 20 days after closing, subject to procedural exceptions. An IRS withholding certificate may reduce or eliminate withholding where it exceeds anticipated seller tax liability. Withholding is a payment toward that liability, not the final calculation; the seller files a return to determine actual tax and any refund.
Before closing, bring the advisory decisions together: residence reporting, ownership, bank readiness, lender conditions, purchase documents, and seller withholding status. Assign responsibility for each unresolved item. This is an acquisition coordination framework, not individualized tax or legal advice.
For a discreet residential search shaped around your family’s priorities, explore North Bay Village and South Florida with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationCoordinate residence and tax-status advice, Swiss account reporting, ownership, banking, financing, and purchase documentation. Keep the residential acquisition distinct from decisions about relocating family-office operations.
Yes. Review them against each account holder’s actual residence and tax status rather than treating a new mailing address as sufficient.
Do not assume a universal checklist. Obtain requirements from the chosen institution for the actual individual or entity applying.
Some Miami programs consider foreign income and asset documentation without requiring U.S. credit history. Eligibility and acceptable evidence remain lender-specific.
Approximately 30–40% is an indicative range described for some foreign-national financing. It is not a universal requirement or a financing commitment.
A typical file includes a signed contract, passport, proof of address, and formation documents when an entity purchases. Confirm additional requirements with the relevant transaction professionals.
No such outcome should be assumed. LLC and trust arrangements require coordinated advice on liability, estate planning, and eventual FIRPTA treatment.
The buyer is the withholding agent when required withholding applies to a foreign seller’s disposition. Failure to collect and remit it can expose the buyer to liability.
The default is 15% of gross sale price, but qualifying residence purchases and other exceptions or withholding certificates can change the result. Price alone does not establish eligibility for residence-based relief.
It is generally reported on IRS Form 8288 and remitted within 20 days after closing, subject to procedural exceptions. Withholding is a payment toward the seller’s potential tax liability, not the final tax calculation.