A discreet move from Washington, D.C. to Miami’s Edgewater calls for more than a moving schedule. Coordinate staff agreements, federal payroll obligations, residence access and vendor insurance before arrival, then review the household’s operating arrangements after the first month.
For a household leaving Washington, D.C. for Miami’s Edgewater, a successful move is measured less by the arrival of furniture than by the continuity of daily life. Familiar staff, accurate payroll and dependable vendors help the new residence feel settled without requiring the owner to manage every detail.
Organize the transition around three coordinated workstreams: people, payroll and property operations. Assign one accountable coordinator-a household manager or designated adviser-and maintain a shared schedule with clearly limited access. A 30-45-day preparation window is a useful planning guide, not a statutory deadline.
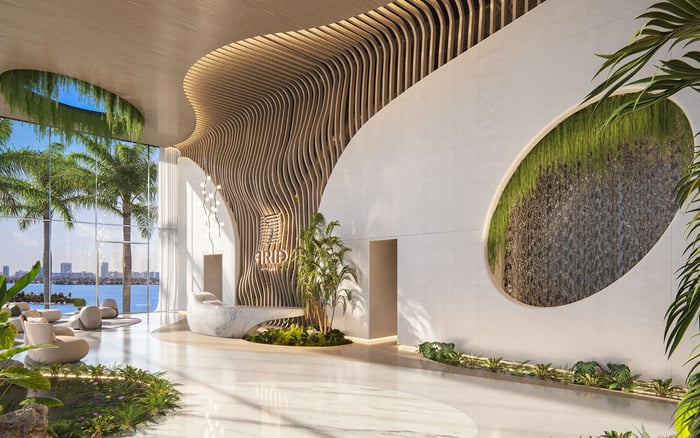
When evaluating Aria Reserve Miami, bring operational questions into the purchase conversation. Ask how household employees, deliveries and outside contractors would be accommodated. Do not assume arrangements at the Washington residence will transfer unchanged. Confirm the answers for the particular residence and intended occupancy date.
Start with a confidential roster identifying who will relocate, who will remain in Washington and which services may need local replacement. For each person, document duties, reporting relationships, work location, anticipated schedule and proposed transition date. Separate agreed arrangements from decisions awaiting approval.
A written transition letter can clarify compensation, agreed moving assistance, temporary accommodation, travel expectations and changes in responsibilities. These letters are recommended planning tools, not universal legal requirements. Have employment advisers review the arrangements before promises become commitments, particularly if the household will continue operating in both locations.
Do not use the relocation to relabel an employee as an independent contractor. Household-worker classification depends on control over both what work is performed and how it is performed. A change of residence alone does not establish contractor status.
Keep staff decisions separate from vendor procurement. A directly managed household employee and a business engaged for a defined service should not automatically share a payment workflow. Review the actual working relationship before deciding how either will be paid.
The central federal threshold for 2026 is $3,000 in cash wages paid to one household employee during the year. At that level, Social Security and Medicare taxes generally apply, subject to applicable exceptions. The move is not a reason to discard earlier wage records or restart annual tracking.
The standard combined Social Security and Medicare rate is 7.65% each for employer and employee. Social Security accounts for 6.2% per party, with a 2026 taxable wage ceiling of $184,500 per employee. Standard Medicare tax is 1.45% per party, without a wage ceiling. These standard rates are not a complete calculation of every possible payroll obligation.
Federal income-tax withholding is a separate decision. Household employers generally do not have to withhold it unless the employee requests withholding and the employer agrees. Record the decision explicitly so the employee’s expectations and payroll instructions remain aligned.
Federal unemployment tax has a different wage trigger: total household cash wages of $1,000 in a calendar quarter. Have the payroll provider confirm how that test applies to the household’s wage history. Its statutory rate is 6% on the first $7,000 of annual wages per employee, before applicable unemployment-tax credits. This employer-paid tax must not be deducted from employee wages.
Before the first post-move payment, have the payroll provider reconcile year-to-date wages, employee details, deductions and employer responsibilities. Applicable household employment taxes generally belong on Schedule H with the employer’s federal income-tax return. Form W-2 is generally required when wages are subject to Social Security or Medicare taxes, or when federal income tax is withheld.
Federal payroll is only one part of the transition. Obtain specific advice on Florida unemployment, workers’ compensation, wage obligations and any continuing Washington, D.C. responsibilities. The federal thresholds above do not establish those requirements, and the move alone does not resolve which obligations apply.
Give advisers a factual account of where each employee will work, whether the Washington household will remain active and how travel will be handled. Keep employment terms, payroll settings and actual work patterns aligned.
For a household considering EDITION Edgewater, keep residence planning distinct from employment compliance. Confirm any building services or access arrangements independently; do not assume they replace the owner’s responsibilities toward privately employed staff.
Before authorizing service visits, request the residence’s current procedures for contractor registration, deliveries, work scheduling and access credentials. Confirm who can approve entry and who should receive notice when work is completed. Engaging a familiar vendor does not, by itself, give that vendor permission to enter.
At Villa Miami, as with any prospective residence, include these questions in operational due diligence without presuming particular policies or services. Ask whether a household representative can coordinate visits and what documentation management expects.
A tiered access plan is a practical safeguard. Recurring staff may need different permissions from a technician making a single visit. Consider time-limited access, an approved contact list and a record of issued keys or credentials. Keep sensitive household information separate from routine vendor scheduling, and remove access when an engagement ends.
Create a vendor master file documenting the service scope, responsible contact, pricing approval, payment instructions and insurance documentation. Identify who may authorize additional work. This can reduce confusion when several providers arrive during the same move-in period.
Insurance should reflect the task and exposure, not an assumed residential minimum. Obtain advice suited to the service and confirm the property’s applicable requirements before authorizing work.
Where driving is part of the service, ask an insurance adviser whether owned, non-owned and hired vehicle exposures are appropriately addressed. Plan to monitor continuing coverage rather than simply collecting a certificate at onboarding.
When considering The Cove Residences Edgewater, obtain the applicable property requirements separately from the household’s own insurance advice. Building approval and household risk review answer different questions.
Around 30 days after arrival, conduct a suggested operational review. Reconcile payroll, confirm staff duties, examine vendor invoices and check whether access permissions still match current needs. Ask staff privately where handoffs remain unclear.
The objective is a household that runs quietly because responsibilities are explicit, not because the owner continually intervenes. Preserve the agreed operating arrangements in a secure file and update them as the residence becomes fully established.
For a considered approach to your next Edgewater residence, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationA 30–45-day preparation window is a useful planning suggestion. It is not a statutory deadline.
No. Classification depends on control over what work is performed and how it is performed, not on the residence changing.
These taxes generally apply when one household employee receives $3,000 or more in cash wages during 2026, subject to applicable exceptions.
The standard combined Social Security and Medicare rate is 7.65% each for employer and employee. Social Security has a 2026 wage ceiling of $184,500, while standard Medicare has no wage ceiling.
Generally, withholding is not required unless the employee requests it and the employer agrees. Document the arrangement clearly.
Review the $1,000 calendar-quarter household cash-wage trigger with the payroll provider against the household’s wage history. FUTA is employer-paid and must not be deducted from employee wages.
Applicable household employment taxes are generally reported on Schedule H with the employer’s federal income-tax return. Form W-2 is generally required when wages are subject to Social Security or Medicare taxes, or federal income tax is withheld.
Obtain advice suited to the service and confirm the property’s applicable requirements. Insurance review should reflect the work and exposure rather than an assumed residential minimum.
A practical file includes the service scope, responsible contact, pricing approval, payment instructions and insurance documentation. Access permissions and authority to approve extra work should also be clear.
Reconcile payroll, confirm staff duties, review vendor invoices and check access permissions. A review around 30 days after arrival is a suggested operating practice, not a statutory deadline.