A Beverly Hills departure calls for more than a change of address. For a Pompano Beach purchase, permanent-residence status, assessment resets and filing deadlines shape a disciplined property-tax strategy, both at acquisition and at a future Florida move.
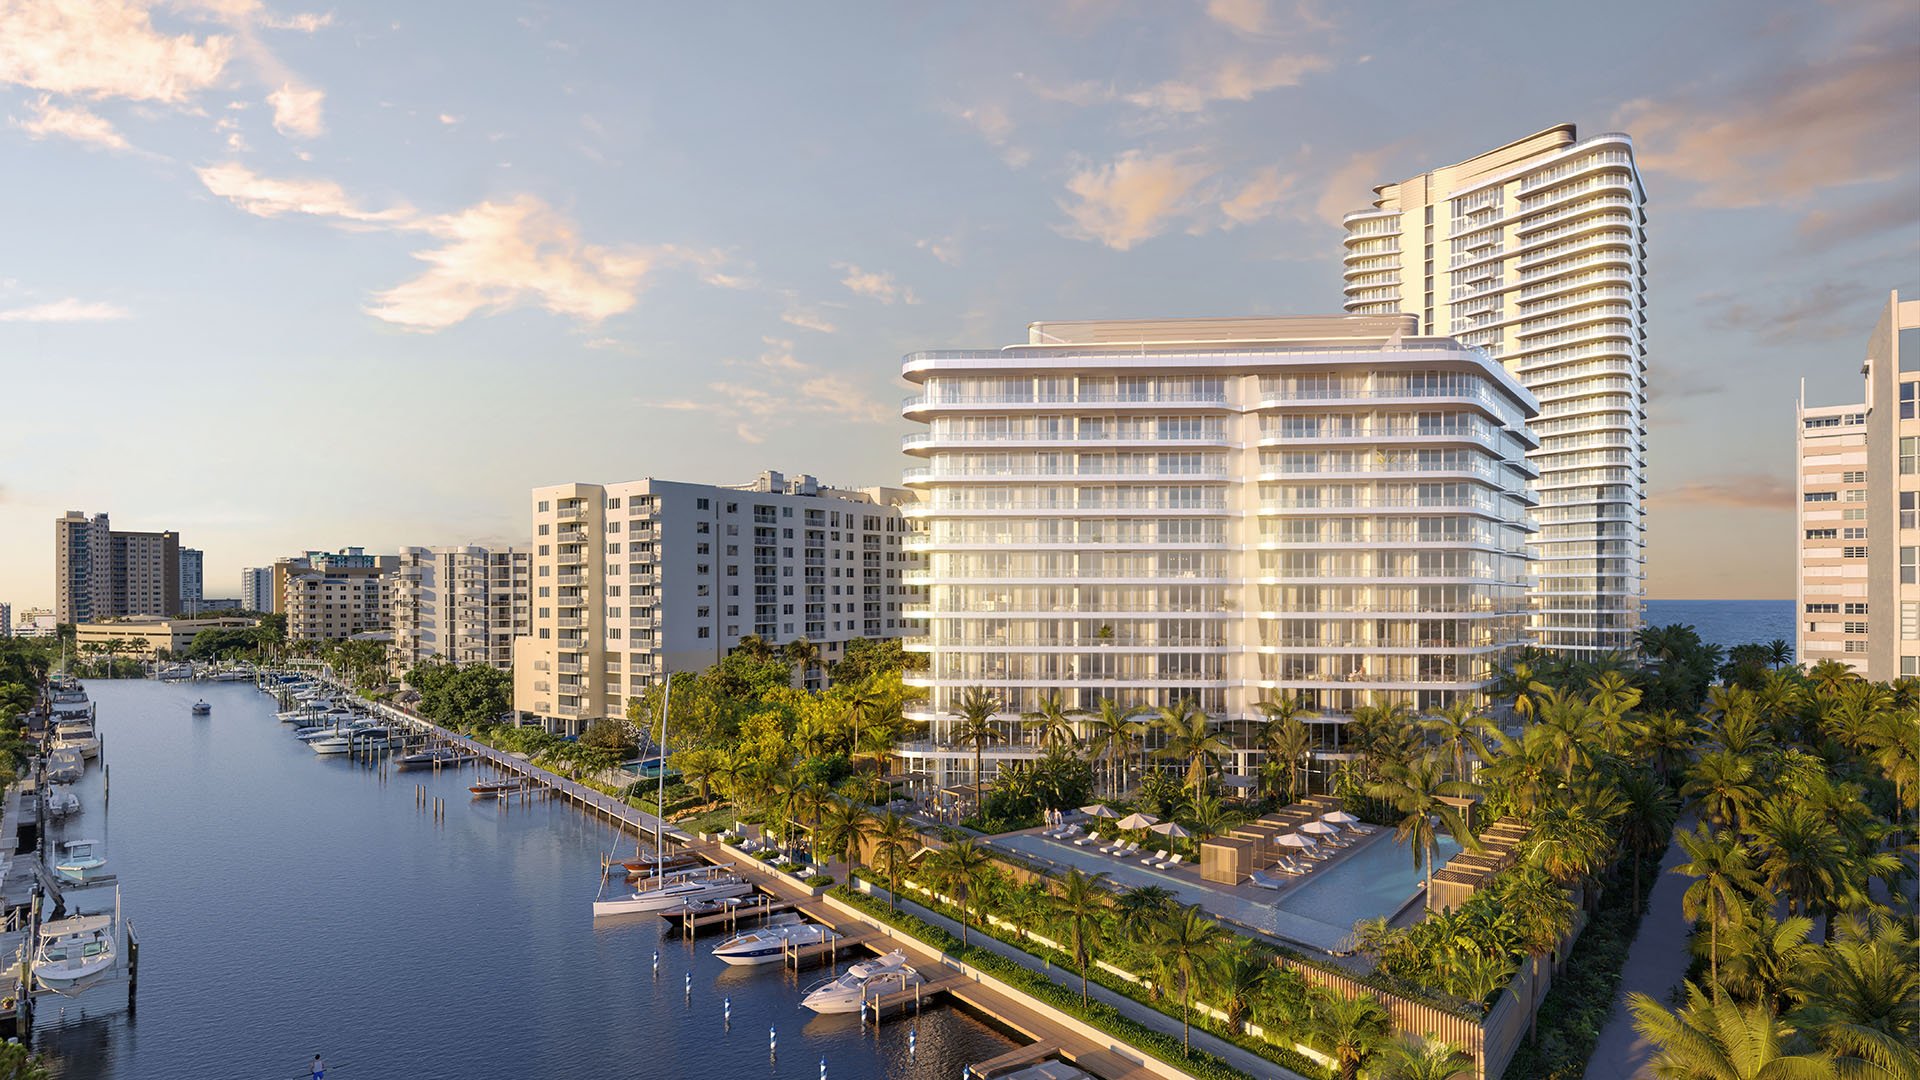
Leaving Beverly Hills for Pompano Beach can begin as a lifestyle decision. The property-tax strategy, however, starts with a more concrete question: will the Florida residence become your permanent home or remain a second residence? That distinction determines which assessment protections may apply and how to organize the acquisition calendar.
A Florida purchase does not, by itself, establish lower annual carrying costs. Without a property-specific comparison, there is no sound basis for declaring Pompano Beach cheaper than Beverly Hills. The more useful exercise is to distinguish the acquisition-year tax position from the assessment basis after purchase and the protections available during ownership.
For a buyer considering Armani Casa Residences Pompano Beach, the residence brief should follow two parallel tracks: the home that suits the household and the ownership assumptions that support its tax budget. Neither a project name nor a seller's historical bill establishes the buyer's future liability.
A qualifying owner must make the property a permanent residence and apply for homestead exemption. Eligibility is determined as of January 1, with a standard application deadline of March 1 for that tax year. In Broward, the priority is to coordinate ownership, permanent-residence eligibility and the exemption application-not treat them as interchangeable milestones.
A buyer acquiring the residence after January 1 generally cannot establish their own homestead exemption there for that tax year. Filing before March 1 does not overcome the January 1 eligibility requirement. Nor is closing before the year changes sufficient on its own: the owner must satisfy the permanent-residence conditions.
The closing calendar is therefore a budgeting input, not simply a transaction preference. Before committing to a date, confirm the expected exemption year for your circumstances. Keep the purchase-year position separate from the first year in which your own homestead exemption is expected to apply.
For an established Florida homestead, Save Our Homes generally limits annual assessed-value increases to the lesser of 3% or the applicable Consumer Price Index change. That protection applies to assessed value. It does not promise that the total property-tax bill will rise by no more than the same percentage.
The accumulated benefit is the difference between the property's just value and its lower Save Our Homes assessed value. It is neither a cash balance nor a dollar-for-dollar tax credit. Keeping those concepts distinct prevents an assessment benefit from being mistaken for an equivalent reduction in annual expenses.
For someone arriving from California without a qualifying prior Florida homestead, there is no Florida Save Our Homes benefit to transfer. Portability does not import a California assessment basis. The starting assumption should therefore be no incoming portability benefit unless a qualifying Florida history has been established.
If the Pompano Beach residence will not be the owner's permanent home, a different framework applies. Eligible nonhomestead properties, including second homes and investment residences, receive a 10% annual assessment-growth limitation rather than the Save Our Homes cap. The county applies that limitation automatically, without a separate application.
Two qualifications matter. First, the 10% limitation applies to non-school assessed values, not the School Board portion of the assessment. Second, it limits assessment growth, not growth in the total tax bill. It is not a ceiling on the household's annual property-tax expense.
When evaluating Ocean 580 Pompano Beach as a second residence, request a tax analysis that distinguishes school from non-school assessment treatment. The purpose is not to assign a building-wide tax advantage, but to understand the specific residence under the intended ownership and use.
For nonhomestead residential property, a qualifying change of ownership triggers assessment at just value on January 1 of the following year. After that reset, subsequent eligible annual increases are subject to the 10% limitation. The seller's accumulated protection does not become the buyer's continuing assessment base.
This distinction deserves its own line in an acquisition review. A historical bill describes the seller's position; it is not a forecast for the new owner. Request a property-specific post-purchase assessment and tax estimate rather than projecting the seller's bill across the intended holding period.
A comparison involving The Ritz-Carlton Residences® Pompano Beach calls for the same discipline. Organize the analysis into the acquisition year, the following January 1 assessment position and subsequent eligible assessment growth. That structure is more useful than a single annual tax figure detached from its assumptions.
A Pompano Beach homestead may become the starting point for a future move within Florida. Eligible owners can transfer up to $500,000 of accumulated Save Our Homes assessment benefit to another Florida homestead. That is a maximum potential transfer, not an automatic entitlement to the full amount.
Eligibility generally requires a homestead exemption on the previous Florida property in one of the three tax years preceding the new homestead exemption. Neither homestead nor portability transfers automatically. Owners must apply for the replacement homestead and separately request portability, with March 1 as the standard portability filing deadline.
Before a future move, use the current homestead's just value and Save Our Homes assessed value to estimate the potentially transferable benefit. Confirm eligibility and the applicable amount before relying on that benefit in the replacement residence's budget.
The assessment rules do not identify an optimal holding period or best resale month. They support a more precise approach: coordinate the next residence's eligibility and filing calendar while presenting the current home's tax history accurately.
A later qualifying nonhomestead sale likewise resets the assessment for the next owner. Your protected assessment should therefore not be marketed as the purchaser's expected ongoing tax position. Nor is there a sound basis for predicting a particular buyer discount from that reset.
The strongest residence strategy keeps three questions separate: what you owe during ownership, what benefit may follow you to another Florida homestead and what a future buyer must budget independently. Choose the home for its fit, then align the tax calendar with that choice.
Explore a considered Pompano Beach residence strategy with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. A reliable comparison requires property-specific tax estimates; the move alone does not establish lower annual carrying costs.
A qualifying owner must make the property a permanent residence and meet eligibility requirements as of January 1. The owner must also apply for the exemption.
The standard deadline is March 1 of the tax year for which the exemption is sought.
Generally not for that residence. A March 1 application does not override the January 1 eligibility requirement.
For an established Florida homestead, annual assessed-value increases are generally limited to the lesser of 3% or the applicable Consumer Price Index change. This is not a cap on the entire tax bill.
No. A buyer without a qualifying prior Florida homestead has no Florida Save Our Homes benefit to transfer.
Eligible nonhomestead properties receive an automatic 10% annual assessment-growth limitation on non-school assessed values. It does not cover the School Board assessment or cap the total tax bill.
The property is assessed at just value on January 1 of the following year. Subsequent eligible annual increases are subject to the 10% limitation, rather than continuing from the seller's protected base.
Eligible owners can transfer up to $500,000 of assessment benefit, not a tax credit. Eligibility generally requires a prior Florida homestead exemption in one of the preceding three tax years, with separate homestead and portability applications.
No optimal resale month or holding period follows from these rules. They support coordinating future homestead and portability deadlines and explaining the next buyer's assessment reset accurately.