At Viceroy Brickell, ownership due diligence should extend beyond the residence to the association’s professional relationships. A disciplined review distinguishes branding from contractual obligations, financial statements from audits, and private-unit services from association management.
For a luxury condominium buyer, the residence is only part of the acquisition. Ownership also means participating in an association whose decisions shape service, spending, and the stewardship of shared property. At Viceroy Brickell, the relationships among legal counsel, the accounting professional, and the association-wide manager deserve deliberate review.
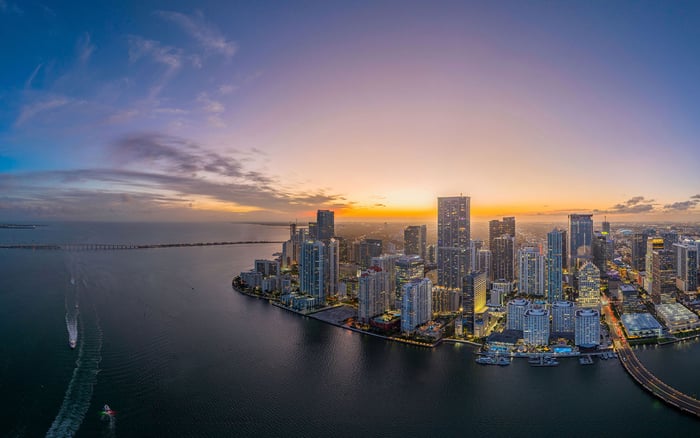
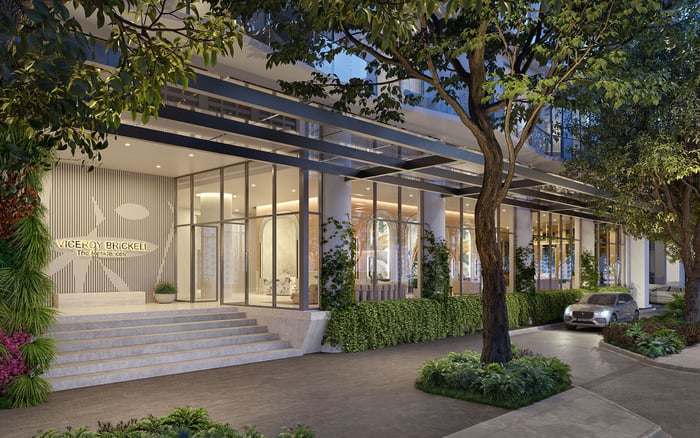
Viceroy Brickell - The Residences is a branded condominium at 77 SE 5th Street in Miami’s Brickell Financial District. Related Group and GTIS Partners are the developers, collaborating with Viceroy. Sales launched in April 2024 for the 45-story, 420-unit tower just west of Brickell Avenue.
Those details establish the project’s identity, not its governance terms. Reviewing professional relationships is due diligence-not an allegation of conflicts, deficient audits, reserve underfunding, or improper management. Buyers should confirm appointments, authority, and contractual obligations rather than infer them from the development team or brand.
A hospitality name provides a recognizable identity. It does not, by itself, establish who employs staff, approves expenditures, appoints professionals, or pays for particular services. The answers belong in the governing documents and applicable agreements.
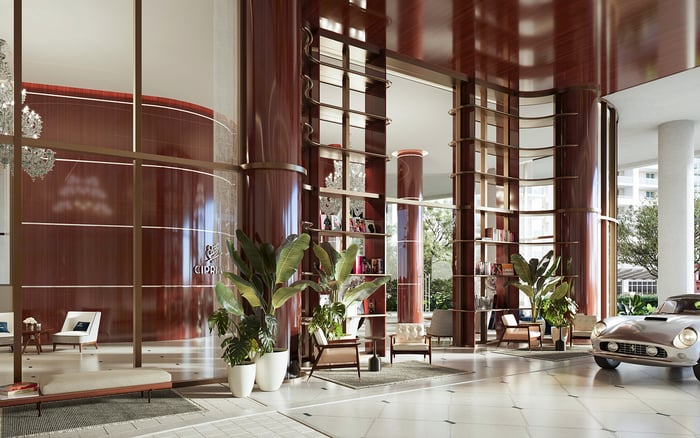
For buyers also considering Cipriani Residences Brickell, a useful comparison begins with consistent questions, not an assumption that branded buildings share an ownership model. Apply those questions to each property’s documents: which entity promises a service, which entity funds it, and who can change the arrangement?
At Viceroy Brickell, request available management and branding agreements for review with independent counsel. Examine scope, fees, affiliations, renewal rights, and termination provisions. Do not presume lengthy commitments, penalties, brand-consent requirements, or developer-friendly indemnities without reading the actual language. Equally, do not assume the association can replace a provider without conditions. The agreement, not the name above the entrance, should settle the question.
The first legal question is straightforward: who is retained to represent the association, and for what work? Confirm the firm’s identity, the scope of its appointment, and who is authorized to give instructions. A buyer’s attorney should separately identify matters requiring advice specific to the buyer.
Where information is available, ask about other relevant professional relationships and how potential conflicts are addressed. A prior or concurrent relationship warrants examination in context; it does not automatically establish improper conduct. The objective is to determine whether the association’s legal interests and decision-making channels are clearly defined.
Access requires care. A prospective purchaser should not assume an automatic entitlement to privileged communications or every engagement letter. Independent counsel can distinguish required transaction disclosures from additional information that may be requested or appropriately summarized. The review should clarify representation without treating confidentiality itself as a warning sign.
Begin with the annual budget and annual financial statement, then determine what professional accounting work has actually been performed. An annual financial statement is not necessarily an audit. Before evaluating an “auditor relationship,” establish whether an audit exists, who performed it, and which period and entity it covers.
Ask for a clear explanation of the accounting professional’s role, including any relevant affiliations and the engagement’s scope where available. Read the financial documents for the questions they can answer: what is budgeted, what was spent, and how association obligations are presented. Seek explanations for material differences rather than treating every variance as evidence of a problem.
Keep financial and physical diligence distinct. An audit does not replace an engineering inspection or a Structural Integrity Reserve Study, commonly called a SIRS. Nor does a budget alone prove that future capital needs are fully addressed. Review applicable engineering and reserve documents alongside the financial material, without assuming Viceroy Brickell has a deficiency.
For an owner who travels frequently, management can be especially important. Yet managing an individual residence and managing the condominium association are different assignments. A business offering services for privately owned units at Viceroy Brickell should not be treated as the confirmed association-wide manager.
Identify the association’s contracted management entity and ask what it is authorized to do. Examine the available agreement for staffing responsibilities, spending authority, procurement procedures, fees, and the division of duties between the manager and board. Ask how performance is evaluated and how owners communicate unresolved concerns.
The same questions can guide a separate review of St. Regis® Residences Brickell without implying that its arrangements match Viceroy’s. For either purchase, tie service expectations to written responsibilities rather than assumptions about what a branded address includes.
For a Florida condominium resale, the seller must provide current required condominium documents at the seller’s expense. These include the declaration of condominium, association articles of incorporation, bylaws, and rules, together with the annual financial statement and annual budget.
Additional disclosures depend on the circumstances. A developer turnover inspection report is among the applicable disclosures for associations whose turnover occurred after July 1, 2023. For buildings subject to milestone-inspection requirements, the applicable inspector-prepared summary is included. SIRS disclosure requirements also address situations in which a study has not been completed.
Do not assume owner turnover has occurred at Viceroy Brickell. Confirm its status and ask counsel which documents apply to the transaction. Resale disclosure requirements should not be applied indiscriminately to a developer sale. In either case, distinguish the mandatory disclosure package from additional contractual and professional information sought for a more complete assessment.
A useful ownership review ends with a clear picture of who advises, who records and examines the finances, who operates the property, and who has authority to approve change. Ask your advisers to identify unanswered questions and explain their practical significance before you commit.
The strongest conclusion is not that every professional must be replaced or that continuity is inherently preferable. It is that responsibilities, costs, affiliations, and available remedies should be understandable. Confirming these points can support confidence in the purchase without turning ordinary diligence into suspicion.
At Viceroy Brickell, the association’s actual documents should determine the assessment. Brand identity and development history provide context; neither substitutes for understanding the obligations that accompany ownership.
For a considered approach to your next South Florida residence, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationViceroy Brickell – The Residences is at 77 SE 5th Street, Miami, FL 33131, in the Brickell Financial District.
Related Group and GTIS Partners are the developers, collaborating with hospitality brand Viceroy.
No. Governing documents and applicable agreements must be reviewed to establish service responsibilities, costs, and contractual rights.
No. The review is a due-diligence exercise, not a finding of conflicts, deficient audits, reserve underfunding, or improper management.
Confirm the firm’s identity, its client and scope of work, and who may direct it. Ask about relevant relationships and how potential conflicts are addressed where information is available.
No. Buyers should establish what accounting work was performed, by whom, and for which period and entity.
No. Financial work and physical-condition assessments serve different purposes and should be reviewed together when applicable.
No. Services for individually owned residences do not establish which company manages the condominium association.
Start with the declaration, articles of incorporation, bylaws, rules, annual financial statement, and annual budget. Additional inspection and reserve disclosures depend on applicable requirements.
Do not assume automatic access to every engagement letter or privileged communication. Independent counsel can distinguish required disclosures from additional information that may appropriately be requested.