
A foreign inheritance can carry a U.S. information-reporting obligation even when its receipt is not taxable income. Before committing inherited funds to a Miami residence, review the recipient’s status, the transfer’s legal source, annual receipts and any foreign-trust involvement separately from property ownership and closing requirements.
An inheritance received abroad can make a Miami residence possible without making the paperwork simple. The essential questions arise before the purchase: Is the recipient a U.S. person? Who legally made the distribution? How much was received during the tax year? Was a foreign trust involved?
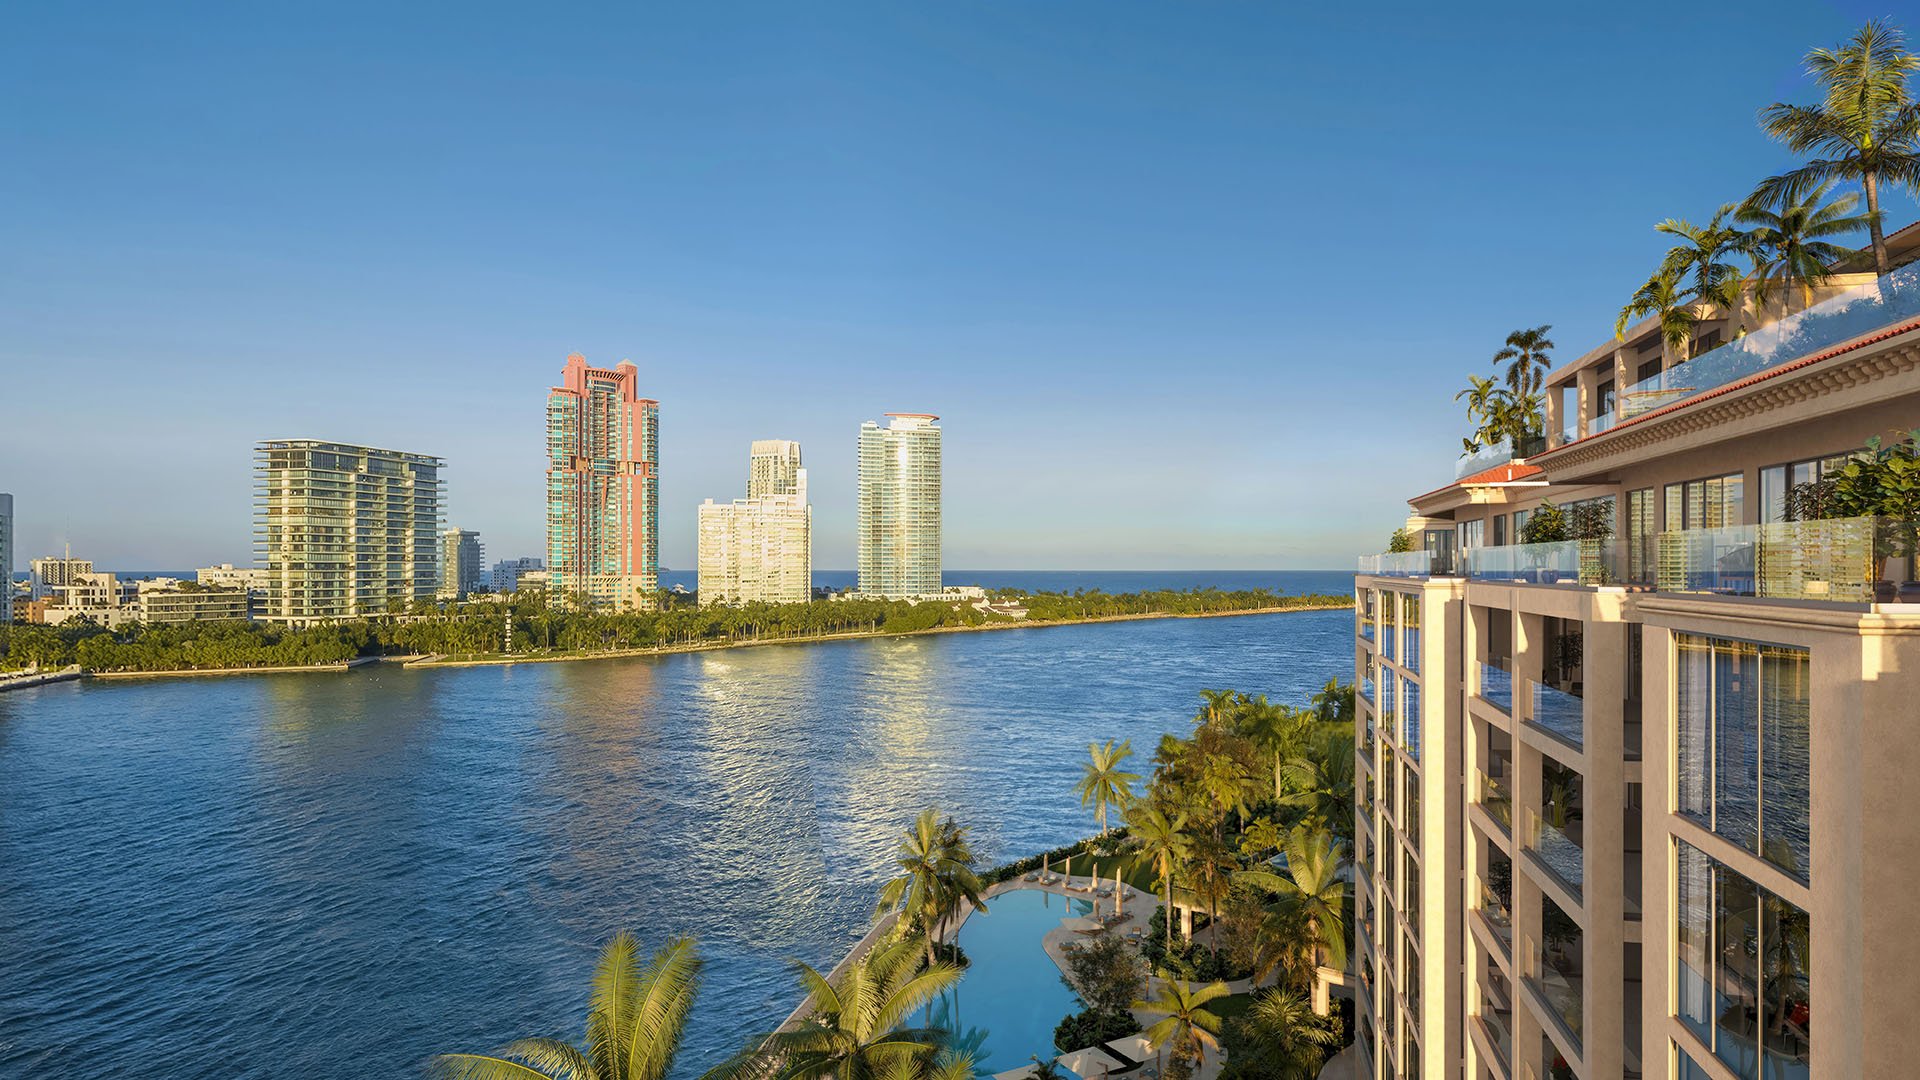
For a buyer considering The Residences at 1428 Brickell, those questions deserve attention alongside the choice of residence. The purchase price does not trigger foreign-gift reporting. The recipient’s status, the character of the transfer and the annual amount are what matter.
Foreign gifts and inheritances generally are not taxable income merely because they are received. They may still carry information-reporting obligations. Using the money for a down payment or an outright purchase does not erase an obligation created by its receipt.
A U.S. person who receives more than $100,000 during a tax year in gifts or bequests from a nonresident-alien individual or foreign estate generally must report those receipts on Form 3520, Part IV. The distinction between more than $100,000 and exactly $100,000 matters when assessing this threshold.
The review should not stop at one wire or one sender. Transfers from related foreign persons must be aggregated when the recipient knows or has reason to know of their relationship. Reviewing each receipt in isolation can therefore leave the annual reporting picture incomplete.
Once the applicable threshold is exceeded, gifts or bequests exceeding $5,000 individually generally must be separately identified. Records should preserve both the individual distributions and the annual total, rather than simply show the balance available for a property purchase.
For buyers, the practical distinction is straightforward: the amount allocated to the residence is not necessarily the amount that needs review. The inquiry concerns reportable receipts during the tax year, not just the funds ultimately used at closing.
“Inheritance” is a family description, not a complete legal classification. A direct bequest from a foreign estate and a distribution from a foreign trust require different analyses, even when both follow a death and serve the same family purpose.
Form 3520 addresses specified foreign gifts and bequests, but it also separately covers certain foreign-trust transactions, ownership and reportable distributions. A foreign-trust distribution should not automatically be tested against the $100,000 threshold applicable to foreign individuals and estates. Purported gifts from foreign corporations or partnerships have a different reporting threshold.
A buyer evaluating Four Seasons Residences Coconut Grove should therefore ask counsel to establish the distributing party’s legal identity before treating the proceeds as a straightforward estate bequest. The choice of residence does not change that classification.
This calls for early review, not simply form preparation. If trust or entity documents are needed to understand the transfer, obtaining them before purchase funds are committed gives advisers a clearer basis for analysis.
A practical preparation file should connect the inheritance to the funds intended for the purchase. This is a recommended working file, not a statutory checklist; counsel should tailor it to the circumstances.
Begin with the will or estate documents, distribution records and identification of the donor or decedent. Add the bank trail showing receipt and movement of the funds, together with currency-conversion support. If a trust or entity appears anywhere in the distribution structure, include its relevant documents rather than relying on a family summary of the arrangement.
For a Miami Beach purchase such as The Perigon Miami Beach, this preparation can proceed alongside the property review. The purpose is not to attach a tax conclusion to a particular address. It is to let advisers assess the inheritance and proposed ownership structure before the closing timetable becomes pressing.
Keep three questions distinct: what the buyer received, how the receipt should be reported and who will hold title to the residence. Resolving one does not automatically resolve the others.
Form 3520 is an information return, not simply a calculation of tax due on inherited money. Its relevance should be considered even when the recipient expects no taxable income merely from receiving the bequest.
The return generally is due on the 15th day of the fourth month after the recipient’s tax year ends. For a calendar-year individual, that is typically April 15, subject to applicable exceptions and extensions. The property’s closing date does not replace that filing timetable.
Failure to file a required Form 3520 can trigger significant information-return penalties. Foreign-gift matters and foreign-trust matters carry different penalty rules-another reason to establish the transfer’s legal character before assuming the filing is routine.
An early conversation with tax counsel should establish whether a return is required, which portions apply and which deadline governs. It should also distinguish the receipt of inherited funds from their later use to acquire the property.
Foreign-gift reporting and residential real-estate reporting address different events. Neither analysis substitutes for the other.
For a proposed Miami purchase through an entity or trust, ask closing counsel to review the ownership structure and confirm which real-estate reporting requirements, if any, apply on the scheduled closing date. Do not assume that a rule’s status at an earlier stage of the residence search will remain unchanged through closing.
That separate review does not remove an otherwise applicable foreign-gift filing obligation. The disciplined approach is to review the inheritance, confirm the proposed title structure and revisit time-sensitive closing requirements with the appropriate advisers. This article provides general information, not individualized tax or legal advice.
For a considered approach to your Miami residence search, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationForeign gifts and inheritances generally are not taxable income merely because they are received. A separate information-reporting obligation may nevertheless apply.
A U.S. person receiving more than $100,000 in a tax year in gifts or bequests from a nonresident-alien individual or foreign estate generally must report the receipts on Form 3520, Part IV.
Transfers from related foreign persons must be aggregated when the recipient knows or has reason to know of their relationship.
Once the applicable $100,000 threshold is exceeded, gifts or bequests exceeding $5,000 individually generally must be separately identified.
No. Using inherited money for a down payment or purchase does not remove a reporting obligation triggered by receiving the foreign bequest.
No. Foreign-trust distributions require their own analysis and should not automatically be tested against the threshold for foreign individuals or estates.
It generally is due on the 15th day of the fourth month after the recipient’s tax year ends, typically April 15 for calendar-year individuals. Exceptions and extensions may apply.
A practical file includes estate documents, distribution records, donor or decedent identification, bank records and currency-conversion support. Relevant trust or entity documents should also be reviewed.
Yes. Failure to file a required return can trigger significant information-return penalties, with different rules for foreign gifts and foreign-trust matters.
Ask closing counsel to confirm which requirements, if any, apply to the proposed ownership structure on the scheduled closing date. That review does not replace the foreign-gift reporting analysis.