A pre-closing framework for verifying homestead eligibility, documenting a portable Save Our Homes benefit, and budgeting for the buyer’s own property-tax assessment in Pompano Beach.
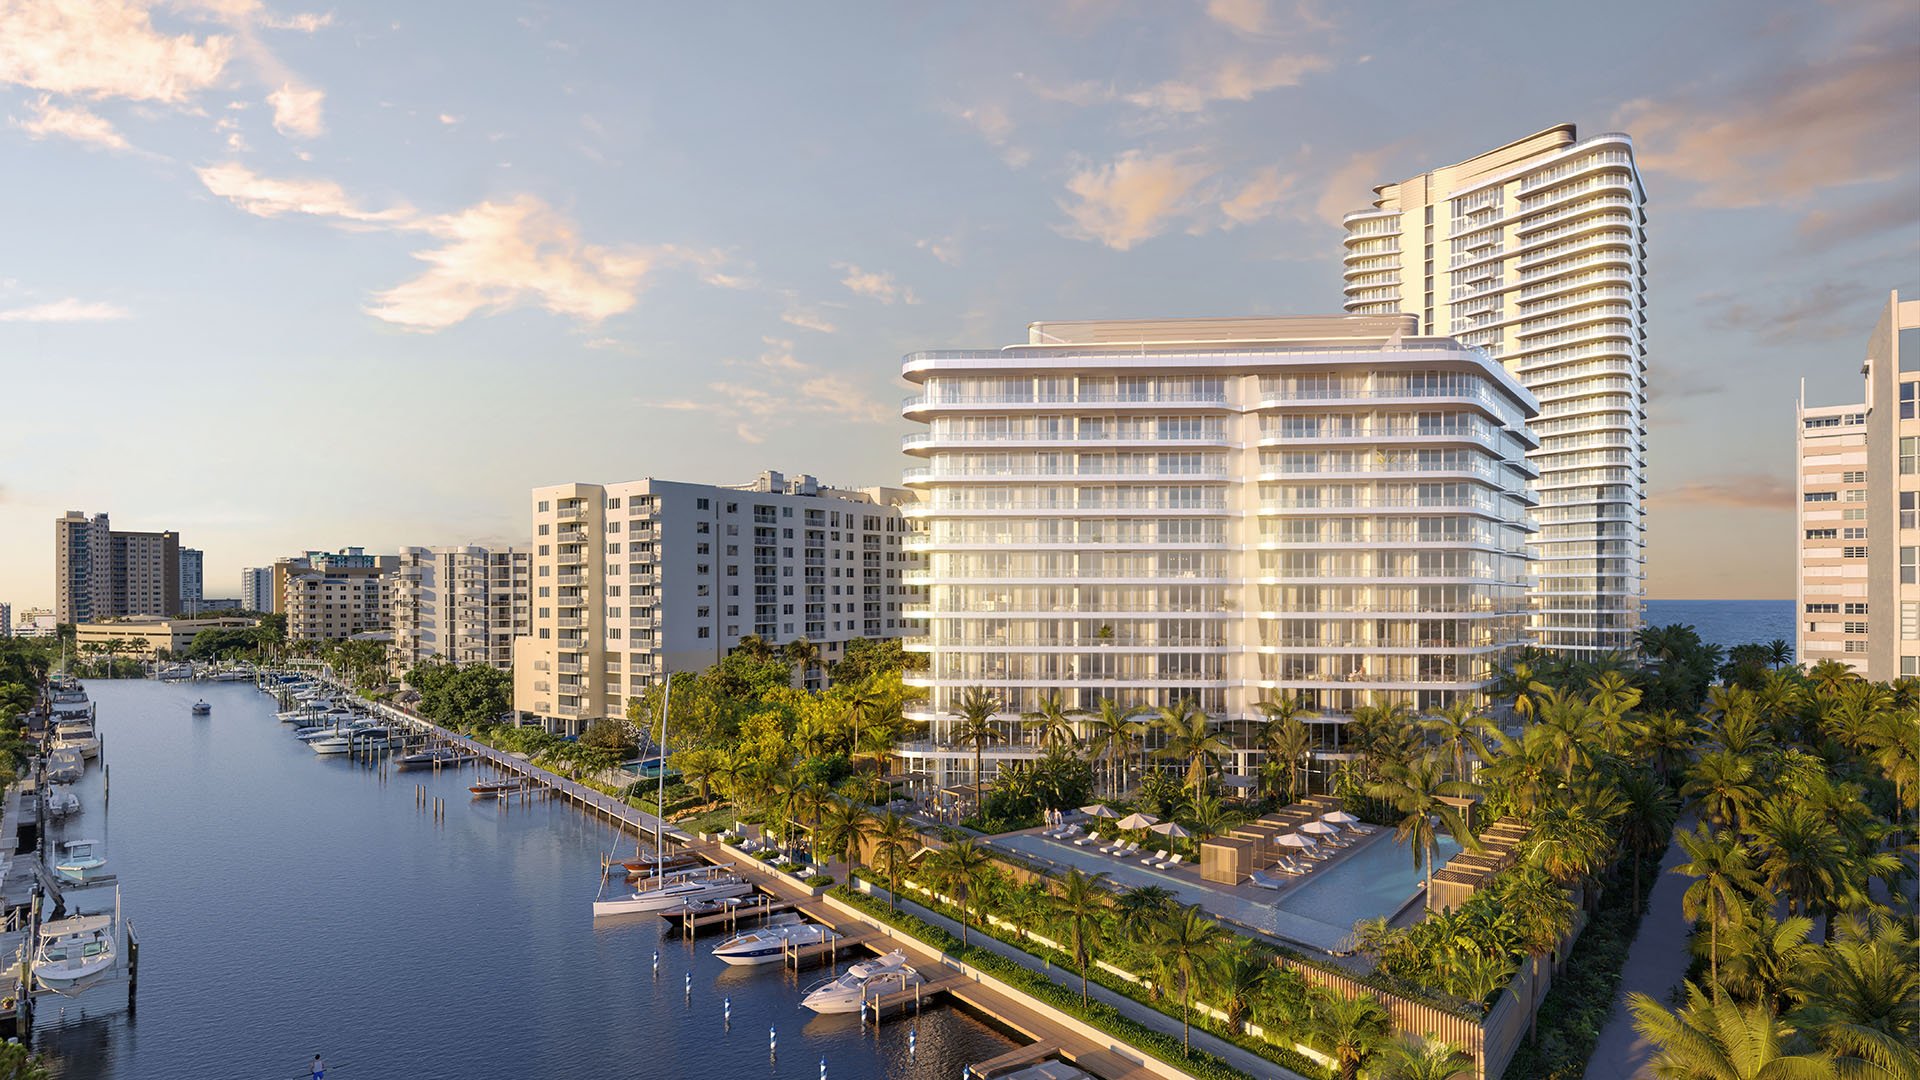
In a full-service Pompano Beach tower, the purchase decision may begin with privacy, design, and the ease of an expertly managed residence. The property-tax review demands a different focus: does the buyer qualify for homestead, can an existing Florida assessment benefit transfer, and what assessment should underpin the ownership budget?
These are three separate questions. A seller’s favorable tax bill does not establish the buyer’s future liability. Nor does a residential brand establish eligibility. For a buyer considering The Ritz-Carlton Residences® Pompano Beach, the essential review concerns the proposed ownership, intended use, and relevant tax-year dates-not the service offering.
The pre-closing objective is a documented tax position: an eligibility review, a verified portability calculation where applicable, and a post-sale tax estimate that does not rely on someone else’s benefits.
A condominium can qualify for Florida homestead exemption when the buyer satisfies ownership and permanent-residence requirements as of January 1 of the applicable tax year. Full-service amenities do not change that test. A residence used solely for vacations or investment does not qualify for the buyer’s permanent-residence homestead benefits.
Start with two questions: will the unit genuinely be the buyer’s permanent home, and does the proposed ownership interest qualify? If title will be held through a trust or entity, have counsel review the structure before closing and confirm eligibility requirements with the county property appraiser. Residency alone should not be treated as sufficient.
The distinction matters equally when evaluating Armani Casa Residences Pompano Beach. Project selection and homestead eligibility are separate decisions; neither luxury branding nor a lifestyle intention substitutes for qualifying ownership and use.
A midyear closing generally makes the following year the buyer’s first eligible homestead year, provided ownership and permanent residence are established by that January 1. Record the intended qualifying year rather than assuming the closing date resolves eligibility.
Before closing, review the unit’s Broward County property record for existing exemptions, just or market value, assessed value, and taxable value. Do not treat these figures as a single measure of what the buyer will owe.
Homestead exemption reduces taxable value. Save Our Homes, commonly abbreviated SOH, generally limits subsequent annual increases in a homesteaded property’s assessed value to the lesser of 3% or the applicable CPI change. These are distinct benefits. The assessment limitation is not a guaranteed percentage cap on the final tax bill.
For a seller with SOH protection, the difference between just value and assessed value reveals the accumulated assessment benefit. That gap is a warning against carrying the seller’s figures directly into the buyer’s budget.
A buyer does not inherit the seller’s SOH-capped assessment. A sale can trigger reassessment at current just value for the new owner’s assessment base. Request an estimated post-sale assessment that reflects the buyer’s circumstances, then separate confirmed benefits from assumptions awaiting approval.
Portability transfers an eligible SOH assessment difference from a previous Florida homestead to a new Florida homestead. It does not transfer the seller’s tax position or automatically move the old homestead exemption to the replacement residence.
The starting calculation is the prior homestead’s just value minus its SOH-limited assessed value. Verify both figures and the prior home’s qualifying homestead year with that property’s appraiser before treating the difference as available.
The maximum portable assessment benefit is $500,000. This is an assessment benefit, not a tax credit or cash payment. Statutory formulas govern the transferable amount; the full prior difference should not automatically be subtracted from every replacement home’s value.
For a buyer considering Ocean 580 Pompano Beach as a replacement permanent residence, the relevant figure is the benefit transferable to that purchase-not simply the largest figure on the previous home’s record. Request a calculation tied to the proposed new homestead before incorporating portability into the ownership budget.
Portability eligibility uses a three-tax-year window tied to the prior qualifying homestead year. It is not a rolling three years measured from the sale’s closing date.
The pre-closing timeline should identify three items: the prior qualifying homestead year, the intended new qualifying homestead year, and the January 1 by which ownership and permanent residence must be established. Have the applicable window confirmed against those tax years.
Closing within an assumed window is not the same as establishing a qualifying replacement homestead. Keep the acquisition and eligibility timetables side by side, particularly when the residence will not become the buyer’s permanent home immediately.
Apply the same discipline to a comparison involving Waldorf Astoria Residences Pompano Beach: evaluate taxes from the buyer’s expected post-sale position rather than assuming the seller’s assessment will continue.
Ask the advisory team to prepare three distinct budget scenarios. First, estimate the post-sale position without assuming homestead or portability. Second, show the position with the buyer’s qualifying homestead benefits. Third, include portability only to the extent its amount and timing have been verified, identifying any outstanding approval.
These are planning scenarios, not promises of a final bill. They reveal how much the budget depends on a particular eligibility outcome. If a benefit remains unresolved before closing, keep that uncertainty explicit rather than embedding an optimistic figure in recurring ownership costs.
Apply for the new homestead using Form DR-501 and request portability using Form DR-501T with the property appraiser in the new home’s county. The standard filing deadline is March 1 of the tax year for which the benefits are sought; the January 1 eligibility requirements still apply. Broward offers online homestead filing.
Assign responsibility for submission, retain the application records, and keep prior homestead documentation with the closing file. After filing, review the August TRIM notice to confirm the new assessment and portability treatment, and promptly question discrepancies.
The closing file should leave no ambiguity about the intended qualifying year, proposed ownership structure, portability assumptions, or tax estimate. This provides a clearer view of carrying costs before the purchase and a defined verification task afterward. Confirm transaction-specific eligibility and calculations with counsel and the appropriate property appraiser.
For a considered approach to your next Pompano Beach residence, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationYes, if the buyer meets the ownership and permanent-residence requirements as of January 1 of the applicable tax year. Full-service amenities do not determine eligibility.
No. A unit used solely as a vacation home or investment property does not qualify for the buyer’s permanent-residence homestead benefits.
Do not assume so. Confirm that the proposed ownership structure satisfies homestead ownership requirements before closing.
Homestead exemption reduces taxable value, while Save Our Homes generally limits subsequent annual increases in assessed value. The assessment limit is not a guaranteed cap on the final tax bill.
No. A buyer does not inherit the seller’s capped assessment, and a sale can trigger reassessment at current just value for the new owner’s assessment base.
The maximum portable SOH assessment benefit is $500,000, subject to eligibility and statutory formulas. It is not a tax credit or cash payment.
Eligibility uses a three-tax-year window tied to the prior qualifying homestead year. It is not a rolling three years from the sale’s closing date.
Generally, the first eligible year is the following year, provided qualifying ownership and permanent residence are established by that January 1.
Use Form DR-501 for homestead and Form DR-501T for portability with the new home’s county property appraiser. The standard filing deadline is March 1 of the year for which benefits are sought, with January 1 eligibility requirements also applying.
Review the August TRIM notice for the new assessment and portability treatment. Promptly question discrepancies rather than assuming the applications produced the expected result.