A furnished Miami residence deserves a transparent asking price: one total, supported allocations for real estate and contents, and a clear inventory of what actually transfers.
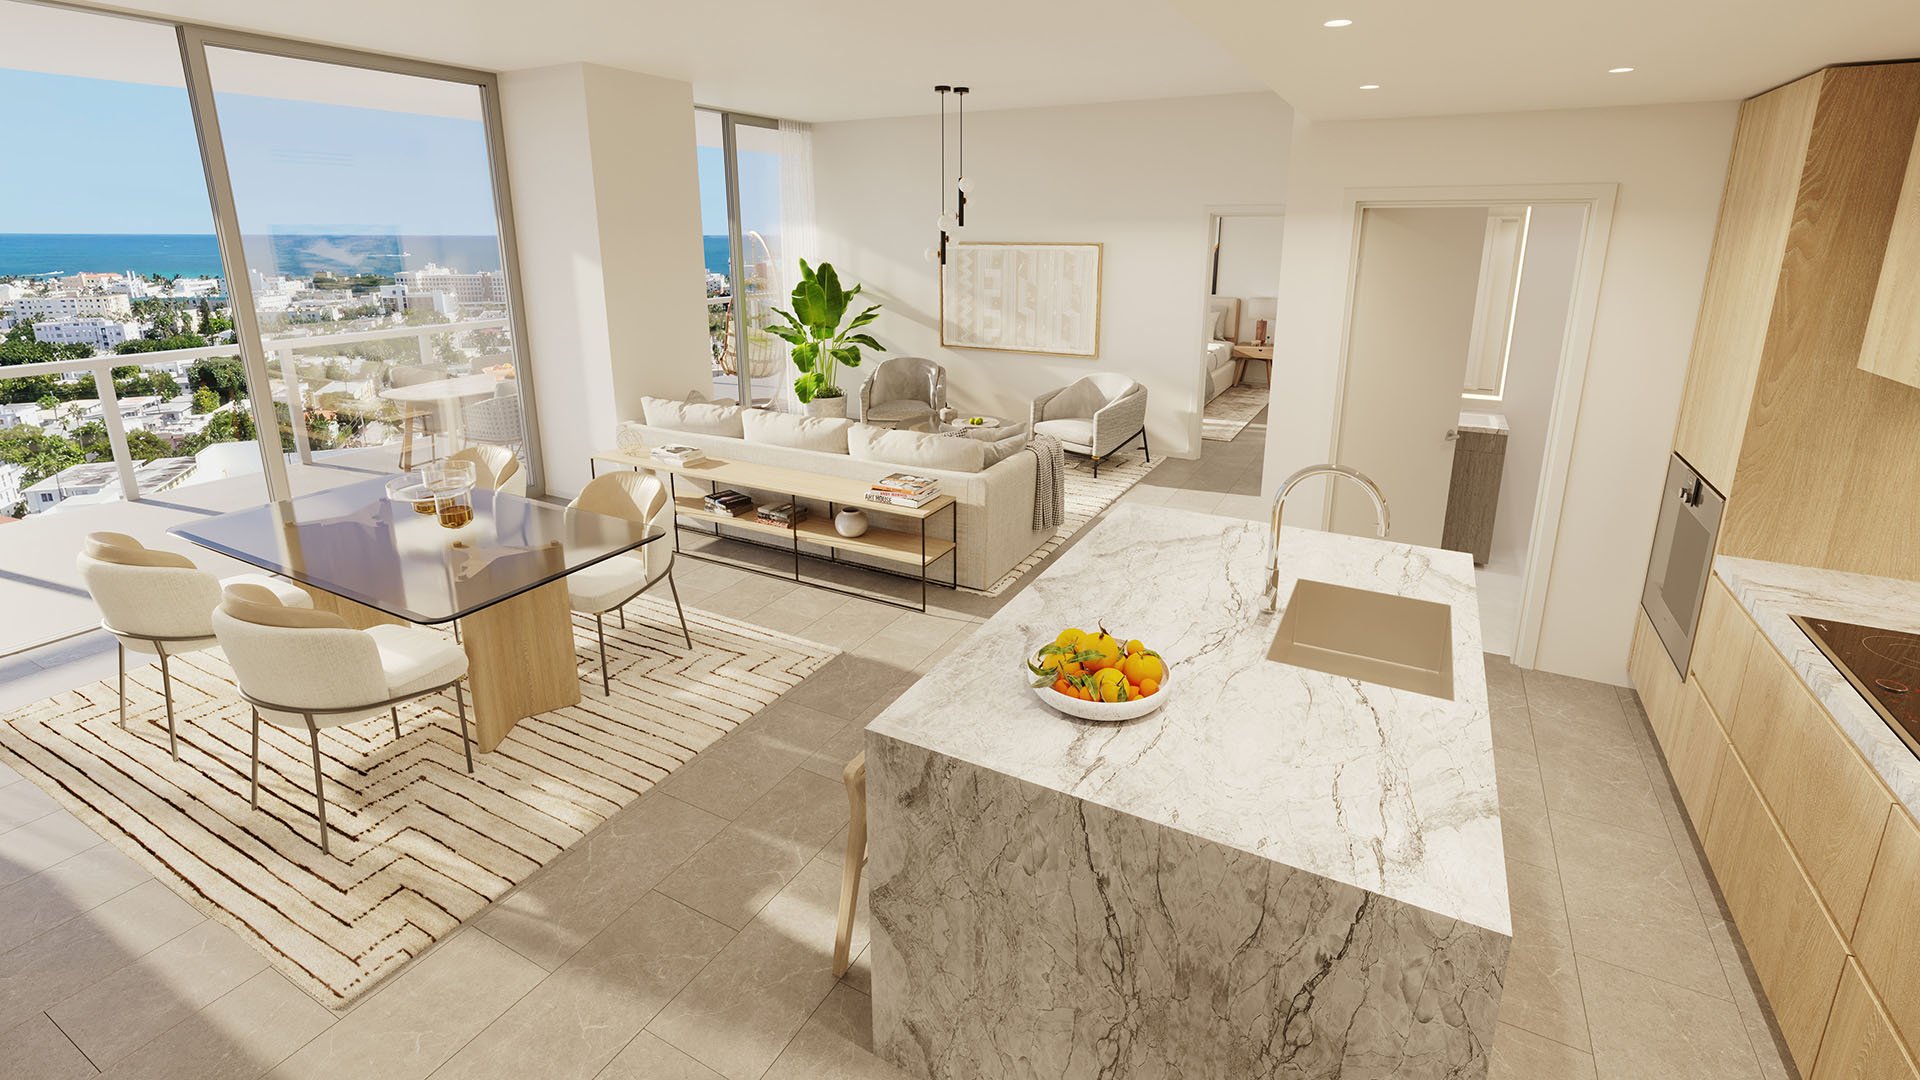
A furnished Miami residence can be presented as a complete environment, but its asking price should distinguish the property from the possessions. The rooms may read as one composition; the economics require greater definition. A buyer should understand how much of the total relates to real estate and how much to identifiable personal property that will actually transfer.
The clearest presentation is straightforward: one total asking price, a real-estate component, and a contents component. The two components must add up to the total. This is a recommendation for transparency, not a Miami-specific legal requirement. The purpose is to make a furnished offering understandable without allowing the interiors to obscure the value of the residence itself.
A seller need not diminish the appeal of a furnished home to explain its price. The residence can still be offered as a complete package, with the allocation displayed alongside the total rather than deferred to a later discussion.
A practical presentation has three lines:
Total asking price: the amount sought for the complete offering.
Real-estate allocation: the amount assigned to the residence.
Contents allocation: the amount assigned to the personal property included.
For a buyer considering a furnished offering at Una Residences Brickell, the useful question is not simply whether furniture is included. It is whether the proposed allocation is supported and the included items are identifiable. This is a transaction-level question, not a statement about any particular residence’s furnishing package.
Treat the asking allocation as a documented proposal. If the negotiated package changes, revisit the figures so the final allocation reflects the property and contents actually being purchased.
“Furnished” is a description, not an inventory. Before discussing the contents allocation, establish precisely which personal property it covers. Furniture is personal property for federal tax purposes, but a room-by-room review still matters: an attractive presentation does not establish that every visible object is included.
Prepare an itemized schedule identifying the furnishings that transfer and clearly separating exclusions. Supporting details can include descriptions, photographs, purchase records, and condition notes. These connect the proposed value to identifiable objects rather than a general impression of the interiors.
For a furnished purchase at Setai Residences Miami Beach, the same principle applies: evaluate the residence and the specified contents, rather than assuming everything seen during a viewing will remain. The inventory should resolve that distinction before the allocation becomes a negotiating point.
If there is uncertainty over whether an installed item belongs with the real estate or the contents, have the transaction advisers resolve its treatment. Do not assign it to either category merely to achieve a preferred split.
The contents component should reflect defensible fair market value. An original invoice can establish what was paid, but not necessarily what the same furnishing is worth today. Condition and depreciation are relevant valuation considerations.
That distinction is particularly important when a seller has invested heavily in the interiors. Personal expenditure and current market value answer different questions. Purchase records remain useful evidence, but they should not replace an assessment of the actual items being transferred.
The larger the contents allocation, the more important independent valuation evidence becomes. An appraisal supported by an inventory and relevant records is stronger than a substantial figure inserted into an agreement without explanation.
For buyers evaluating a furnished residence at Jade Signature Sunny Isles Beach, the discipline is the same: ask what supports the contents figure. A meaningful allocation should be explainable item by item or through a supported valuation of the identified collection-not justified solely as a percentage of the asking price.
Separating the components helps buyers avoid treating a combined property-and-contents price as real-estate value alone. Keep that distinction visible when comparing furnished and unfurnished offerings. Otherwise, a difference in the package can be mistaken for a difference in the underlying residence’s pricing.
This does not mean simply subtracting whatever number a seller assigns to furniture and accepting the remainder. Both components need support. An inflated contents figure can distort the apparent real-estate price just as an unexplained all-in figure can obscure it.
The same reasoning applies when considering a furnished offering at Park Grove Coconut Grove. Evaluate the proposed real-estate component on its own merits, then examine the contents separately. Neither the project name nor the presentation of the interiors replaces evidence supporting the allocation.
A sale-price allocation is not the same as tax basis. Basis generally begins with acquisition cost and may require adjustments. Gain generally depends on the amount realized compared with the relevant asset’s adjusted basis; the entire allocated price is not necessarily taxable gain.
Keep purchase and improvement records available for the tax review. Where depreciation applies, it can affect adjusted basis. Moving a larger share of the price into furnishings is therefore not a guaranteed tax-saving strategy, especially when their value or actual transfer cannot be substantiated.
Florida also distinguishes real-property assessment from taxable tangible personal property. Household goods associated with qualifying homesteaded property and furnishings used in rented or leased property can receive different treatment; rental furnishings may be taxable. These assessment distinctions do not establish a required percentage for dividing a furnished sale price.
Before committing, reconcile the total price, both allocations, and the inventory. Confirm that the contents being valued are the contents being transferred. If items are removed or substituted during negotiations, review whether the supporting valuation and allocation remain appropriate.
Ask legal and tax advisers to review the transaction’s specific treatment rather than assuming a pricing split settles every issue. The essential standard is consistency: a clear total, defensible component values, and documentation that matches the actual exchange. Precision does not detract from a beautifully furnished residence. It makes the purchase easier to understand.
For a considered approach to South Florida’s furnished residences, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationShow the total asking price alongside separate real-estate and contents allocations. The two components should add up to the total.
It is a transparency recommendation, not an established Miami-specific legal requirement. Transaction advisers should review any requirements applicable to the particular sale.
No arbitrary percentage should replace evidence of fair market value. Both the real-estate and contents allocations need defensible support.
Not automatically. Purchase records are useful, but current condition and depreciation are relevant to valuation.
It should identify the personal property included in the sale and distinguish exclusions. Descriptions, photographs, and condition notes can help connect the valuation to the actual items.
Independent valuation evidence is particularly useful for substantial contents allocations. It provides stronger support than an unexplained contractual figure.
Yes. Assigning a portion of the price to contents is insufficient without evidence that identifiable personal property was included in the sale.
Not by itself. Gain generally depends on the amount realized compared with the relevant asset’s adjusted basis.
Yes. Furnishings used in rented or leased property may be taxable, while household goods associated with qualifying homesteaded property can receive different treatment.
No. Unsupported values or inadequate evidence of the transfer can expose an allocation to challenge, and tax consequences depend on the transaction’s specific facts.